• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

General Personal Finance Blog

19 Money Saving Challenge Ideas You Need To Start Today

June 24, 2025 By Ana Rose

Saving money can become overwhelming and draining, especially when unexpected expenses pop up at the worst times possible. Whether it’s saving for a future financial goal, helping your kid get into college, or just the simple act of saving for an emergency, saving money can be a lifesaver when the need arises. This article will help you explore the 19 best money-saving challenges that are fun and motivating, offering simple and manageable steps to help you stay consistent with the process.

1. 52-Week Savings Challenge

The 52-Week Saving Challenge" graphic: Woman putting coin in piggy bank next to a table with weekly saving amounts.

One of the most popular strategies till date is the 52-week savings challenge that includes starting off by saving a small amount by gradually increasing it to bigger steps. You save up $1 in week 1, $2 in week 2, $3 in week 3, and so on, until you reach $52 in week 52. 

By the end of the year, you’ll have saved up an amount of $1,378 without even realizing, making this challenge a considerable savings option. 

2. No-Spend Challenge

Another effective way to save money is through the no-spend challenge that is all about cutting off all the non-essential spendings. After the paycheck comes, pay your rents, bills, and utilities, however, unnecessary spendings like coffee runs, subscriptions, online shopping, or takeouts should be avoided. 

It may seem little at first, but these non-essential spending cut off a huge amount from your income, making this challenge an effective way to get aware of your spendings. 

3. Pantry Challenge

If you feel like you’re an impulsive buyer, this pantry challenge will work the best for you. This challenge is all about utilizing the goods and ingredients present in the pantry instead of making grocery runs for a week or two.

This challenge enhances creativity and problem-solving, urging you to make something of the resources present and reducing food wastage.  

4. 30-Day Minimalist Challenge

Remove one unnecessary item from your home each day for a whole month. So the next time you go shopping, you wouldn’t have to worry about replacing the old item with a new one or buying a similar item. 

This 30-day minimalist challenge offers decluttering of home and clearing up of physical and mental space. 

5. Weather-Based Savings Challenge

For something fun and seasonal, go with the weather-based savings challenge that includes picking a specific weather like rainy, sunny, cloudy, or snowy, and everytime that weather shows up, deposit a fixed amount like $5 or $10 into the savings. 

This challenge is a fun one, driving the motivation to save money through engaging and playful ways. 

6. Round-Up Challenge
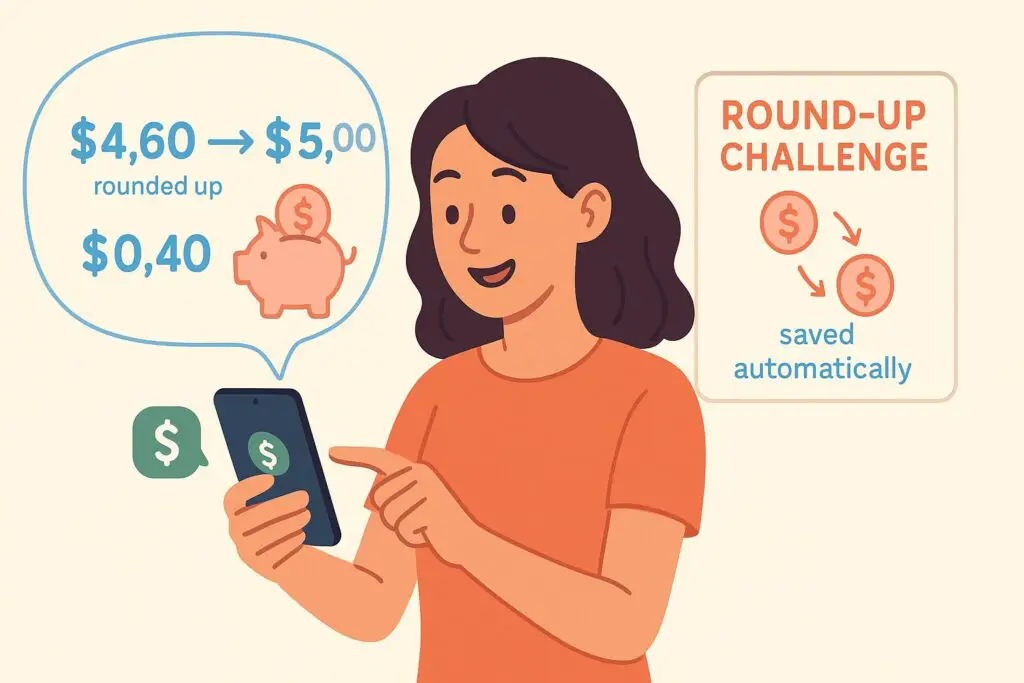
Woman using phone showing a transaction rounded up, with change going to a piggy bank icon for a "Round-Up Challenge."

For our digital spenders, this round-up challenge is made specifically for you. Every time you make a purchase, round it up to the nearest dollar and transfer the remaining amount into savings.
Many banking apps make it easier by automating this process in the background. If you prefer to do it manually, set up a weekly transfer based on your estimated round-ups, making this challenge easier for you to carry out. 

7. 100 Envelope Challenge

For an fun and engaging challenge, pick the 100 envelope challenge where you label 100 envelopes from 1-100. Randomly select an envelope each week and put the corresponding amount in it. 

This method is easy and adds up quickly, leading to an amount of $5,050 by the end, offering a challenge with clear visual goals.

8. 1% Income Challenge

If percentages feel easier than fixed amounts, this challenge is the best fit for you. Instead of saving up a fixed amount every month, just save up 1% of your income. 

For example, if someone’s earning $5,000 every month, 1% of that income would be $50. This challenge offers you a way to set aside a small amount which can gradually grow big into a savings that’s more meaningful and useful. 

9. Found Money Challenge

The found money challenge is an effortless and easy one since you don’t have to worry about adding money to this challenge from your income or paycheck. Simply put, this challenge includes unexpected tax refunds, rebates, cash gifts, or loose change you find around the house. 

Since this money isn’t the part of your regular budget, you don’t have to worry about saving it!

10. Daily $1 Challenge

Another easy and simple way to save money is through the daily $1 challenge, that includes saving a dollar each day. Keeping up with this challenge for a year can lead to saving up $365, which is quite a decent amount. 

Moreover, since the amount is really small, it’s nearly impossible to justify skipping it. So to save up money side-by-side, this daily $1 challenge can be your go-to!

11. No Takeout Month
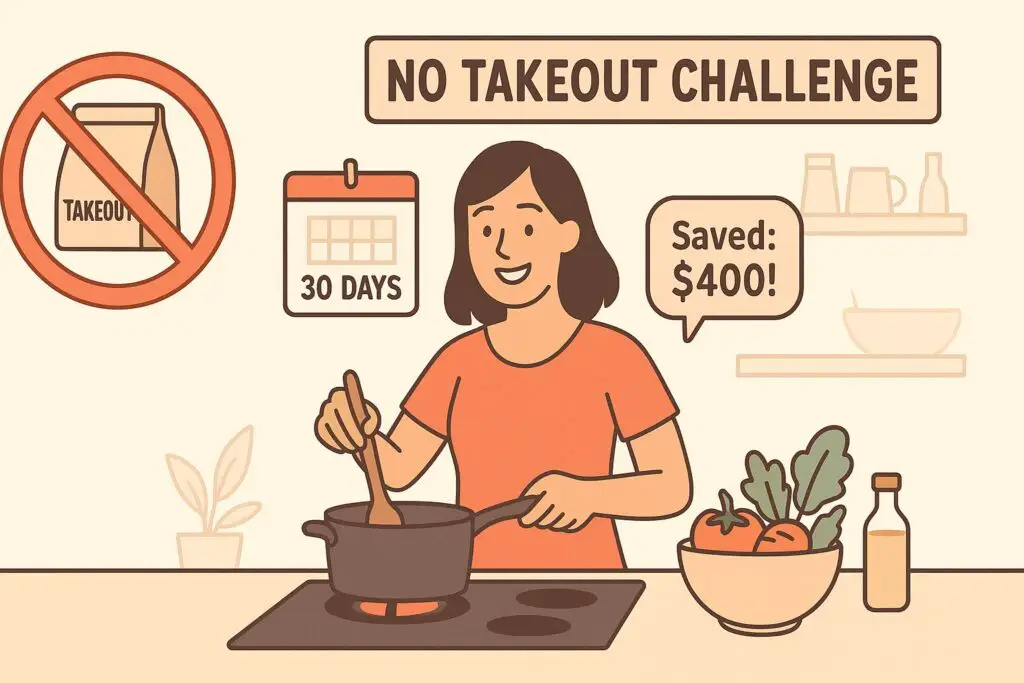
Woman cooking at home, with a crossed-out takeout bag and calendar showing "No Takeout Challenge," saved $400.

To save money spent on food, take up a no takeout month challenge. One of the most effective habits you can adopt, this challenge includes committing to cook and eat homemade meals, instead of relying on takeouts. 

The savings from restaurant meals and skipping delivery fees can save you around $300-$500, depending on your spending and eating habits. 

12. Zero-Based Budget Challenge

Assign your income to specific categories until there’s no unassigned money left. For example, allocate 50% of your income to wants, that include rent, utilities, and bills, 30% to your wants, that include dining out, takeouts, entertainment, or subscriptions. Lastly, 20% of your income goes to savings, leaving no unallocated money and income behind. 

This challenge creates a sense of responsibility and accountability, making money saving a bit easier for you to follow. 

13. $5 Bill Rule

For a simple and surprisingly effective way to save money, go with the %5 bill rule challenge that is all about the simple act of stashing away a $5 bill in a jar, everytime you receive it. Instead of keeping it with you, save it in a jar or an envelope so you can effectively avoid spending it unknowingly. 

This method is a simple yet highly useful strategy to save money that can help you gather a large amount in less time, if paid attention to.

14. Declutter & Sell Challenge

If your home is filled with items you don’t use anymore, the Declutter and Sell Challenge can fit you the best! Make a list of the items you no longer need and sell one unused item each week through online platforms. 

The money you earn through selling the goods go straight to the savings account, helping you in decluttering and making money through the process. 

15. Coin Jar Challenge

The Coin Jar Challenge is an old-school one, but a timeless classic for a reason. Drop your spare change into a jar every day, and once it’s full, take it to the bank or a coin machine. People report saving hundreds per year through this passive habit.

This challenge may seem simple, but is an effective way to stay consistent and motivated to save money.

16. Savings Bingo Challenge
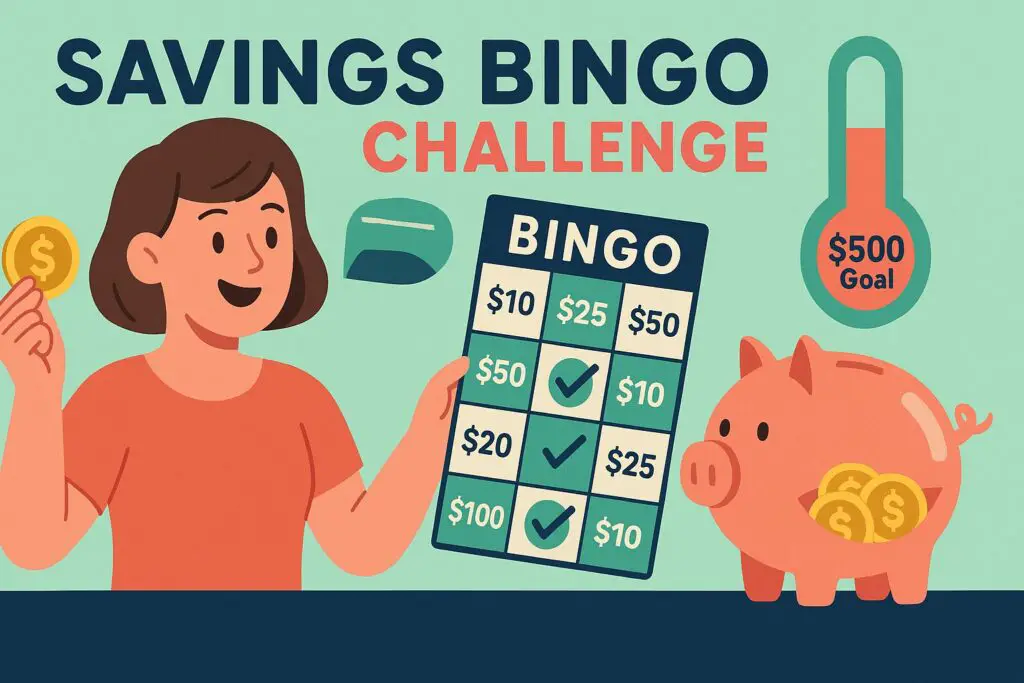
Woman holds a coin and a "Savings Bingo Challenge" card with marked amounts, next to a piggy bank.

If you enjoy playing games then turn saving into a personal competition with the Savings Bingo Challenge. Create a bingo card with varying amounts in each square (e.g., $10, $20, $50), then choose one to save each week. Once you’ve filled the card, you’ll have met your savings goal in a fun and interactive way.

17. Subscription Audit Challenge

In today’s world, where everything runs on subscriptions, the need to monitor them becomes essential. List every monthly subscription you have, whether it’s a streaming platform, music subscriptions, or cloud storage, and cancel at least one. 

You can also discover the subscriptions you no longer need and redirect the amount going to those specific subscriptions to savings. 

18. One-In-One-Out Rule

The One-In-One-Out Rule is helpful for those who shop regularly. Each item you bring home, you must donate, sell, or toss an old one. To supercharge the savings element, match the price of the new item by transferring the same amount into savings. 

This method discourages impulsive buying and encourages purchasing thoughtfully. 

19. Goal-Trigger Challenge

The goal-trigger challenge is a fun and playful way to save money. Each time you’re tempted to perform a specific action or behavior, deposit a fixed amount into the savings account. For example, if you find yourself tempted to shop online or order food, transfer an amount of $10 into the savings account. 

Conclusion

Adopting money saving habits is not just a financial experiment, but more a vision with strategies. Whether it’s saving money through the 52-week challenge or using jars and envelopes to save money until they gather up to a large amount, each challenge is unique in its own and offers a fun and interactive way for you to stay motivated and consistent with the process. Money saving might feel like a drag but if done right, you’ll find out that it doesn’t always have to be a burden. So pick one challenge that speaks to you, stick to it, and watch your financial confidence grow!
The Best Finance Books To Read For Beginners

June 23, 2025 By Ana Rose

Making money can be draining and overwhelming, especially when you’ve just started. From budgeting and saving to invest and build wealth, the financial world is a twisted one that comes with its own rules and twists. 

Whether you’re saving up for a future financial goal, paying off a debt, or saving up for college, reading finance books can significantly guide you in making smart financial choices.

Why Reading Books is Important?

Reading books is essential, especially if you’re a beginner, figuring out a way to navigate through the challenges and complexities of the financial world. Books offer depth, clarity, relevant insight, and lasting knowledge that social media platforms and posts often lack. 

Whether it’s learning how to budget reasonably, deal with financial crises, paying off debts, managing student loans, or just simply saving up for a big future financial goal that you’ve set, books offer structured guidance, step-by-step advice, and real-world examples that make the plans and strategies highly practical and applicable. 

By taking out time to read, you not only gain valuable insights and information but also develop the focus and confidence you need to make firm financial decisions in the future. 

1. Rich Dad Poor Dad by Robert Kiyosaki

Rich Dad Poor Dad by Robert Kiyosaki

Written in 1997 by Robert Kiyosaki, the author talks about his rich dad, the father of his best friend, and his poor dad, his biological father, and how both the men in his life shaped his thoughts and thinking pattern about money and investment. 

Kiyosaki introduced concepts like assets versus liabilities, financial literacy, and financial independence, urging people to think like an entrepreneur rather than relying solely on the traditional employment norm. 

It’s an eye-opening read that challenges the traditional ways around money, jobs, and success, making it a must-read for people stepping into the financial world. 

2. The Psychology of Money by Morgan Housel 

The Psychology of Money by Morgan Housel

Morgan Housel in his book The Psychology of Money, talks about how emotions, thoughts, feelings, and behavior shape financial success. The author in his book explains that financial success is more about behavior than knowledge and insight.  

This highly readable book makes you think and pour thought into the “whys” of the financial world, helping you understand the emotional aspect of money-making, which often goes unnoticed. 

Housel in his book shares his insights regarding the role of luck, patience, risk, and greed in the financial world, making it one of the top books for newbies who want to explore the financial world more rigorously. 

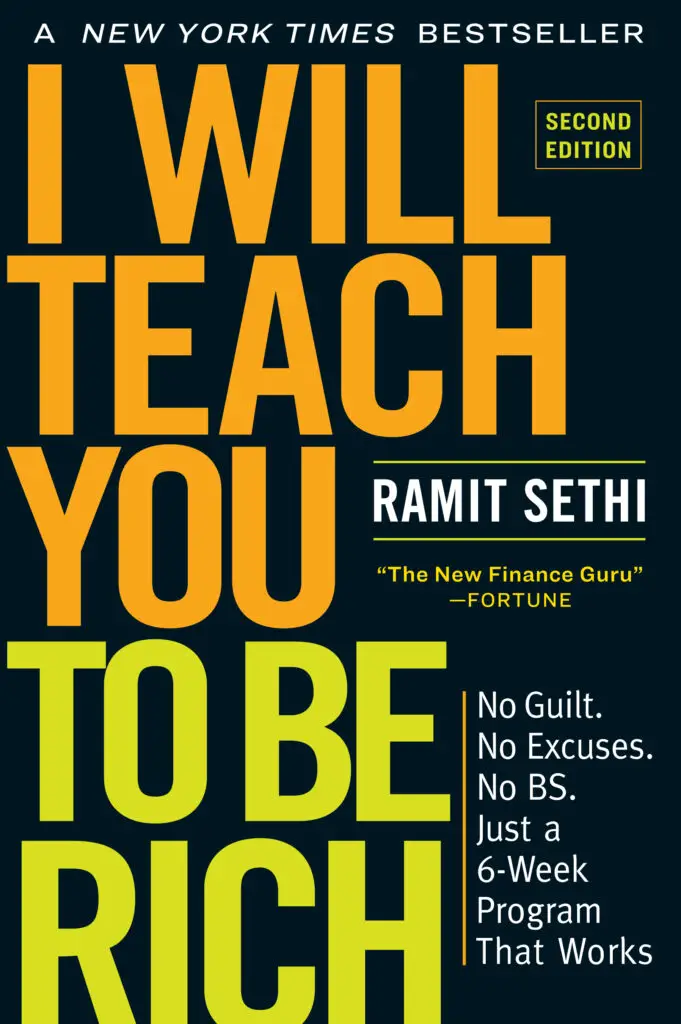
3. I Will Teach You To Be Rich by Ramit Sethi

I Will Teach You To Be Rich by Ramit Sethi

Written by Ramit Sethi in 2009, this book delivers a humorous yet highly-practical six-week program for money-making, particularly for millennials and Gen-Z to get their financial status in line. 

Sethi, in his book, helps readers develop a highly applicable financial plan that includes budgeting, saving, and spending money on things that truly matter. 

The step-by-step guidelines and a tone that feel like advice coming from a financially stable bestfriend, makes this book perfect for people who don’t know where to start from when stepping into this complex world of finance. 

4. The Millionaire Next Door by Thomas J. Stanley and William D. Danko

The Millionaire Next Door by Thomas J. Stanley and William D. Danko

Written by Thomas J. Stanley and William D. Danko, The Millionaire Next Door is an insightful book based on extensive research on the behaviors of American millionaires. 

This book discards the myth that millionaires drive flashy cars and live in gigantic mansions. In reality, most millionaires live a decent life, save consistently and invest their money wisely. The authors reveal that healthy habits like budgeting, investing, and avoiding debt can help you understand that wealth comes from restraint and disciplined living rather than a high income.

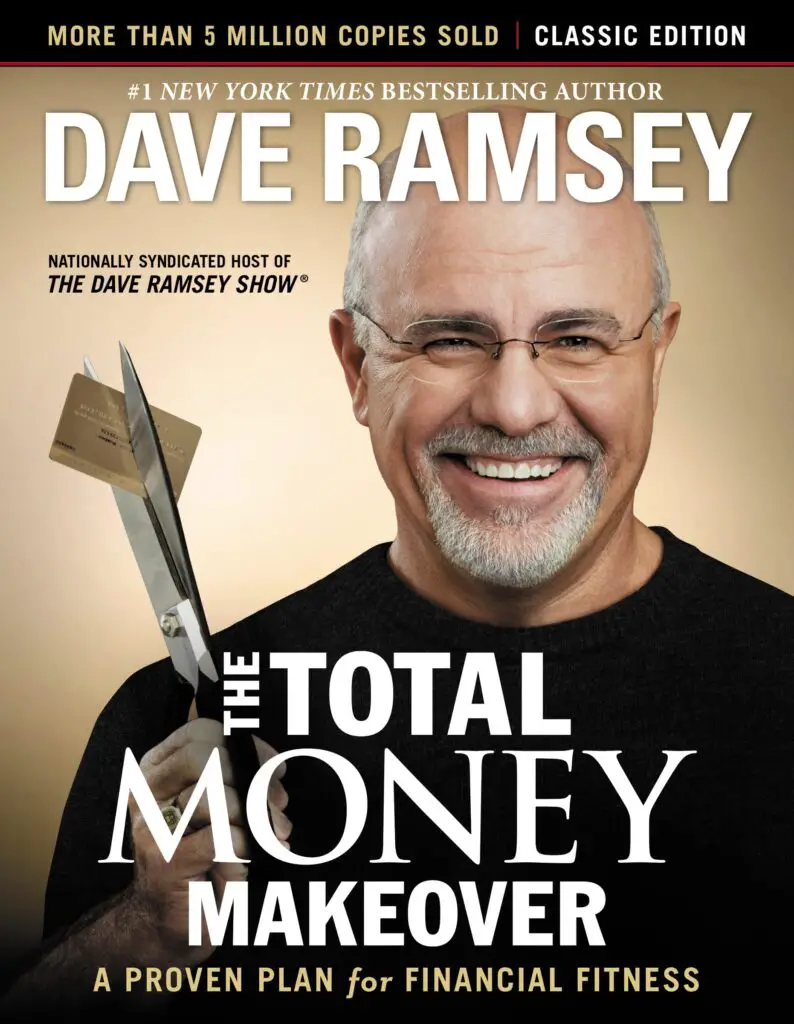
5. The Total Money Makeover by Dave Ramsey

The Total Money Makeover by Dave Ramsey

Firstly published in 2003 by Dave Ramsay, The Total Money Makeover is a simple and straightforward guide for getting out of debt, saving for a big future financial goal, or building long-term wealth through understandable steps. 

This New York Times bestseller has helped thousands of people get out of a financial crisis with the help of America’s favorite finance coach, Dave Ramsey. Even though the situation may feel like a dead end, through smart thinking and problem-solving skills, you can pay off a debt, begin to invest smartly, and make more of your resources. The principles offered in this book are not just fictional based, they’re based on actual results, making this book one of the best finance books to read for beginners, helping them start somewhere. 

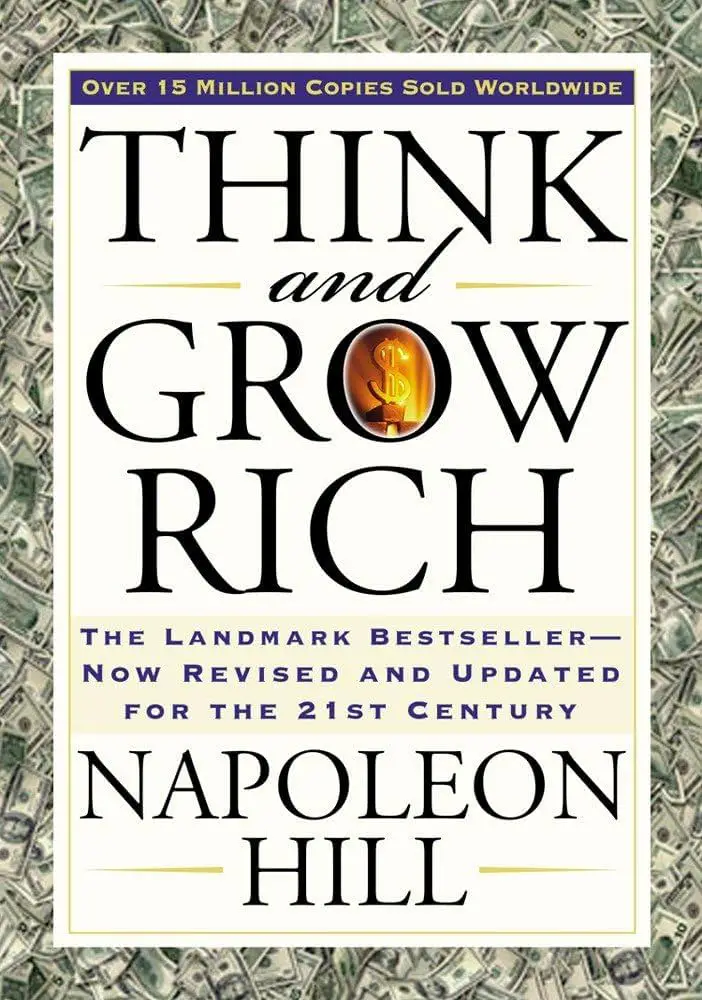
6. Think and Grow Rich by Napoleon Hill

Think and Grow Rich by Napoleon Hill

Written by Napoleon Hill and Rosa Lee Beeland in 1937, this book is a classic one that guides its readers on how to control your destiny by controlling your mind and thinking. While it may sound superficial, the authors believe that controlling your thoughts and thinking can somehow help you control your destiny and luck. 

Each chapter brings a new and unique perspective that can significantly change how you see people, money, psychology, and develop a new perspective. Regardless of your profession and business, this book offers a beautiful and unique perspective to see things, making it perfect for beginners to read. 

While not a traditional finance book, this book is known for shaping the mindsets of financially successful people, making it a relevant read for people, even today. 

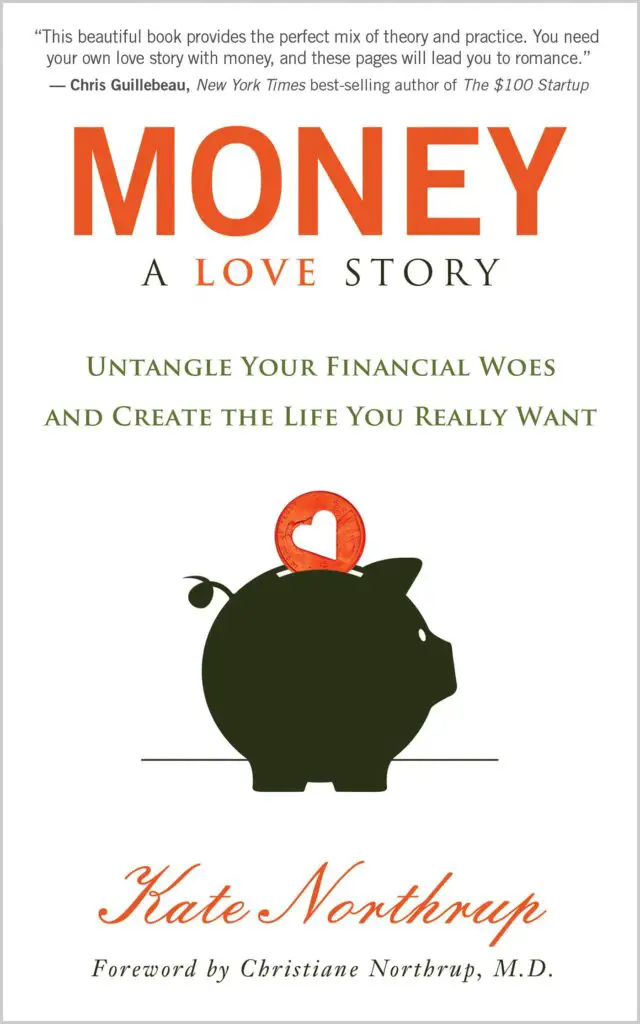
7. Money: A Love Story by Kate Northrup

Money: A Love Story by Kate Northrup

Put together by Kate Northrup, this book beautifully combines self-help with personal finance. Northrup describes the emotional aspects, healing, and self-worth as essential components when it comes to improving your financial situation. 

The book encourages women to explore their money mindset, approach it with confidence, let go of any fear or guilt, and chase the money-making goals with compassion and empowerment. This book offers a more holistic and soulful approach to improving financial status, making it a must-read for people exploring this complex world, urging them to look beyond numbers and spreadsheets. 

8. Broke Millennial by Erin Lowry

Broke Millennial by Erin Lowry

Erin Lowry in her book Broke Millennial, talks about how 20 to 30 year olds can navigate through the financial challenges with effectiveness. From managing student loans to budgeting smartly, this book offers a simple and straightforward advice to its readers, leaving no room for ambiguity.

The author uses a humorous tone accompanied by fun personal anecdotes, making this book fun and engaging to read. Moreover, Lowry makes financial concepts easy to digest, ending each chapter with a call to action. 

The practical and easy step-by-step guidance makes this book a considerable option for people beginning their financial journey. Whether it’s dealing with debts, investing, or budgeting money smartly, this book has got it all, making it a must-read for financial world newbies!

9. The Simple Path to Wealth by JL Collins

The Simple Path to Wealth by JL Collins

For an invaluable and step-by-step guide to controlling your finances and budget, The Simple Path to Wealth written by JL Collins is the answer! This book is a clear and fluff-free guide to help you gain control of your finances, helping you attain financial independence and security. 

The humorous tone of the book paired with highly applicable plans make it perfect for beginners, helping them implement it in easier ways. The book talks about how saving a higher percentage of your income, budgeting your paycheck smartly, and avoiding taking debt can lead you to greater financial security in the long-run. 

10. Your Money or Your Life by Vicki Robin and Joe Dominguez

Your Money or Your Life by Vicki Robin and Joe Dominguez

For a classic read on how to build wealth effectively, go with Your Money or Your Life written by Vicki Robin and Joe Dominguez. For a more meaningful connection with money, this book offers a deeper perspective, asking readers to examine how they trade their time, effort, and energy for their income. 

This book offers a 9-step plan to help you track spending, increase savings, reduce expenses, and eventually achieve financial independence and security. The authors also share the experiences, stories, and examples of many successful people, offering a motivational aspect to readers as well. 

Conclusion

Reading finance books as a beginner is one of the smartest decisions you can make while initiating your journey towards financial independence and long-term success. The books shared in this article offer a simple and straightforward approach to money-making, helping you digest complex financial concepts and offering practical tools so you can start right away! Whether it’s an author comparing his two dads in terms of money-making or deeply understanding the role of emotional aspects in financial decision-making, each book offers a unique perspective for people beginning their financial journey. The best part? You don’t need a finance degree to grasp the concepts, just willingness to learn. So pick one, start reading and take control of your financial life!

How To Save Money Biweekly

June 21, 2025 By Ana Rose

Saving money can be difficult, especially when you’re dealing with bills, daily expenses, and unexpected costs. But what if there was a way for you to save up without feeling the pinch? Biweekly money saving is a practical and stress-free method that can potentially grow your savings over time without having to overhaul your entire budget. This article will share some easy tips with you, guiding you on how to save money biweekly, helping you reach your financial goals without having it feel like a drag.

What is saving money biweekly?

Biweekly money saving is setting aside a portion of your income every two weeks, typically in line with your paycheck schedule. Instead of saving monthly, setting aside a small amount every two weeks can help you save smaller amounts more often, that is 26 times a year. 

This method encourages consistent and manageable saving habits that can help you save for an emergency situation, future financial goals, or planning for large expenses without having to utilize your entire budget.

Set a savings goal

Woman holding pink piggy bank pointing to biweekly savings goal chart with thermometer tracker showing $2,500 and $5,000 milestones

Before you get to saving, it is important to have a clear purpose and strategy in mind. Ask yourself questions like

  • What am I saving for?
  • When do I want to reach this goal?
  • How much do I need?

Whether it’s $1,000 for an emergency fund, $2,000 to help your kid get into college or $5,000 for a nice and fun family vacation, it’s better to have a plan in mind to give your savings a meaning and help you stay motivated and consistent in the process!

Tip: Break the goal into smaller, biweekly chunks. For example, if you want to save around $5000 at the end of the year, you need to save almost $193 every two weeks. 

Use the 50/30/20 rule

A simple budgeting framework can be your go-to when thinking of effective plans or strategies to save money biweekly. The 50/30/20 rule is a similar and simple budgeting technique to help you allocate your take-home pay in a helpful manner. 

According to this rule, 50% of your pay goes to your needs. For example paying rent, utilities, groceries, and insurance would take up 50% of your income. 30% of your pay goes to your wants. This includes dining out with family and friends, subscriptions, entertainment, and other fun activities. Lastly, 20% of your pay would be used up for saving for an emergency fund, debt repayment, or any other future financial goals. 

Let’s say your biweekly paycheck is $2,000, the allocation of the income according to the 50/30/20 rule would include $1000 spent on needs, $600 on wants, and $400 on savings.

The 52-week saving challenge 

Woman placing gold coin into pink piggy bank next to table showing 52-week challenge with weekly amounts from $1 to $52

For a simple yet powerful strategy to save money biweekly more effectively, 52-week saving challenge is your answer! This method involves building up the savings gradually over the course of a year. 

It works by having you save a small amount each week, starting with $1 in week one, $2 in week 2, $3 in week 3 and so on until you reach $52 in week 52. By the end of 52 weeks, you’ll have saved a total of $1,378, without having to put a lot of effort and making any drastic changes to your lifestyle. 

Whether you’re saving for an emergency fund, a getaway holiday, or any future financial goal, the 52-week challenge turns savings into a much more fun and manageable habit. Especially when paired with a physical or digital tracker to stay in touch with the progress, this challenge can help you stay motivated and accountable when it comes to saving effectively. 

Pay yourself first

One of the most powerful tools when it comes to saving money is paying yourself first, which simply put, means saving money and setting some aside before you get to spend it.
A helpful way to carry out this practical method is to set up an automatic transfer to your savings account on the pay day. This way, saving becomes effortless and more manageable. This useful method also makes you less tempted to spend what you meant to save, making it one of the top strategies to save money biweekly. 

Use a biweekly budget plan

Woman standing beside pie chart showing 50% needs, 30% wants, 20% savings with $2,000 biweekly paycheck breakdown example

Budgeting biweekly requires a different approach than budgeting monthly. This approach requires a bit of adjustment as big expenses such car payments or rents are due once a month, not every two weeks. To make this method work, you need to set aside half of those monthly bills from each paycheck. 

At the same time, plan your everyday spending like gas, groceries, and fun in such a way that they match your pay schedule. 

CategoryBiweekly Amount
Rent and other utilities$700
Groceries$200
Gas and Transport $100
Savings$300
Fun and Dining$150
Emergency Situations$50

This method helps you spend your money like each dollar has a purpose and a job to complete. 

Cut non-essential spendings

To speed up the saving process, another helpful way is to cut non-essential spendings. Look for areas where you can cut off money both permanently and temporarily. This method can help you save up money more effectively and quickly, making the process a bit easier. 

Some non-essential spendings may include cancelling unused and unnecessary subscriptions, cooking more meals at home and avoiding takeouts and dining out, shopping with a list to avoid impulse purchasing, and switching to generic brands.

Even small changes, like cutting off coffee purchase for $5 daily can help you save around $130 biweekly or over $3,300 a year!

Try the envelope or jar method

For a hands-on budgeting technique, try the envelope or jar method which includes dividing your expenses into categories and using practical tools like envelopes or jars for holding the defined amount. Once the money runs out in the envelope or jar for a specific category, you stop spending on it. This practical method creates natural spending limits and helps create discipline for future financial saving goals.
If you’re more into digital tools, apps like Goodbudget can make saving money easier. These apps help you track expenses, monitor your budget, and help you stay organized and consistent with your biweekly savings plan. 

Save extra paychecks

Since you get 26 paychecks per year, two months will give you an extra paycheck, as compared to someone saving money monthly. 

To save money more efficiently, you can use these bonus pay periods to increase saving contributions, pay off high interest debts, build an emergency cushion, or treat yourself responsibly. 

For example, if your usual biweekly pay is $1,500 and March gives your three paychecks, you could save $1,500 extra that month!

The key is to plan ahead for these extra paychecks as they can become powerful tools for you to accelerate the saving process, reduce stress, and achieve greater financial security in the future. 

Track your progress

One of the most effective ways to stay consistent with your biweekly savings plan is to monitor the progress regularly. Tracking the progress not only keeps you in touch but also helps you stay motivated by showing you how far you’ve come, even if the process seems small at first. 

Some practical ways to track your savings can include using a simple spreadsheet, whether Excel or Google sheets, using budgeting apps like YNAB or Rocket Money, and creating a visual saving tracker such as a printable chart with progress bars and goal meters. 

By tracking your progress regularly, you can potentially be more aware of your habits, and can adjust them accordingly to help make the savings plan work better. 

Split the paycheck

When your paycheck arrives, it’s tempting to keep the whole amount in one account and spend it the way you like. But doing so can potentially blur the line between money for necessities and money for entertainment. One effective way to avoid this is to automatically split the paycheck into multiple accounts. 

You can set three separate bank accounts or sub-accounts. One can be the bills account that is for fixed monthly expenses like rents, utilities, insurance, or phone bills. One can be a fun spending account that covers flexible expenses like groceries, gas, takeouts, or shopping. The last one can be the savings account that can help you save up for future expenses or goals that you desire to fulfill. 

Conclusion

Saving money biweekly can be a game-changer for greater financial security and stability in the future, especially when your budgeting aligns with your pay schedule. By using effective strategies like the 50/30/20 rule, the 52-week saving challenge, the paying yourself first strategy, and tracking the progress regularly, you can create an effective habit that fits naturally into your lifestyle. With a clear path and purpose, saving every two weeks becomes less of a chore and more a confident step towards a future with financial security!

How Financial Services Use Transactional Emails to Combat Cyber Threats

June 13, 2025 By Kevin | Just Start Investing

In today’s digital-first world, the financial sector is constantly under the microscope when it comes to security. With cyberattacks growing in volume and sophistication, protecting customer data and ensuring secure communication has never been more critical. One of the silent warriors in this fight? Transactional emails.

[Read more…] about How Financial Services Use Transactional Emails to Combat Cyber Threats

Stress, Deadlines, and Vices: Inside the Finance Grind

May 20, 2025 By Kevin | Just Start Investing

There’s a lot people don’t see when they think about careers in finance. From the outside, it can look like a fast-paced, high-powered world with big salaries and fancy job titles. But if you talk to people on the inside—especially those who’ve been in it for a while—you’ll hear a different story. Behind those spreadsheets and earnings calls, there’s another side of the job that doesn’t make it into the recruitment ads. The long hours, the constant pressure, the intense competition—it wears people down. And in that kind of pressure cooker, certain habits can start to take root. Some of them aren’t just unhealthy—they’re addictive.

[Read more…] about Stress, Deadlines, and Vices: Inside the Finance Grind
  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 37
  • Go to page 38
  • Go to page 39
  • Go to page 40
  • Go to page 41
  • Interim pages omitted …
  • Go to page 73
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers