• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

General Personal Finance Blog

Most Effective Financial Literacy Projects For Kids

October 11, 2025 By Ana Rose

Money is a part of everyday life, yet many children grow up without learning their way around money. While schools cover topics like maths and figures, they rarely teach kids about real-world money scenarios, and by the time they become adults, they already feel overwhelmed by the concepts of budgeting, saving , or paying off debts. This is exactly why it’s important to teach your kids about financial literacy by making money lessons practical, fun, and hands-on. Instead of telling your kids about money, a better approach would be to let them experience it on their own, allowing them to take on money projects and make money concepts real and easier to understand. This article will help you explore some of the most effective financial literacy projects for kids that not only build financial knowledge but also shape habits that can stay with them for life. 
Most Effective Financial Literacy Projects For Kids Graphic

1. Create a Savings Jar Project

A cheerful child placing coins into a transparent savings jar decorated with stickers on a pastel pink background with soft glowing highlights.

For an easy and effective way to introduce kids to money management, create a savings jar project. Give them a transparent jar or piggy bank so they can see their savings grow over time, making the process more exciting and easier to stay consistent with. 

Each time they put in a coin or a note, explain to them that these small amounts can build up into something big and meaningful over time, making it worth every sacrifice and effort. To make the saving process more meaningful, you can also consider associating the project with a mini goal like buying a new toy or a video game. 

2. Needs vs. Wants Sorting Game

For one of the most simple yet highly effective approaches to help your kids understand money management better, consider the needs vs. wants sorting game. This project is all about helping your kids understand what expense is a need and what falls under the wants category. Tell them that needs are essentials that always come first, whereas wants are those extras that are just nice to have. 

Once you let them know the difference between the two, start collecting pictures of items from magazines or get printouts of items like food, toys, school supplies, clothes, or gadgets, and ask them which items are needs and which are wants. This project can help them understand the importance of always prioritizing needs over wants, building healthy habits of spending wisely in the long run. 

3. Allowance Budgeting Challenge

Instead of giving your kids money without any direction or purpose, try turning their allowance into more of a budgeting project. Teach them to divide their money into three parts, saving, spending , and sharing. 

For instance, if you give them $10, they can put $5 in savings, $3 for spending, and $2 for sharing or giving. While this may seem simple, this project can help your kids think strategically, making the most of their money. 

4. Family Grocery Project
A parent and child smiling while comparing grocery prices and checking a shopping list on a pastel pink background with subtle glowing highlights.

For one of the most practical ways to teach your kids about budgeting, consider the family grocery project which involves taking your kid to grocery shopping with you, giving them a small amount of money, a mini shopping list, and letting them plan how to buy the items while still figuring out ways to stay within the budget. 

Ask them to compare prices, cost, and value, and help them learn about spending wisely and being more mindful with the hard-earned money. 

5. Goal-Setting Vision Board

A vision board can remind your kids of their targets and goals, making the process feel more exciting and motivating. You can help them cut out pictures or draw items they want to save for, whether it’s a new toy, a new video game, or a fun trip. 

Try placing the vision board in their room so they’re reminded of their goals and that they’re moving closer to achieving it with every passing day. This project helps kids understand the importance of staying consistent with your goals and being patient while working towards them. 

6. Mini Lemonade Stand or Bake Sale

Let your kids get hands-on experience with selling or dealing with customers by helping them set up a small business like lemonade stand or bake sale. You can guide them through the process such as helping them buy ingredients, set prices, or keep track of sales. 

Not only will your kids enjoy the excitement of making their own money, they will also learn that earning requires effort, patience, and responsibility, ultimately teaching them beneficial lessons at an early age. 

7. DIY Bank at Home

Turn your home into a “bank” where your kids can deposit their money into envelopes or boxes that act like accounts. You can set up savings, spending, and giving sections and even play the role of the “banker” to keep track of balances. 

This project can make kids more familiar with how real banks work but in a fun, simple way. Over time, your kids can understand essential concepts like deposits, withdrawals, and balance tracking without feeling overwhelmed, making this project idea a considerable option. 

8. Charity Box Project

Teaching kids about generosity is just as important as teaching them about saving. Create a charity box at home where they can drop a small portion of their allowance or gift money. Once the box has enough, let them choose a cause, like donating to an animal shelter, helping a neighbor, or giving to a school fundraiser. 

This project shows children that money isn’t just for personal use, but also a tool to help others and bring positive change in the community.

9. Board Games and Money Activities

Games are a fun and stress-free way for kids to learn about financial concepts. Games like Monopoly, The Game of Life, or even custom DIY board games can teach them about saving, investing, and making choices with money. You can also create simple activities at home, such as role-playing a store where kids buy and sell items with play money. 

These interactive games make financial lessons less formal and more engaging, helping kids understand money naturally through play.

10. Small Entrepreneur Project

Children are naturally creative and curious, and giving them the chance to run a very small business project can teach them lessons they will never forget, because it helps them see that money does not just appear from parents’ wallets, it comes from effort, skill, and time. You can guide your child in starting something simple such as selling homemade lemonade, painting cards, or baking cupcakes, and then walk them through every part of the process, from buying supplies to setting prices and finally counting what they’ve earned. 

This project not only helps kids understand profit and costs in a fun, hands-on way, but also builds their confidence and independence as they experience the joy of creating something themselves and being rewarded for their work.

11. Advertising Awareness Activity

In today’s world, children are surrounded by advertisements everywhere they look, such as on TV, social media, shops, and even games, and many times these ads are designed to make them want things they do not really need. 

A simple and effective project is to watch commercials or look at online ads together, then talk about the tricks companies use, like bright colors, catchy music, or fun characters, to convince people to buy. By having these conversations, children start noticing how advertising works, and instead of getting carried away by excitement, they slowly learn to pause, question whether they really need the product, and make choices that come from their own judgment.

12. Family Budgeting Discussion

Children often think money is endless because they don’t see all the behind-the-scenes decisions that parents make, so involving them in simple family budgeting discussions can be one of the most powerful ways to show them how money truly works in daily life. 

You don’t have to overwhelm them with numbers, but you can sit together and explain in simple terms how a portion of money is kept aside for food, another part for bills, and then a small portion for fun or savings, and you can even let them help with something small like planning a grocery list within a budget or choosing an activity that fits the family’s spending plan.

This kind of project not only makes children feel trusted and included in family matters, but it also builds a very practical understanding that money has limits, choices have to be made, and being thoughtful with spending is what allows the family to enjoy life without unnecessary stress.

Conclusion

Teaching kids financial literacy doesn’t have to be complicated or filled with big, scary words, it can be as simple as turning everyday moments into little lessons and letting them practice with small projects that feel fun and meaningful. Whether it’s dropping coins into a savings jar, running a lemonade stand, playing a board game, or joining a family budgeting talk, each experience gives them tools that will stay with them for life. The goal isn’t to raise financial experts overnight, but to slowly build habits so that as they grow older, they will carry these lessons with them.
How To Teach Financial Literacy To Kids

October 10, 2025 By Ana Rose

Money is something you have to deal with your entire life, yet many children grow up without learning how to manage it. Schools often skip teaching the real-world money skills and by the time kids become adults, they face the stress of budgeting, saving, or paying off debt, leaving them overwhelmed and frustrated. Teaching the kids about financial literacy is not about overwhelming them with complicated or complex financial terms, it’s about showing them how money works in ways they can understand. This article will help you explore how to teach financial literacy to kids, starting with small lessons, everyday examples, fun activities, and building habits that will serve them for life.

How To Teach Financial Literacy To Kids Graphic

Start with the Basics of Money

The first step in teaching kids financial literacy is helping them understand the basics of money without overcomplicating it for them. Show them what it is, like coins, notes, or even digital transactions, and how it works. Explain it to them that people work, and in return, they get paid and then they use that money to buy the things they need. 

You can use simple and understandable examples, like buying candy with money you make, to make it relatable for them. 

Teach the Difference Between Needs and Wants

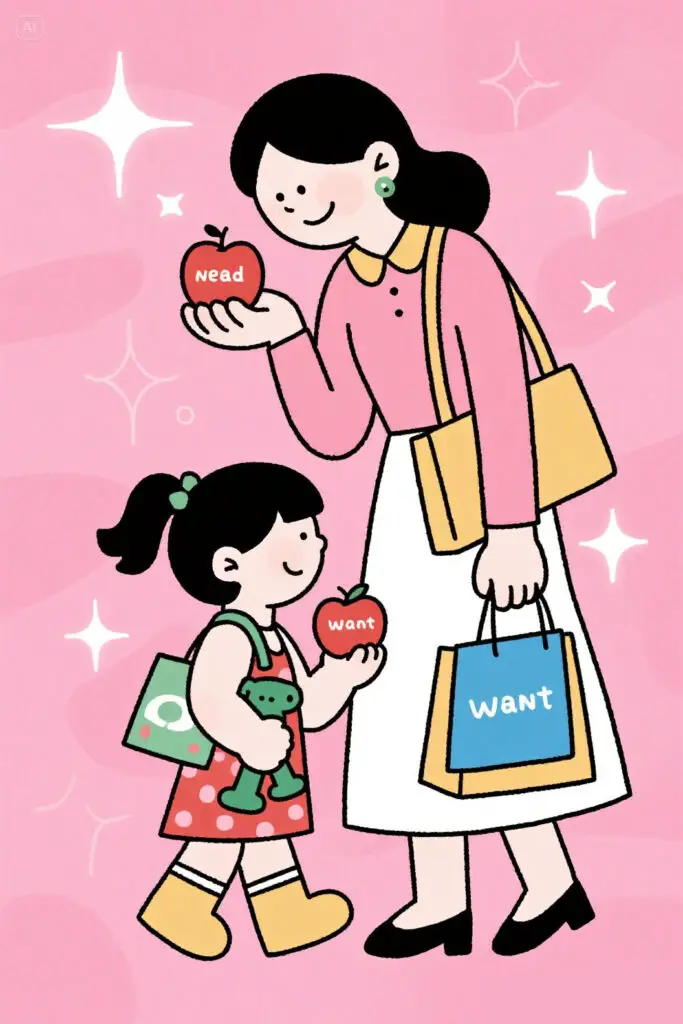
Illustration of a parent and child shopping together. The child holds two items: an apple (need) and a toy (want). The parent gently explains the difference while smiling. Pastel pink background with glowing highlights, simple and playful design.

One of the most important lessons when it comes to teaching kids financial literacy is teaching them the difference between needs and wants. Needs are essentials like food, school supplies, or clothes, whereas wants are those nice-to-have items like toys, video games, or fancy snacks. 

You can make this step fun for the kids by taking them shopping and asking them to sort items into “needs”and “wants”. This exercise can help them understand that while wants are fun, needs always come first. 

Use Real-Life Examples in Daily Life

Children learn the best when they connect lessons to real-life examples. Let them see you pay bills, buy groceries, or compare two brands based on price. You can also involve them in small decisions such as choosing between two cereals, and then explain why one might be a better option than the other based on cost, quality, or value, helping them understand that every purchase involves thinking carefully rather than picking whatever looks good. 

Give Kids an Allowance to Practice With

An allowance is one of the simplest ways to teach kids hands-on money management. Whether you give it weekly or monthly, it gives them real money to practice saving, spending, and budgeting. 

Allowing them the freedom to make small mistakes, such as buying something they regret teaches valuable lessons. You can also associate allowance with tasks or chores, so children learn that earning comes with effort.

Teach the Habit of Saving Early

Saving is one of those important financial habits that kids should learn as early as possible. Give them a clear jar or piggy bank so they can physically see their money grow, which makes the process more exciting and easier to follow. 

You can also encourage them to save a part of whatever money comes their way, whether it’s from pocket money, a gift, or something they’ve earned, because even the smallest savings can grow into something meaningful, and when they’re older, they’ll be glad they started early.

Introduce Goal Setting for Their Money

Illustration of a child placing coins into three clear jars labeled “Save,” “Spend,” and “Goal.” The “Goal” jar has a picture of a toy taped to it. Pastel pink background with glowing highlights, cheerful and motivational vibe.

Teaching kids about setting goals helps them understand the purpose of saving and spending with a more mindful and intentional approach. Encourage them to set small and achievable goals like saving for a toy, a book, or even a special outing. 

Break the goal into smaller steps and show them that each time they put money aside with consistency, it brings them closer to the target.

Encourage Smart Spending Choices

Kids often get excited about spending money as soon as they have it, so this is the perfect opportunity to guide them toward making thoughtful choices. Teach them to compare prices, check for quality, and ask themselves whether they really need the item. For example, when they want a toy, you can show them how the same item might cost less in another store or online. This simple habit will help them understand that spending isn’t just about buying something fast, but about getting the best value for their money.

Involve Them in Family Budgeting

Children can learn a lot when they see how their family plans money in real life. You can share simple budgeting discussions with them such as setting aside money for groceries, bills, or even family outings. 

You don’t have to discuss complex numbers or figures with them, just explaining or letting them see how the family makes decisions regarding money and finances is enough. You can also let them help with small tasks like planning a grocery list within a budget, comparing prices, or choosing which items to prioritize, which not only makes them feel included but also gives them a practical understanding of how budgeting works in real life.

Teach About Sharing and Giving Back

Money lessons shouldn’t only be about saving and budgeting, they should also include sharing and donating money to causes your children care about. Encourage kids to set aside a small portion of their money to donate or help someone in need. 

This could be as simple as contributing to a school fundraiser or helping a friend in need. Teaching your children about generosity at an early age helps build empathy and helps them understand that money is also a tool for making a positive difference in other people’s lives. 

Open a Savings Account and Explain Banking

Once kids are a little older, introducing them to banking is a great step forward. Take them to open a savings account and explain how banks keep money safe, how deposits and withdrawals work, and even the concept of earning interest. By involving them in small transactions at the bank, they start to feel confident about handling money in the real world.

Use Games and Activities to Make Learning Fun

Kids learn best when the lessons don’t feel like lessons at all, and that’s why turning money concepts into games can be so powerful. You can try playing board games like Monopoly or The Game of Life to introduce ideas like saving, investing, and making financial decisions. Another helpful strategy would be to create simple at-home activities such as a pretend store where they “buy” and “sell” with play money. 

Teach the Value of Work and Earning

One of the most valuable money lessons for kids is showing them that money doesn’t just appear, it’s earned through effort. Encourage them to do small chores around the house or take on age-appropriate tasks, and connect their efforts with a small reward or allowance.

This not only teaches them responsibility but also helps them appreciate the value of hard work and understand that money has meaning when it is earned.

Explain Debt in Simple Words

As kids grow older, it’s important to gently introduce them to the concept of debt, because one day they’ll face things like credit cards or loans. You can keep it simple by explaining that borrowing money means you have to pay it back, often with extra money added on top, called interest. 

Teach Critical Thinking About Advertising

Children are surrounded by ads everywhere they look, such as on TV, online, or even at the store, and these ads are designed to make them want things instantly. Take the time to explain to your kids that advertisements are not always about what they need but about convincing them to buy. You can make this lesson interactive by watching commercials together and asking questions like, “Do we really need this?” or “What is the ad trying to make us feel?” 

Celebrate Their Progress and Good Habits 

Learning about money can sometimes feel overwhelming, so it’s important to celebrate the small wins along the way. Whether your child has saved up for their first toy, donated to a cause, or stuck to a small budget, recognize their effort and cheer them on. Celebrations don’t have to be expensive, it could be as simple as having a family movie night, cooking their favorite meal, or giving them words of praise that show how proud you are.

Conclusion

Teaching kids about money is not about turning them into financial experts overnight, but about slowly building habits and giving them the confidence to make smart choices as they grow. By starting with small lessons like understanding the basics of money, saving in a piggy bank, or helping with the family budget, you are giving them skills that will stay with them for life. The goal is to make money a topic that feels natural, approachable, and even fun, instead of something scary or confusing. When children learn early that money is a tool that can help them achieve their goals, share with others, and create stability, they are more likely to grow into adults who feel confident and capable with their finances. 

The Top 24 Financial Life Hacks You Need To Know

October 9, 2025 By Ana Rose

Money isn’t everything, but the way you handle it can shape almost every aspect of your life. From paying bills to building your future dream life, the habits and little hacks you use for managing money can make the difference between always being stressed out over finances and finally being in control rather than letting money control you. Whether you are a student, an entrepreneur, or someone simply looking for little money hacks to manage their financial life more effectively, using tips and tricks can transform your financial health in ways you may not realize. This article will explore 24 smart financial hacks, helping you save more and spend smartly, ultimately growing wealth without having to turn your life upside down. 

The Top 24 Financial Life Hacks You Need To Know Graphic

1. Automate Your Savings

To avoid the temptation to use your hard-earned money, automating transfers to your savings account is one of the best options. This way, you don’t have to remember to transfer an amount whenever the saving is due, moreover, this hack also takes away the stress of manually moving an amount to a safe space, allowing your money to grow in silence and peace without any extra effort. 

2. Use the 24-Hour Rule

Impulsive buying is one of the biggest obstacles to managing money in a healthy manner. An effective way to deal with impulse shopping is by waiting 24 hours before purchasing, giving yourself the time to think over your choices and asking yourself whether the purchase is worth your money. In most cases, you’ll come to realize that you don’t actually need the item. 

3. Track Every Dollar

Keeping track of your spendings can show you where the money is actually going, helping you manage it accordingly. You can use apps to track your spending habits, create a spreadsheet, or use something as simple as a notebook. 

4. Embrace the 50/30/20 Rule

To manage your money more effectively, a good strategy would be to use a helpful budgeting method. For a classic option, consider the 50/30/20 rule which involves assigning 50% of your income to essential expenses such as rent, transportation, or groceries, 30% of the paycheck goes to non-essential expenses such as takeouts, shopping, or subscription, and lastly, 20% is used on savings or paying off debt, if there is any. 

5. Cancel Unused Subscriptions

Smartphone screen with multiple app icons and a cancel button, symbolizing removing unused subscriptions, on a pastel pink background with glowing highlights.

Many people pay monthly for apps or memberships they don’t even use. Check your bank statement for hidden charges, figure out subscriptions that silently eat away a chunk of your income every month, cancel them, and direct the same money towards something more meaningful like a savings fund or safety net. 

6. Cook at Home More Often

Takeouts and restaurant bills cost much more than we realize. Cooking at home not only saves money but also gives you healthier meals. A better strategy is to plan your meals ahead of time and make the necessary preparations, so that whenever you feel like eating, you already have a meal ready or prepped. This way, you eat healthy food at home while also avoiding food waste.

7. Negotiate Bills

Phone, internet, or even insurance companies offer lower rates if you simply ask them. Instead of assuming that the prices are fixed, try giving the companies a polite call, you may end up saving thousands of dollars a year!

8. Pay Yourself First

Each time your paycheck hits your bank account, a simple yet highly effective financial hack is to pay yourself. Before you spend your money on rent, groceries, utilities, or other expenses, make it your habit to transfer an amount to your savings account first. If you wait until the month ends, you’ll rarely have anything left, which is exactly why his habit is a must-try, ensuring that your financial goals always come first.

9. Build an Emergency Fund

Life throws unexpected challenges when you least expect them. Whether it’s a sudden medical bill, job loss, or car repair, having a safety net in place can help you deal with these circumstances with confidence. 

Try having 3–6 months of expenses saved in a separate savings account to protect yourself from falling into debt during tough times.

10. Round Up Purchases

An easy yet effective saving trick is rounding up your purchases to the nearest dollar and saving the difference. For example, if you spend $8.60, round it up to $9 and set aside the extra $0.40. 

Many apps can do this automatically, and over time, those small amounts add up into significant savings without you even noticing.

11. Shop with a List

Shopping without a plan often leads to overspending on items you don’t really need. Having a list keeps you focused and prevents impulse purchases. 

This simple habit saves money, reduces waste, and ensures you only buy what you truly need.

12. Buy in Bulk (But Smartly)

Buying essentials in bulk such as items like rice, pasta, cleaning products, or toiletries are perfect bulk purchases that are also cheaper in the long run. 

Just be careful to only buy what you know you’ll use before it expires, otherwise you’re not saving, you’re wasting.

13. Use Cashback and Reward

Cashback offers, rewards points, and loyalty programs can stretch your money further. By using cards or apps that give you rewards on everyday purchases, you get back a portion of what you spend. However, always remember to use these perks wisely, not as an excuse to overspend.

14. Plan Your Meals Around Discounts

Groceries can eat up a large part of your budget. A smart strategy is to plan meals based on weekly store discounts or seasonal sales. This not only lowers your expenses but also pushes you to be more creative with meals while saving money.

15. DIY Where Possible

Hiring professionals for every little task can be costly. Learning to do small repairs, cooking your own meals, or even brewing your own coffee can cut expenses significantly. DIY doesn’t mean doing everything yourself, but for smaller tasks, it’s a big money-saver.

16. Set Sinking Funds

Certain expenses like car maintenance, holiday gifts, or vacations don’t come monthly, but they always show up eventually. A sinking fund is where you save small amounts regularly for these expenses. When the time comes, you’ll already have the money set aside instead of scrambling or going into debt.

17. Invest Early

The sooner you start investing, the more your money benefits from compound growth. Even small investments made early can turn into large sums over time. 

18. Avoid Lifestyle Inflation

Illustration of two paths—one with luxury spending on cars and shopping bags, and the other showing savings and investments growing—on a pastel pink background with soft highlights.

It’s tempting to upgrade your lifestyle when your income increases, such as buying nicer cars, bigger homes, more luxuries, but if your spending rises with your income, you’ll never build wealth. Instead, keep your lifestyle steady and direct extra income toward savings or investments.

19. Unsubscribe From Temptation

Emails and social media ads are designed to push you into spending. By unsubscribing from shopping newsletters and unfollowing pages that constantly tempt you, you can reduce the urge to buy things you don’t need..

20. Use Public Transport

Owning a car can be expensive with fuel, insurance, parking, and maintenance costs. Whenever possible, use public transportation or carpooling to save money. It’s not just budget-friendly but also eco-friendly, helping you cut costs and reduce stress.

21. Buy Secondhand

Many items like furniture, clothes, and even electronics are available in great condition at a fraction of the cost. Thrift stores, online marketplaces, or community sales can help you save money while being sustainable.

22. Learn Basic Financial Literacy

The more you understand money, the better you can manage it. Reading finance books, listening to podcasts, or following reliable finance blogs can build your knowledge. Even basic financial literacy helps you make smarter choices and avoid costly mistakes.

23. Set Clear Money Goals

Money without direction often disappears quickly which is why it is important to set clear goals like buying a home, paying off debt, or saving for retirement. Having a target keeps you motivated and gives you a sense of purpose for every dollar you save.

24. Celebrate Small Wins 

Whenever you reach a financial milestone, it is important to celebrate your success. Whether you’ve paid off a credit card debt, saved your first $500, or stuck to a budget for a month, treat yourself in a budget-friendly way. 

These small celebrations don‘t have to cost you a lot, they can be as simple as watching your comfort movie, having your favorite meal, or going for a fun day out with friends. 

Conclusion

Money is something we all deal with every single day, and while it can sometimes feel overwhelming, the truth is that even small changes in the way we handle it can completely shift our financial lives. These 24 hacks are not about turning your life upside down or making you feel restricted, but about giving you little tools and habits that make things lighter and more manageable.. The best part is that none of these hacks requires perfection, what matters is consistency, patience, and the belief that progress, no matter how small, is worth celebrating. By making money work for you instead of against you, you not only grow your wealth but also create peace of mind and freedom in your everyday life.

Tony Robbins 7 Steps To Financial Freedom

October 6, 2025 By Ana Rose

Financial freedom is a term that we hear quite often, yet most people are not really sure what it actually means or how they can ever get there. For some people, financial freedom simply means being able to pay their bills on time without the constant stress of running out of money, for others it is about being able to retire early and spend their days doing the things they love without worrying about a paycheck. In his well-known book, “Money: Master the Game”, Tony Robbins takes this idea and makes it real by offering not just vague dreams of independence but a clear and practical roadmap that anyone can follow, no matter whether they are just starting their journey or already on the path to building wealth. This article will help you explore the 7 steps to financial freedom by Tony Robbins, helping you become financially free and stable in the long run. 

Tony Robbins 7 Steps To Financial Freedom Graphic

Step 1: Make the Most Important Financial Decision of Your Life

The very first step that Tony Robbins talks about is not about learning complicated investment formulas or chasing big opportunities, it is simply about making a personal choice that changes the direction of your life forever, and that choice is deciding to become an investor instead of being only a spender. Most of us are used to earning money and spending it almost as quickly as it comes in, and while that might cover today’s needs, it does nothing for tomorrow. 

Robbins explains that financial freedom begins when you decide that no matter what, you will always put aside a small part of what you earn and make it work for you instead of letting it slip away. Even if the amount feels small at first, the power lies in the habit, because once you commit to paying yourself first, your future self benefits from the money that grows quietly in the background. 

Step 2: Become the Insider and Know the Rules Before You Get in the Game

Illustration of a person reading a large open book filled with financial icons like coins, stocks, and tax symbols, with a magnifying glass highlighting the pages, on a pastel pink background with glowing highlights.

Once you have made the decision to invest, the next step is to learn how the money game actually works. Robbins says that the financial industry often takes advantage of people who do not educate themselves, charging hidden fees, offering confusing products, and giving advice that is not always in the client’s best interest. 

To protect yourself and grow with confidence, you need to take responsibility for learning the basics, for instance, how investments grow, what risks exist, how fees and taxes affect your returns, and how different financial tools work. You do not have to become an expert overnight, but by becoming an insider, you remove the fear and confusion that holds most people back. 

Step 3: What’s the Price of Your Dreams? Make the Game Winnable

A lot of people believe financial freedom is only for millionaires, but Robbins encourages us to stop thinking in overwhelming terms and instead, get clear on exactly what it would cost to live the life we truly want. He asks you to sit down and calculate how much money you really need each month or each year to cover your essentials, your comforts, and even your dreams. 

Many people are surprised when they do this exercise, because the number is usually smaller and more achievable than they first imagined. This is what he means by making the game winnable, because once you know your number, you can create a plan that feels realistic rather than chasing some endless and uncertain goal. With a clear target in front of you, every saving and investing step becomes more meaningful, because you can see how it moves you closer to the life you want. 

Step 4: Make the Most Important Investment Decision of Your Life

In this step, Robbins reminds us that the success of your investments does not depend on picking the perfect stock or trying to time the market, but on how you divide your money across different types of assets. This process is called asset allocation, and it is one of the biggest factors that determines whether your wealth grows steadily or gets lost to sudden risks. 

By spreading your money between things like stocks, bonds, real estate, and cash, you protect yourself from losing everything if one part of the market goes down, while still allowing your money to grow over time. Robbins explains that even the wealthiest investors in the world rely on this principle, because it balances growth with safety. Making this decision wisely is the difference between financial stress and financial confidence, because it ensures that your future is not left to chance but supported by a structure designed to last.

Step 5: Upside Without the Downside and Create a Lifetime Income Plan

Minimalist vector of a balanced scale with coins sprouting like a plant on one side and a shield symbolizing protection on the other, set against a pastel pink background with soft glowing highlights.

One of the biggest fears people carry is the thought of running out of money when they get older, and Robbins addresses this by showing how you can build a plan that gives you steady income for life while still allowing your wealth to grow. The idea is to combine investments that have potential for growth with strategies that also protect you from big losses, so you can enjoy the upside without being crushed by the downside. 

This might include using tools like annuities for guaranteed income, dividend-paying investments, or other options that make sure your basic needs will always be covered. When you know that no matter what happens in the economy you will still have money coming in, a huge weight is lifted off your shoulders, because you are no longer depending only on your job or on hope. This step is really about peace of mind, knowing that your future is secured allows you to enjoy the present without the constant fear of financial collapse.

Step 6: Invest Like the .001% — The Billionaire’s Playbook

In this step, Robbins takes us inside the minds of some of the world’s most successful investors, people who have built incredible wealth not by luck but by using strategies that anyone can learn from. He interviewed financial giants like Warren Buffett and Ray Dalio, and what he discovered is that their success is not about chasing trends or gambling on risky moves, but about patience, discipline, and intelligent planning. For example, Dalio’s approach focuses on building a portfolio that can withstand different economic conditions, while Buffett’s philosophy is about long-term value and ignoring short-term noise. 

Robbins explains that while we may not have billions to invest, we can still follow the same principles on a smaller scale such as balancing our portfolios wisely, focusing on long-term growth, and avoiding emotional decisions that sabotage our progress. Learning from the very best gives us a shortcut to avoid mistakes and build wealth with confidence, because their playbook is already tested and proven.

Step 7: Just Do It, Enjoy It, and Share It 

The final step is about taking action and remembering why you started this journey in the first place. All the knowledge and strategies in the world mean nothing if you do not apply them, so Robbins encourages us to begin wherever we are, even if it feels small at first, because the real progress comes from starting and staying consistent. 

As your financial situation improves, it is also important to celebrate the small wins along the way instead of waiting until the end, because enjoying the journey makes the process more meaningful. Most importantly, Robbins highlights that true financial freedom is not just about having enough for yourself but also about sharing your blessings with others. 

Whether it is helping your family, supporting your community, or contributing to causes you care about, giving back creates a sense of purpose that money alone cannot provide. In the end, wealth is not just about security or luxury, it is about freedom, joy, and the ability to make a difference.

Conclusion

When you look at Tony Robbins’ seven steps to financial freedom as a whole, you realize that this journey is not about chasing some impossible dream of endless wealth, it is about creating a life where money stops being your biggest worry and instead becomes a tool that gives you choices and peace of mind. What makes these steps so powerful is that they are not just about numbers and investments but about shifting your mindset, because financial freedom is not only about how much you have in the bank but also about how you feel when you think about money. The truth is that freedom comes when you no longer live in fear of running out, when you know you have created a plan that will take care of you and your loved ones, and when you are in a position to share your success with others. 

10 Steps To Financial Freedom

October 3, 2025 By Ana Rose

Financial freedom is one of those goals everyone dreams to achieve but very few of us manage to get there. For everyone, the definition of financial freedom is different, some see it as the ability to live life on your own terms while some may see it as being debt-free, having money in savings, or simply not stressing over bills every month. In today’s age where inflation is rising, debts and unexpected financial emergencies are a part of life, financial freedom can feel like a distant dream. But the truth is, financial freedom isn’t reserved for the wealthy only, it can be built step by step through conscious efforts while maintaining discipline and confidence. This article will help you explore a step by step guide towards financial freedom, helping you become financially secure and stable in the long run. 

10 Steps To Financial Freedom Graphic

Step 1: Define What Financial Freedom Means for You

For the first step towards financial freedom, you need to think about what financial freedom truly means to you. If you don’t know what you’re aiming for, no amount of saving, budgeting, or investing will feel satisfying because you won’t have a clear finish line. 

You can take some time and reflect on your values and priorities. Whether it’s saving a specific amount, securing your children’s education, or reaching a level of income that allows you to live life on your own terms, having a clear goal can help make the process more personalized, ultimately helping you become more motivated and consistent to achieve your target. 

Step 2: Track Your Money

A woman writes expenses in a notebook on a pastel pink background, surrounded by floating receipts, coffee cups, and shopping bags. Soft glowing highlights symbolize awareness of spending habits.

Once you know what financial freedom looks like for you, the next step is to track your money. The key point of this step is to know your income and modifying your spending habits considering your hard earned money. Most people believe they know their spending habits, but the truth is, small purchases like daily coffees, takeout meals, subscriptions, or impulse shopping add up faster than we realize and quietly drain our income.

You can track your money through budgeting apps, spreadsheets, or something as simple as a notebook. Record all sources of income and every expense, either big or small, for at least one month. When you review the results, you’re likely to find some spots where money slips away, offering you the opportunity to modify your spending habits and redirect that money towards your bigger goal. 

Step 3: Create a Realistic Budget

The next step is to create a realistic budget that feels empowering for your money, rather than a restriction or punishment. A good budget can help you balance your needs, wants, and long-term goals perfectly without making you feel deprived or holding back on things you enjoy. 

One popular method is the 50/30/20 rule where 50% of your income goes to the basic expenses which include rent, groceries, transportation, or utilities. 30% of the income is spent on non-essential expenses that include takeouts, shopping, subscriptions, or hobbies. Lastly, 20% of the income goes to savings and debts, if there is any. 

You can also consider the envelope method where every dollar is assigned a purpose to serve. In this budgeting method, categories are made, such as groceries, transportation, or food, and envelopes are labeled with each category’s name. A certain amount of cash is placed into each envelope at the start of the month, and once the money in a particular envelope is spent, you can’t add more or borrow from another category. This method forces you to stay disciplined, spend within limits, and become more mindful about where every dollar goes.

Step 4: Build an Emergency Fund

Life has its way of throwing curveballs when we least expect them, such as medical bills, job loss, or sudden car repairs can turn your financial world upside down if you’re not prepared. This is why building an emergency fund is one of the most important steps towards financial freedom, because it gives you a safety net instead of relying on loans or credit cards in times of financial crisis. 

You can save three to six months’ worth of essential living expenses, but if that feels overwhelming, start small by setting a goal of $500, then $1,000, and gradually build from there. Even a modest emergency fund can offer you peace of mind, because knowing that you have money set aside allows you to face challenges without panicking or stressing over the future. 

Step 5: Eliminate High-Interest Debt

Debt is one of the biggest obstacles standing between you and financial freedom, especially high-interest debt like credit cards, payday loans, or personal loans that seem to grow faster than you can pay them off. The first step to tackling debt is to list all your balances along with their interest rates, so you can see clearly where your money is going.

From there, you can choose between two proven strategies, the debt snowball method, where you focus on paying off the smallest balance first while making minimum payments on the others, which builds confidence and momentum along the way, or the debt avalanche method, where you pay off the highest-interest debt first, saving more money in the long run. 

Step 6: Increase Your Income Streams

Relying solely on one income in today’s economy is risky, because if that job disappears, so does your financial stability. That’s why it’s important to explore different ways to earn money on the side, no matter how small they may seem at first. You can think about your skills and hobbies, whether it’s writing, teaching, baking, or even creating digital content, use your skills to create a side hustle that brings in extra income. 

The purpose is not to overburden yourself but to make your financial life more secure and flexible. Even an additional $100 or $200 earned in a month can make a difference when directed toward savings, debt repayment, or investments. Having multiple streams of income gives you peace of mind and more choices in life, because you’re not tied down to one source of money or worried about what will happen if it suddenly stops.

Step 7: Save and Invest Consistently

A woman places coins into a flourishing money plant against a pastel pink background, with a savings jar and a stack of books beside her. Glowing highlights represent long-term financial growth.

Saving money is the foundation of financial security, but investing is what truly helps your wealth grow over time. Many people hesitate to invest because it feels complicated or risky, but the truth is, you don’t need to be an expert or start with a huge amount. Savings keep your money safe for short-term goals, but investments help your money work for you in the long run through the power of compounding. Even if you start with something small like $50 or $100 a month in a retirement fund, mutual fund, or index fund, it can grow into something much bigger over the years. The key is to keep adding to it, no matter how small the amount, and not pull it out for temporary wants. When you save and invest consistently, you create a sense of security and freedom, knowing your future is taken care of and you’re not just depending on your paycheck alone.

Step 8: Protect Yourself with Insurance

No matter how well you plan, life can bring unexpected challenges, and without proper protection, a single event can wipe out years of progress. This is where insurance becomes essential, it acts like a shield to protect you, your family, and your money. Health insurance, life insurance, and even property insurance may feel like an extra expense, but in reality, they save you from massive financial loss when something unexpected happens. 

By getting the right insurance for your situation, you’re not only protecting yourself but also giving your family the security they deserve. It’s not about expecting the worst to happen but being smart enough to prepare in case it does, so that your journey to financial freedom doesn’t get derailed.

Step 9: Keep Learning About Money

Money is not something you figure out once and never look at again, it’s a lifelong learning process. The financial world keeps changing, with new tools, new opportunities, and new risks, and the more you learn, the better choices you can make for yourself. 

You don’t need to become a finance expert, just making small efforts to read personal finance books, listen to podcasts, or follow reliable money experts can make a huge difference. When you keep learning, you also protect yourself from falling into scams, making poor investment decisions, or staying stuck in unhealthy financial habits. 

Step 10: Live Below Your Means & Stay Disciplined 

At the heart of financial freedom lies discipline, and one of the most important habits to develop is living below your means. This doesn’t mean you have to live a boring or joyless life, it simply means resisting the urge to spend more every time your income grows. Many people earn high salaries but are still stressed about money because their lifestyle expenses keep increasing with their paycheck. 

On the other hand, people with average incomes often build wealth because they are careful, thoughtful, and consistent with how they spend and save. Living below your means allows you to create a gap between what you earn and what you spend, and that gap is where savings, investments, and true financial security come from. 

Conclusion

Financial freedom may sound like a distant dream, but in reality, it is built step by step through conscious decisions, discipline, and patience. By defining what financial freedom means for you, tracking your money, budgeting wisely, saving, investing, and protecting yourself with the right tools, you gradually build a life where money is no longer a constant source of stress. Each small step adds up, and even if progress feels slow, remember that every dollar saved or invested is moving you closer to peace of mind and independence. The beauty of financial freedom is that it doesn’t require you to be rich, it just requires you to be intentional, thoughtful, and consistent with your choices. 

  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 24
  • Go to page 25
  • Go to page 26
  • Go to page 27
  • Go to page 28
  • Interim pages omitted …
  • Go to page 73
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers