• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

General Personal Finance Blog

How To Beat DCM Services?

February 28, 2024 By Kevin Keenan

Dealing with debt collectors can be a daunting experience, especially when it involves debts of deceased loved ones.

Learn about DCM Services, how they operate, and the type of debt they collect. It’s important to know your consumer rights when dealing with debt collectors like DCM Services.

Discover tips on how to handle DCM Services, including requesting validation of the debt, negotiating a settlement, and seeking legal help if necessary.

Key Takeaways:

  • Know your consumer rights when dealing with DCM Services to protect yourself from any potential violations.
  • Always request validation of the debt from DCM Services to ensure accuracy and legitimacy.
  • Consider negotiating a settlement or seeking legal help to beat DCM Services and resolve the debt.

What is DCM Services?
dcm services

DCM Services, based in Minneapolis, Minnesota, is a debt collection agency that specializes in collecting debts from deceased individuals on behalf of creditors or estates.

They offer a range of services to assist with debt collection, including skip tracing to locate individuals, negotiation with creditors to settle debts, and providing detailed account information to estate representatives.

DCM Services prides itself on its strict adherence to the Fair Debt Collection Practices Act, ensuring that all debt collection activities are conducted ethically and within legal guidelines.

When handling debts of deceased individuals, they work closely with estate representatives to verify debts and communicate effectively to resolve outstanding balances.

DCM Services interfaces with credit bureaus to update credit reports accurately, reflecting any settlements or payments made on behalf of the deceased individual.

Who is DCM Services?

DCM Services LLC, commonly known as DCM Services, is a reputable debt collection agency with a strong presence in the industry, accredited by the Better Business Bureau.

Established with a commitment to ethical debt collection practices, DCM Services has built a solid reputation for its professionalism and efficiency in resolving outstanding debts.

Through the years, the agency has demonstrated a consistent dedication to aiding individuals and businesses in managing their financial obligations.

Being affiliated with the Better Business Bureau signifies DCM Services’ adherence to high standards of integrity and customer service.

This accreditation is a testament to their commitment to fair debt collection practices and transparent communication with clients.

  • Debt collectors at DCM Services play a crucial role in contacting debtors and negotiating repayment plans on behalf of creditors. Their primary objective is to recover owed funds while maintaining respect and professionalism throughout the process.
  • In complex cases or legal disputes, DCM Services may involve attorneys to navigate legal frameworks and ensure compliance with regulations governing debt collection.

What Type of Debt Does DCM Services Collect?

DCM Services primarily focuses on collecting outstanding debts from deceased individuals, requiring proper documentation and estate verification to proceed with the collections process.

Specific types of debts that DCM Services handles include credit card balances, medical bills, personal loans, and mortgage payments. When dealing with deceased individuals’ debts, it is crucial to send debt validation letters to ensure the validity of the obligations. These letters serve as a formal request for proof of the debt’s existence and authenticity.

In the process of debt verification, estate documentation plays a vital role. This may involve obtaining a copy of the deceased person’s will, death certificate, and any relevant trust documents. Validating the estate ensures that the debts are legitimate and can be pursued for collection.

Verifying and collecting debts from deceased individuals requires a systematic approach. DCM Services conducts thorough investigations to confirm the debts, reviews estate documentation, contacts creditors, and works with legal representatives if necessary to resolve outstanding financial obligations.

How Does DCM Services Operate?

DCM Services operates by initiating debt collection procedures, which may involve sending validation letters, negotiating settlements, and in certain cases, pursuing legal actions such as lawsuits or wage garnishment.

Regarding handling consumer complaints, DCM Services maintains communication channels to address concerns and resolve issues promptly.

While the possibility of lawsuits or wage garnishment exists, the primary focus is on amicable resolution through negotiations.

Validation letters play a crucial role in this process by providing consumers with the opportunity to request proof of the debt’s validity. These letters serve as a means to verify and dispute the debt, facilitating a transparent and fair collection process.

  • In cases where negotiations are feasible, DCM Services offers various options for individuals to explore. These negotiations can include setting up payment plans, settling for reduced amounts, or even exploring debt consolidation solutions.
  • It is essential for individuals dealing with debt collection agencies, such as DCM Services, to understand their rights and responsibilities throughout the process.

Know Your Consumer Rights Before Dealing with DCM Services
know your consumer rights

Before engaging with DCM Services, it is crucial to understand your consumer rights, including protections related to your credit score, the collections process, the option of pay-for-delete agreements, and the importance of maintaining proper documentation.

When dealing with debt collectors like DCM Services, it’s important to remember that your credit score can be significantly impacted. Late or missed payments that end up in collections can lower your score, making it harder to access credit or loans in the future.

Consider negotiating a pay-for-delete agreement with DCM Services. This allows you to settle the debt in exchange for the collection account being removed from your credit report, which can help improve your credit score.

Monitoring your credit through services like Credit Karma or Credit Sesame can give you real-time updates on changes to your credit report, helping you track any negative impacts from debt collection activities.

Lastly, proper documentation is key. Keep records of all communications with DCM Services, including letters, emails, and phone calls. This documentation can serve as evidence of any violations of your consumer rights and can be invaluable in any disputes that may arise.

What Are Your Rights When Dealing with Debt Collectors?

When interacting with debt collectors like DCM Services, individuals are protected by the Fair Debt Collection Practices Act, which outlines specific consumer rights, including the right to dispute debts, seek legal counsel, and request arbitration in case of disputes.

Under the Fair Debt Collection Practices Act, consumers have the right to challenge the validity of a debt by formally disputing it with the collection agency. This enables them to seek validation and ensures that they are not unfairly coerced into paying debts they do not owe.

Individuals can enlist the assistance of attorneys who specialize in debt collection matters to guide and represent them throughout the process, providing valuable expertise and protection against any potential violations of their rights.

What Are the Rules for Debt Collection Practices?

Debt collectors like DCM Services must adhere to strict rules governed by the Fair Debt Collection Practices Act, requiring proper documentation, transparency in settlement agreements, and compliance with court procedures when necessary.

Under the Fair Debt Collection Practices Act, debt collectors, including DCM Services, are mandated to maintain accurate account records and provide written validation of debts upon request. This ensures that consumers have access to necessary information and can verify the legitimacy of the debt.

Collectors must clearly communicate settlement terms, including the total amount owed, any applicable fees, and payment options.

In cases where disputes arise, individuals have the right to challenge the debt through formal procedures. Debt collectors must cease collection activities until they provide verification of the debt.

If the matter escalates, consumers can seek legal recourse through the court system to address any violations of their rights under the Act.

How Can You Verify the Debt with DCM Services?

To verify a debt with DCM Services, individuals can request a validation letter, engage in negotiations regarding the debt, and cross-reference information with credit bureaus to ensure accuracy and legitimacy.

Upon receiving a validation letter from DCM Services, it is crucial to carefully review the details provided to confirm the debt’s validity. In the negotiation phase, be prepared to discuss payment options, potential settlements, or payment plans to reach a mutually agreeable resolution.

Leveraging credit bureau data can help in verifying the debt details and identifying any discrepancies that need to be addressed.

What Are Your Options for Dealing with DCM Services?

Individuals facing debts with DCM Services have options such as negotiation for settlement agreements, seeking assistance from credit repair companies, or exploring alternative solutions to resolve outstanding debts.

When dealing with debts owed to DCM Services, it’s essential to consider the various paths available to find a suitable resolution. One approach that many individuals find effective is to engage in direct negotiations with the debt collection agency.

By negotiating for settlement agreements, you may be able to reach a mutually agreeable payment plan that works within your financial capabilities. You could explore the option of enlisting the expertise of credit repair companies.

These professionals specialize in helping individuals navigate the complexities of debt management and can provide valuable support throughout the process.

How To Beat DCM Services?
how to beat DCM services

To overcome challenges posed by DCM Services, you can contact local attorney for legal assistance, file complaints when necessary, engage attorneys for debt settlement negotiations, or opt for arbitration to resolve disputes.

When dealing with debt collection agencies like DCM Services, it’s crucial to stay informed of your rights and understand the process involved.

If you encounter any unfair or aggressive practices from DCM Services, don’t hesitate to file complaints with the appropriate authorities to protect your consumer rights.

In more complex cases or if negotiations with DCM Services prove challenging, seeking assistance from experienced attorneys specializing in debt resolution can be beneficial.

These legal professionals can provide guidance, representation, and negotiation skills to help reach a favorable settlement that aligns with your financial situation.

Request Validation of the Debt
Request for Validation of the Debt

One effective way to address debts with DCM Services is to request validation of the debt through the submission of a formal debt validation letter, ensuring that the debt collectors provide accurate and verifiable information.

By sending a debt validation letter, individuals can challenge the validity of the debt and ensure that they are not being unfairly pursued for amounts that they may not owe.

This process allows consumers to request evidence that the debt is accurate, including details such as the original creditor, the amount owed, and any relevant dates.

Once the letter is received, DCM Services is legally obligated to provide the requested information within a reasonable timeframe.

Negotiate a Settlement
negotiation with UCB

Negotiating a settlement with DCM Services can be a viable option to reach a mutually agreeable resolution, potentially avoiding more severe actions like wage garnishment through cooperative discussions and compromises.

When engaging in negotiations with DCM Services, it is essential to understand that both parties have a common interest in resolving the debt amicably. This mutual objective can serve as a foundation for meaningful conversations that prioritize finding a balanced solution.

By proactively initiating discussions, individuals can take control of the situation, demonstrating a willingness to address the debt responsibly.

Establishing open communication channels fosters trust and paves the way for productive negotiations that benefit both the debtor and the creditor.

File a Dispute with Credit Bureaus
File a Dispute with Credit Bureaus

In cases of disputed debts with DCM Services, individuals can consider filing disputes with credit bureaus, leveraging credit monitoring services to rectify inaccuracies, and potentially avoiding legal actions such as lawsuits.

When facing challenged debts linked to DCM Services, taking proactive measures to dispute these accounts becomes crucial. By submitting disputes to the credit bureaus, people allow these agencies a chance to investigate and rectify any errors reported.

This process can be further streamlined by utilizing credit monitoring services that actively track and highlight any discrepancies within credit reports.

By promptly addressing inaccuracies through the assistance of credit monitoring tools, individuals equip themselves with the necessary information to dispute any questionable debt entries effectively.

Through this preemptive step, they can significantly reduce the risk of potential lawsuits and resolve financial matters swiftly and efficiently.

File a Complaint with the Consumer Financial Protection Bureau

Submitting a complaint to the Consumer Financial Protection Bureau can be a strategic step in addressing issues with DCM Services, requiring proper documentation and evidence to support the complaint and facilitate regulatory intervention.

When preparing to lodge a complaint against DCM Services, individuals should ensure that all interactions and communications with the company are documented meticulously. This documentation can include emails, letters, phone call records, and any other correspondence that highlights the issue at hand.

Providing detailed information helps the Consumer Financial Protection Bureau better understand the situation, assess the validity of the complaint, and take appropriate action.

Seek Legal Help
legal help

Engaging legal assistance when dealing with DCM Services can offer valuable support in navigating complex debt scenarios, addressing potential issues like wage garnishment, and seeking professional guidance for debt settlement negotiations.

By seeking legal aid, individuals can access a wealth of knowledge and experience to help them understand their rights and options when facing debt challenges.

Legal representation can provide a shield against aggressive collection tactics, helping to prevent or mitigate the risk of wage garnishment.

Having a skilled lawyer on your side can significantly enhance your chances of a successful debt settlement process, ensuring fair and manageable resolutions.

If you are getting calls from other collection agencies like CCS offices, you can beat them with a qualified and skilled attorney at your side. You can also check our guide on how to beat CCS Offices, if you are getting calls from them.

Frequently Asked Questions

How can DCM services affect me?

If you have a family member who has passed away and had outstanding debts, DCM Services may contact you to collect the debt. It is important to know your consumer rights before dealing with them.

What are my consumer rights when dealing with DCM Services?

As a consumer, you have the right to request validation of the debt, dispute the debt, and request that all communication be done in writing. DCM Services must comply with these requests.

How can I beat DCM Services and their debt collection efforts?

The best way to beat DCM Services is to know your consumer rights and exercise them. Request validation of the debt and dispute it if necessary. You can also seek legal advice and representation to protect your rights.

What happens if I ignore DCM Services?

If you ignore DCM Services, they may continue to contact you and may even take legal action to collect the debt. It is important to address the situation and exercise your consumer rights.

Can I negotiate with DCM Services to settle the debt?

Yes, you can negotiate with DCM Services to settle the debt for a lower amount. It is important to do your research and only agree to a settlement that you can afford. Make sure to get any agreement in writing and keep records of all communication.
How To Beat UCB Collections?

February 28, 2024 By Kevin Keenan

Are you being contacted by UCB Inc? Wondering if United Collection Bureau is legitimate?

This article provides information about UCB, including complaints and bad reviews. Find out how the FDCPA can protect you from UCB debt collectors and what steps you can take if they start contacting you.

Learn about your rights and how to negotiate a payment plan. Stay informed on how to avoid being contacted by UCB collectors.

Key Takeaways:

  • Understand your rights under the FDCPA to protect yourself from UCB collections.
  • Verify the debt and negotiate a payment plan to handle UCB collectors.
  • Stay proactive by paying debts on time, keeping records, and communicating with creditors to avoid being contacted by UCB collectors.

What is UCB Inc?

UCB collections 1

UCB Inc, also known as United Collection Bureau, is a company specializing in debt collection services.

Founded in 1959, UCB Inc has established itself as a trusted name in the industry, aiding individuals and businesses in recovering outstanding debts. Their team of professionals employs a customer-centric approach, prioritizing ethical and legal practices in all debt collection processes.

UCB Inc offers a range of services, including debt recovery, skip tracing, credit reporting, and account monitoring, catering to various client needs.

By using advanced technology and strategies, they ensure efficient and effective debt collection while maintaining compliance with relevant regulations.

Plus traditional debt collection methods, UCB Inc also focuses on educating clients about financial responsibility and debt management, reflecting their commitment to long-term financial wellness.

Is United Collection Bureau Legitimate?

United Collection Bureau‘s legitimacy has come into question due to numerous complaints and negative reviews.

Consumers have voiced concerns over aggressive collection tactics used by United Collection Bureau, alleging harassment and intimidation tactics.

Many have reported misleading information provided during collection calls, causing confusion and frustration.

The Fair Debt Collection Practices Act (FDCPA) plays a crucial role in regulating how debt collectors like United Collection Bureau operate, protecting consumers from abusive practices.

What Are the Complaints and Bad Reviews About UCB?

Complaints and bad reviews about UCB typically involve issues with aggressive debt collection tactics and poor customer service.

Consumers have expressed frustration over what they perceive as unfair and harassing behavior by UCB’s debt collectors.

Many customers have reported receiving multiple calls a day, even after requesting to cease communication or disputing the debts. This kind of relentless pursuit can leave individuals feeling stressed and overwhelmed.

The lack of empathy and understanding from the customer support team at UCB has only exacerbated these negative experiences.

It seems that the company’s focus on collecting debts overshadows their commitment to assisting and supporting their clients during challenging financial times.

How Can the FDCPA Protect You from UCB Debt Collectors?

The FDCPA offers protections to consumers from UCB debt collectors by outlining rights and regulations that debt collectors must adhere to.

One important provision of the FDCPA is the restriction it places on debt collectors from using deceptive or abusive practices when contacting consumers for debt collection purposes. This includes prohibiting actions such as making false statements or threats, harassing individuals, or using unfair methods in the pursuit of debt payments.

The FDCPA mandates that debt collectors must provide accurate information regarding the debt, including the amount owed and the creditor to whom the debt is owed. This ensures transparency and accountability in the debt collection process.

What to Do If UCB Collectors Start Contacting You?

dealing with UCB collectors

If UCB collectors begin contacting you, it is crucial to understand your rights under the FDCPA and take appropriate actions to address the situation.

Verifying the legitimacy of the debt is the initial crucial step. Request validation of the debt in writing within 30 days of the initial contact to ensure you are dealing with a legitimate collector.

If there are any doubts about the validity of the debt or the conduct of the collector, considering seeking legal assistance is a wise decision. Legal professionals specialize in consumer rights can provide valuable guidance and support.

If the collector engages in abusive or unfair practices, filing a complaint with the Consumer Financial Protection Bureau (CFPB) can alert regulatory authorities to potential violations.

Exploring negotiation options to resolve the debt amicably can also be beneficial. Initiate communication with the collector to discuss payment plans or settlements that work for both parties.

Understand Your Rights Under the FDCPA

Understanding your rights under the FDCPA is essential when dealing with debt collectors like those from UCB.

Consumers have the right to request verification of the debt in writing within 30 days of initial contact, giving them the power to dispute any inaccuracies. The FDCPA prohibits debt collectors from engaging in abusive practices, such as incessant calling or using threatening language.

Your rights also include the right to sue a debt collector in a state or federal court within one year of a violation. It is crucial to be aware of these protections to ensure you are not taken advantage of during debt collection processes.

Verify the Debt

Verifying the debt with UCB collectors involves requesting a validation notice and sending a formal debt dispute letter if necessary.

Upon receiving a debt collection notice from UCB, individuals should promptly request validation of the debt by sending a written request via certified mail. This validation notice should include details such as the amount owed, the original creditor, and a statement confirming the collector’s authority.

If discrepancies arise during the verification process, consumers have the right to dispute the debt. This can be done by submitting a formal dispute letter to UCB, clearly outlining any errors or inaccuracies found in the debt information. It is crucial to include any supporting documents that can validate the inaccuracies claimed.

Negotiate a Payment Plan

Negotiate a Payment Plan

Negotiating a payment plan with UCB collectors can help resolve outstanding debts through structured agreements or pay-for-delete arrangements.

When faced with mounting debts, having open communication with UCB collectors is crucial. By initiating discussions about repayment terms, individuals can explore various options to alleviate their financial burdens.

One popular avenue is to propose a structured payment plan that is manageable within one’s budget constraints. Such arrangements typically involve set monthly installments over an agreed period.

Alternatively, individuals may also consider negotiating pay-for-delete agreements with UCB collectors, a strategy where the debt is erased from credit reports upon settlement. This approach can be appealing for those looking to improve their credit standing while settling debts.

File a Complaint with the CFPB

Submitting a complaint to the CFPB about UCB collectors can help address issues of misconduct or violations of consumer rights.

When individuals encounter unfair practices or misleading behavior from debt collectors working for UCB, they can seek resolution through the Consumer Financial Protection Bureau (CFPB). The process entails gathering relevant evidence, such as communication records and account statements, to support the complaint.

Upon submission, the CFPB reviews the complaint, investigates the allegations, and works towards resolving the issue in compliance with consumer protection laws.

By reporting these instances to the CFPB, consumers not only seek redress for themselves but also contribute to upholding ethical standards in debt collection practices.

Seek Legal Help

Seek Legal Help

Engaging legal assistance when dealing with UCB collectors may be necessary, especially in cases involving potential legal action or disputes.

Legal counsel plays a crucial role in navigating the intricacies of debt collection laws and regulations, providing expert guidance on how to respond to collection attempts effectively.

By consulting a lawyer, individuals can gain a better understanding of their rights and legal options, such as negotiating settlements, challenging inaccurate information, or defending against potential lawsuits.

How Can You Avoid Being Contacted by UCB Collectors?

To prevent unwanted contact from UCB collectors, consumers can take proactive measures to manage their debts and protect their financial well-being.

One effective strategy is to ensure timely debt payments to creditors, as this demonstrates financial responsibility and reduces the likelihood of debt collection actions.

Maintaining open lines of communication with creditors can help in negotiating manageable repayment plans or seeking financial assistance if needed.

It is crucial for consumers to educate themselves about their consumer rights under the law, which can give the power to them to challenge any unfair debt collection practices.

Pay Your Debts on Time

Maintaining timely payments on debts can help prevent escalation with UCB collectors and protect your credit score.

By ensuring you make your debt repayments on time, you not only avoid the stress of dealing with collection agencies but also safeguard your credit score from negative impacts. This is crucial for maintaining your overall financial stability and credibility.

Late payments can have a significant adverse effect on your credit report, making it harder for you to secure favorable terms on future loans or credit opportunities.

Staying current on your debts demonstrates your responsible financial behavior, which is essential for lenders when assessing your creditworthiness. It is a proactive step towards building and maintaining a positive financial reputation.

Keep Records of Your Payments

Keeping detailed records of your payments can serve as evidence in case of disputes or errors raised by UCB collectors.

Clear payment documentation plays a crucial role in ensuring smooth communication with UCB collectors. By having organized records, you can quickly verify any discrepancies that may arise and provide accurate information to resolve issues efficiently.

These records act as a safety net, safeguarding you against potential errors or misunderstandings. They serve as a reliable source of data to support your claims and protect your rights in case of disputes.

Communicate with Your Creditors

Open communication with creditors and debt collectors can facilitate negotiation processes and help clarify any uncertainties in the debt validation process.

By engaging in transparent discussions with creditors and UCB collectors, individuals can address any queries, verify the accuracy of debts, and explore potential avenues for resolving outstanding balances.

This openness fosters a collaborative environment that can lead to more favorable terms, such as reduced interest rates, waived fees, or structured repayment plans that work within one’s financial capabilities.

By openly communicating concerns and seeking validation of debts, debtors can ensure that they are dealing with legitimate entities and avoid falling victim to fraudulent practices.

Know Your Rights Under the FDCPA

Understanding your rights under the FDCPA, including limitations on debt collection practices, is crucial when engaging with UCB collectors.

Consumers are protected by the Fair Debt Collection Practices Act (FDCPA), which outlines rules that debt collectors must follow. These rules prohibit abusive practices such as harassment or deceitful tactics when attempting to collect debts.

It is important to be aware of the statutes of limitations that govern how long a debt collector can legally pursue repayment for a particular debt.

By familiarizing yourself with these regulations, you can ensure that your rights are respected and that any collection efforts are conducted within the boundaries of the law.

However, if you are getting calls from DCM services, here’s how to beat DCM Services.

Frequently Asked Questions

Is United Collection Bureau a legitimate company?

Yes, United Collection Bureau (UCB) is a legitimate debt collection agency that has been in operation since 1959. However, it has received many complaints and bad reviews from consumers.

What is the FDCPA and how does it protect me from UCB collectors?

The Fair Debt Collection Practices Act (FDCPA) is a federal law that outlines the rules and regulations that debt collectors, including UCB, must follow when attempting to collect a debt. It protects consumers from abusive, deceptive, and unfair debt collection practices.

Can I dispute a debt with UCB collections?

Yes, you have the right to dispute a debt with UCB collections. If you believe that the debt is not yours or the amount is inaccurate, you can send a written dispute letter to UCB within 30 days of their initial contact. They must then provide proof of the debt before continuing to collect from you.

How can I beat UCB collections?

The best way to beat UCB collections is to know your rights under the FDCPA and to be proactive in managing your debt. Keep records of all communication with UCB, including phone calls and letters. If they violate your rights, you can file a complaint with the Consumer Financial Protection Bureau.

What should I do if UCB collectors start contacting me?

If UCB collectors start contacting you, the first thing you should do is request debt validation. This means asking for proof of the debt and making sure it is accurate and belongs to you. You should also familiarize yourself with your rights under the FDCPA and keep a record of all communication with UCB.

Can I negotiate with UCB to settle my debt?

Yes, you can negotiate with UCB to settle your debt for a lower amount. It is important to keep records of any agreements and to get everything in writing. Be sure to only agree to a payment plan that you can afford, and never give UCB access to your bank account.

How To Stop Calls From GLA Collections?

February 27, 2024 By Kevin Keenan

To Stop calls from 502-267-7522 or GLA collections, verify the debt, negotiate a payment plan, report the number to the FTC or seek legal help.

Are you receiving calls from GLA Collections and wondering why?

In this article, we will explore who GLA Collections is, the reasons for debt collection calls, and how to verify the legitimacy of the company.

We will also discuss effective ways to stop calls from GLA Collections, such as requesting proof of debt, sending a cease and desist letter, and reporting the number to the FTC.

If you owe money to GLA Collections, we will provide tips on verifying the debt, negotiating a payment plan, and seeking credit counseling.

Stay tuned for useful information on dealing with debt collection calls.

Key Takeaways:

  • Verify the legitimacy of GLA Collections before taking any action to stop calls.
  • Request for proof of debt and send a cease and desist letter to stop calls from GLA Collections.
  • If you owe money to GLA Collections, negotiate a payment plan and seek credit counseling to manage the debt.
How to stop calls from gla collections?

Who is GLA Collections?

GLA Collections is a debt collection agency specializing in the recovery of outstanding debts on behalf of creditors.

With a focus on professionalism and efficiency, GLA Collections provides a range of services to assist creditors in retrieving their overdue payments. Their clientele includes a diverse mix of businesses, financial institutions, and individuals seeking assistance in recovering unpaid debts.

Whether it is credit card debt, medical bills, or personal loans, GLA Collections handles a variety of debt types.

Using both traditional and modern debt collection techniques, they tailor their approach to each case, striving to achieve successful outcomes while maintaining ethical practices.

Why Am I Receiving Calls from GLA Collections 502-267-7522?

Receiving calls from GLA Collections may indicate that you have an outstanding debt that has been assigned to them for collection.

Often, individuals find themselves in this situation due to various reasons. It could be because they have fallen behind on their bills, resulting in utility companies or service providers forwarding the unpaid amounts to collection agencies like GLA Collections.

Loans that have gone into default, such as mortgage payments or car loans, can also lead to debt being handed over for collection.

Another common scenario is high outstanding balances on credit cards that have not been repaid on time.

What Are the Possible Reasons for Debt Collection Calls?

Debt collection calls can be initiated for various reasons, including unpaid credit card bills, defaulted loans, or outstanding medical expenses, prompting collection agencies like GLA Collections to seek repayment.

Unpaid credit card bills are a common cause for debt collection calls, often stemming from overspending or financial hardship.

Defaulted loans, whether from personal, student, or business sources, can lead to intense collection efforts.

Outstanding medical expenses, accrued from unexpected illnesses or emergencies, can also escalate to debt collection if left unresolved.

These financial obligations can pile up quickly, especially when coupled with high-interest rates or missed payment deadlines.

As a result, individuals may find themselves facing persistent calls from collection agencies like GLA Collections as they pursue repayment for these outstanding debts.

Is GLA Collections a Legitimate Company?

Is GLA Collections a Legitimate Company - How to stop calls from gla collections

GLA Collections is a legitimate debt collection agency operating within the boundaries of the Fair Debt Collection Practices Act.

The company’s commitment to abiding by industry regulations, such as the Fair Debt Collection Practices Act, ensures that their practices are ethical and lawful. GLA Collections’ adherence to these guidelines not only highlights their professionalism but also showcases their dedication to operating with integrity.

The company holds accreditations and affiliations that further validate its legitimacy in the debt collection sector.

These affiliations serve as a testament to GLA Collections’ reputation for ethical debt collection practices and solidify their position as a trustworthy agency in the industry.

How Can I Verify the Legitimacy of GLA Collections?

To verify the legitimacy of GLA Collections, you can request validation information regarding the debt they are attempting to collect from you.

Once you have requested validation information, carefully review the details provided in the validation notice to ensure it aligns with your records.

Pay close attention to the amount owed, the original creditor’s name, and any dates associated with the debt. If there are any discrepancies or uncertainties, consider reaching out to GLA Collections for clarification.

Ask for copies of any relevant collection documentation, such as the original debt agreement or statements. Review these documents thoroughly to confirm the accuracy of the information and the validity of the debt being pursued.

Verify the credentials of GLA Collections by checking their licensing and accreditation. Ensure they are licensed to operate in your state and inquire about any professional affiliations they may have. This step adds an extra layer of assurance regarding their legitimacy and professionalism.

How to Stop Calls from GLA Collections?

Stopping calls from GLA Collections can be achieved through various methods such as requesting proof of debt, sending a cease and desist letter, blocking the number, reporting to the FTC, or seeking legal assistance.

If you opt to request proof of debt, ensure that you do so within the stipulated timelines to exercise your rights effectively. Sending a cease and desist letter can communicate your desire for them to cease communication, backed by consumer protection laws.

Blocking the number on your phone is a quick fix to avoid constant interruptions. Reporting to the FTC not only helps address your case but can also contribute to larger regulatory actions against unfair debt collection practices. Seeking legal assistance can offer guidance on your rights and the steps to take for resolution.

Request for Proof of Debt

Requesting proof of debt from GLA Collections is a crucial step in validating the legitimacy of the debt they are attempting to collect from you.

By requesting validation of the debt, you ensure that the collection agency has the right to collect the amount from you. The validation notice should include details such as the original creditor’s name, the amount owed, and any relevant account information.

This process helps in verifying that the debt is indeed yours and not a mistake or fraud. It also ensures that the collection agency has the legal authority to pursue the debt.

Without proper validation, you could end up paying for a debt that may not be yours, or for an amount that is inaccurate.

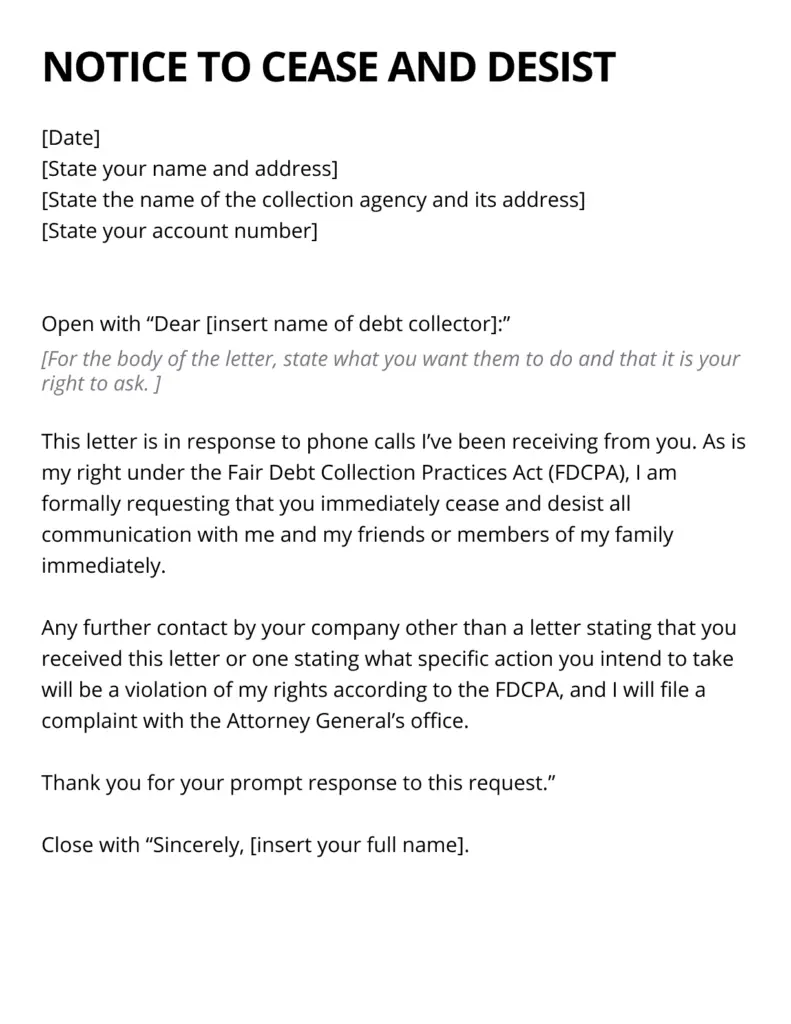
Send a Cease and Desist Letter

Send a Cease and Desist Letter

Sending a cease and desist letter to GLA Collections can legally require them to stop contacting you regarding the debt.

When preparing such a correspondence, it is crucial to clearly outline your demand for them to cease all communication, as continued contact could be a violation of the Fair Debt Collection Practices Act (FDCPA).

Include your personal information, the account details, and the specific language requesting the cessation of communication in a firm and professional tone.

It’s essential to send the letter via certified mail with a return receipt to ensure proof of delivery and establish a paper trail in case legal action becomes necessary.

Block the Number

Blocking the number used by GLA Collections is an effective way to prevent further calls from reaching you.

When dealing with persistent debt collectors, it’s crucial to take proactive steps to protect your peace of mind and privacy.

First and foremost, ensure that you have the correct number that GLA Collections is using to contact you. Once you have this information, you can proceed to block the number on your smartphone or landline.

On most smartphones, you can easily block a number by going to your call history or settings. You may want to consider utilizing call-blocking apps that offer more robust features for filtering unwanted calls.

Report the Number to the FTC

Reporting the number used by GLA Collections to the FTC can help address issues of harassment or abusive communication tactics.

When providing these details to the FTC, it is essential to include specific instances of unwanted calls, including the dates and times they occurred. This information plays a crucial role in establishing a pattern of behavior, thus strengthening your case against the violators of consumer rights.

Documenting the nature of the calls, whether they involve threats, persistent harassment, or misleading information, adds weight to your complaint.

Remember, the more thorough and accurate your documentation, the higher the chances of the FTC taking regulatory action against GLA Collections or any other entity engaged in such practices.

Seek Legal Help

Engaging a consumer attorney for assistance in dealing with GLA Collections can provide legal support and protection under the Fair Debt Collection Practices Act.

Consumer attorneys are well-versed in the intricacies of debt collection laws and can assess the situation objectively to determine the best course of action.

By seeking legal counsel, individuals can benefit from strategic negotiation skills that attorneys possess, which can lead to reduced debts or more favorable repayment terms.

Attorneys can help in identifying any potential violations of the Fair Debt Collection Practices Act by agencies like GLA Collections, and take appropriate legal action to protect the consumer’s rights. This proactive approach can alleviate stress and provide a sense of security during challenging debt collection situations.

What to Do If I Owe Money to GLA Collections?

What to Do If I Owe Money to GLA Collections - How to stop calls from gla collections

If you owe money to GLA Collections, it is essential to take proactive steps to address the debt and explore repayment options.

Start by requesting debt verification from GLA Collections to ensure the accuracy of the amount owed. This step can help you understand the details of the debt and your rights as a consumer.

Once you have verified the debt, consider reaching out to GLA Collections to negotiate payment terms that are manageable for you.

Be honest about your financial situation and see if you can set up a payment plan or settle the debt for a reduced amount.

Seek guidance from a reputable credit counseling service to develop a personalized financial management plan. They can provide valuable advice on budgeting, debt repayment strategies, and improving your credit score.

Verify the Debt

Verifying the debt with GLA Collections ensures that you have accurate information regarding the owed amount and the legitimacy of the collection efforts.

By requesting validation details from GLA Collections, you can ascertain the validity of the debt in question. It is crucial to review the documentation provided, such as original creditor information, details of the debt, and any relevant payment history. Ensuring the accuracy of these records can help you avoid potential disputes or wrongful payments.

Taking the time to verify the debt before proceeding with any payments adds a layer of protection for your financial well-being and helps maintain transparency in the collection process.

Negotiate a Payment Plan

Negotiating a customized payment plan with GLA Collections can help you address the debt in a structured and manageable way.

When you initiate negotiations with GLA Collections, it is essential to outline your financial situation honestly and transparently. By fostering open communication from the start, you set the foundation for a smoother negotiation process.

Establishing realistic repayment schedules tailored to your income and expenses can alleviate stress and set clear expectations for both parties.

This proactive approach not only demonstrates your commitment to resolving the debt but also increases the likelihood of reaching a mutually beneficial agreement.

Remember, clear and respectful communication is key in navigating payment arrangements with debt collectors.

Make Payments on Time

Making timely payments to GLA Collections is essential for resolving the debt and preventing further negative impacts on your credit score.

When you meet your payment obligations to GLA Collections in a timely manner, you not only fulfill your financial responsibilities but also demonstrate a commitment towards improving your credit standing.

By honoring your payments on time, you show creditors and credit bureaus that you are reliable and trustworthy, which can positively impact your credit report and score.

Failing to make timely payments, on the other hand, can lead to increased debt, late fees, and even potential legal actions from collection agencies. It can tarnish your credit history, making it difficult to secure loans or obtain favorable interest rates in the future.

Keep Records of Payments

Keep Records of Payments

Maintaining detailed records of payments made to GLA Collections helps ensure transparency and accountability throughout the debt repayment process.

Proper documentation is crucial when managing interactions with debt collection agencies like GLA Collections.

By keeping organized records of all financial transactions, communications, and agreements, individuals can prevent any potential disputes or misunderstandings in the future. This includes saving copies of payment receipts, emails, letters, and any written agreements.

Having well-maintained records not only benefits the debtor but also provides a layer of protection in case of any discrepancies or challenges with GLA Collections. These documents serve as concrete evidence in case of any need for legal recourse or dispute resolution, ensuring that all parties are held accountable.

Seek Credit Counseling

Consulting with a credit counseling service can provide valuable insights and assistance in managing debts owed to GLA Collections.

These professionals are equipped with the knowledge and skills to assess your financial situation and create a tailored plan to tackle your debts effectively.

Through budgeting guidance, negotiation with creditors, and implementation of debt relief strategies, credit counselors can help you regain control over your finances.

By enrolling in a debt management program recommended by credit counselors, you may benefit from reduced interest rates, waived fees, and a structured repayment schedule, all of which can expedite your journey towards debt freedom.

Frequently Asked Questions

How can I stop calls from GLA Collections?

You can stop calls from GLA Collections by requesting a cease and desist letter from the company, sending a written request to stop the calls, or blocking the number on your phone.

What should I do if I continue to receive calls from GLA Collections?

If you continue to receive calls from GLA Collections after requesting them to stop, you can file a complaint with the Federal Trade Commission or seek legal action against the company.

Who is calling me from 502-267-7522?

The number 502-267-7522 belongs to GLA Collections, a debt collection agency that specializes in collecting medical debts.

Is GLA Collections a legitimate company?

Yes, GLA Collections is a legitimate company that has been in business for over 30 years and is licensed and bonded to collect debts in multiple states.

Can I negotiate with GLA Collections to stop the calls?

Yes, you can negotiate with GLA Collections to stop the calls by setting up a payment plan or settling the debt. However, make sure to get any agreement in writing to avoid any misunderstandings.

Are there any other ways to stop calls from GLA Collections?

Yes, you can also enroll in a debt management program through a credit counseling agency to handle your debts, which may also put a stop to the calls from GLA Collections.

How To Stop Calls From Covington Credit?

February 27, 2024 By Kevin Keenan

To stop calls from covington credit, send them a cease and desist letter or seek assistance from an FDCPA attorney.

Are you receiving calls from Covington Credit and wondering why they are on your credit report?

We will dive into understanding Covington Credit, including whether they are a debt collection agency and who they collect for.

Explore the impact Covington Credit can have on your credit score and find tips on dealing with their calls.

Learn how to remove Covington Credit from your credit report and empower yourself financially by knowing your rights and options.

Stay tuned for valuable resources and steps to take action today.

Key Takeaways:

  • Understand why Covington Credit is on your credit report and if they are a debt collection agency.
  • Covington Credit can negatively impact your credit score, but there are ways to stop their calls and remove them from your report.
  • Take action by knowing your rights when dealing with Covington Credit, seeking help and utilizing resources.

Understanding Covington Credit

How To Stop calls from covington credit

Covington Credit, a debt collection company, plays a significant role in the credit report ecosystem by managing debts on behalf of creditors.

Founded in 1991, Covington Credit has established itself as a reputable agency that specializes in collecting overdue debts from individuals who have fallen behind on payments.

Through their expertise and resources, Covington Credit works directly with creditors to recover outstanding balances, ensuring that debts are settled and payments are made. This not only benefits creditors by helping them recoup money owed to them, but it also impacts individuals’ credit reports.

When debts are successfully managed and resolved by Covington Credit, it can lead to improved credit scores and financial stability for debtors.

What is Covington Credit and why are they on your credit report?

Covington Credit is a debt collection company that appears on your credit report due to its role in managing and collecting outstanding debts on behalf of creditors.

When a consumer falls behind on payments to a creditor, the creditor may enlist a debt collector like Covington Credit to help recover the owed amount.

Debt collectors act as intermediaries between the creditor and the debtor, facilitating communication and attempting to secure payment on the overdue account.

By showing up on your credit report, Covington Credit signifies to other creditors and lenders that you have had past issues with debt repayment. This transparency is crucial for assessing a person’s creditworthiness and can impact future loan approvals and interest rates.

Is Covington Credit a debt collection agency?

Yes, Covington Credit is a legitimate debt collection agency that specializes in managing and collecting overdue debts on behalf of creditors.

Established with a strong commitment to ethical practices, Covington Credit has earned a reputation for its professionalism and adherence to industry standards.

As a legitimate player in the debt collection agency landscape, Covington Credit ensures that all interactions with debtors are conducted with respect and in compliance with regulations.

Their approach is not only effective in recovering outstanding debts but also prioritizes maintaining positive relationships between creditors and debtors.

Covington Credit’s dedication to transparency and fairness sets it apart as a trusted partner for creditors seeking assistance in managing delinquent accounts.

Who does Covington Credit collect for?

Covington Credit primarily collects debts for various creditors who have authorized the company to pursue outstanding payments on their behalf.

The collaborative nature of debt collection often involves a symbiotic relationship between the debt collector and creditors.

Debt collection partnerships require transparent communication channels, where both parties work together to ensure fair and ethical practices in the debt recovery process.

By representing the clients and creditors effectively, Covington Credit maintains a reputation for professionalism and efficiency in handling debt collection activities.

This collaborative approach helps in streamlining the debt collection process and facilitates smoother communication and resolution of outstanding debts.

Impact on Credit Score

Covington Credit’s actions can have a significant impact on your credit score, especially if payment issues or accounts in collections are involved.

Payment history is a critical factor in determining your credit score. If Covington Credit reports consistent on-time payments, it can positively impact your score. If payments are missed or late, it can result in a negative effect.

Accounts in collections can severely damage your credit score. When Covington Credit places an account with a collection agency, it shows that the debt has not been paid and can stay on your credit report for seven years.

Managing these collections accounts properly by negotiating settlements or payment plans can help minimize the impact on your score.

Does Covington Credit negatively affect your credit score?

Covington Credit’s involvement can lead to negative impacts on your credit score, particularly if there are errors in reporting or delays in account resolutions.

When errors are present in your credit report due to Covington Credit’s actions, it can hinder your credit repair efforts and make it challenging to rectify inaccuracies swiftly. These errors might result in lower credit scores, as timely corrections are crucial for maintaining a healthy credit profile.

Delays in resolving account discrepancies caused by Covington Credit can lead to prolonged negative impacts on your credit standing, affecting your ability to access favorable loan terms or credit opportunities. It is essential to stay vigilant and promptly address any issues that arise, working towards maintaining an accurate credit report and a positive credit score.

Dealing with Covington Credit Calls

stop calls from covington credit

When facing incessant calls from Covington Credit, understanding your rights and options can help mitigate harassment and address unwanted phone call issues.

In dealing with persistent calls from Covington Credit, it is crucial to be aware of the protections afforded to you under consumer laws.

One effective strategy is to send a cease and desist notice, informing the company to stop contacting you.

Documenting each call, including the date and time, can serve as evidence in case further action is necessary.

Remember that you have the right to request the company to cease all communications with you, and if the calls persist, consider seeking legal advice to explore options for filing a formal complaint or pursuing legal action.

Reasons for receiving calls from Covington Credit

Calls from Covington Credit may occur due to debt validation processes, legal obligations under the Fair Debt Collection Practices Act, or the need for sharing essential information regarding debts.

When Covington Credit contacts individuals, it is often to ensure the accuracy and validity of the debt validation process. This involves confirming details related to outstanding debts to safeguard both the consumer and the debt collector in compliance with the FDCPA.

These calls serve as a means of informing consumers about their rights, obligations, and any necessary steps to take regarding their outstanding debts, creating an open and transparent dialogue between the parties involved.

Ways to get Covington Credit to stop calling

To cease unwanted calls from Covington Credit, sending a cease and desist notice or seeking assistance from an FDCPA attorney to address potential monetary damages can be effective strategies.

When dealing with persistent unwanted calls, it is crucial to understand your rights and the options available to protect yourself. Some individuals may also opt to engage legal representation to handle the situation more effectively.

Along with sending a cease and desist notice, documenting each call received from Covington Credit can help support any legal action taken in the future. Individuals who have experienced harassment or abuse through these calls might consider filing a complaint with the Consumer Financial Protection Bureau for additional support.

Will Covington Credit resort to legal actions like suing or garnishing wages?

Covington Credit may escalate to legal actions such as lawsuits or wage garnishments if debt settlement attempts fail or in cases of potential illegal actions by creditors.

When faced with persistent challenges in debt settlement negotiations, Covington Credit may resort to filing a lawsuit against the debtor to recover the outstanding amount.

In cases where creditors engage in unethical or illegal actions during debt collection, Covington Credit has the option to pursue legal actions as a means of protecting consumer rights.

This may involve seeking court orders for wage garnishments, wherein a portion of the debtor’s salary is withheld to meet the debt obligations.

These measures are taken to enforce compliance with repayment agreements and ensure fair treatment in debt collection processes.

Removing Covington Credit from Your Report

Removing Covington Credit from Your Report

Eliminating Covington Credit from your credit report involves engaging with credit bureaus, addressing delinquent debt issues, and sending formal debt validation letters when necessary.

When starting this process, it is crucial to first request your credit report from the three major credit bureaus: Equifax, Experian, and TransUnion.

Carefully review the information related to Covington Credit on each report. If there are inaccuracies or fraudulent entries, you should dispute these with the respective credit bureaus.

In cases where there are legitimate debts owed to Covington Credit, it’s essential to determine the status of these debts and work towards resolving them. This may involve negotiating a settlement or payment plan with Covington Credit directly.

How to remove Covington Credit from your credit report?

Removing Covington Credit from your credit report may involve negotiating pay-for-delete agreements, submitting dispute claims to credit bureaus, and verifying debts through the debt validation process.

Pay-for-delete negotiations entail directly working with Covington Credit to settle outstanding debts with the agreement that they will remove negative entries from your credit report upon payment.

Dispute filings with credit bureaus involve formally challenging any inaccurate or incomplete information related to Covington Credit on your credit report, prompting an investigation by the bureau to verify and correct the data.

Debt validation requests are crucial as they require Covington Credit to provide proof that the debt is valid and that they have the right to collect it, ensuring accuracy and legality in the reporting process.

Options to consider: pay for delete, negotiate a settlement, or goodwill removal

When addressing Covington Credit entries, exploring options like pay-for-delete arrangements, settling debts, or requesting goodwill removals can help in improving your credit profile.

Settlement negotiations can be a viable option for managing Covington Credit entries. By negotiating a reduced payoff amount with the creditor, you can satisfy the debt and potentially have it reported more favorably on your credit report.

Goodwill removal requests involve writing goodwill letters to the creditor, appealing for the removal of negative entries out of goodwill.

Considering pay-for-delete agreements, where you pay the creditor to remove the entry from your credit report entirely, can also be an effective strategy for enhancing your credit profile.

Understanding Rights and Options

Understanding your rights under the Fair Credit Reporting Act when dealing with Covington Credit is crucial for safeguarding consumer protection and maintaining accurate credit information.

In terms of Covington Credit, being aware of how the Fair Credit Reporting Act (FCRA) intersects with your credit dealings can greatly impact your financial well-being.

The FCRA ensures that the information reported by Covington Credit and other credit bureaus is accurate, fair, and private.

Familiarizing yourself with these laws give the power tos you to dispute any inaccuracies on your credit report promptly, which in turn can affect your credit score and financial opportunities. Thus, staying informed about your rights under the FCRA is vital for protecting your consumer rights and financial health.

Know your rights when dealing with Covington Credit

Being informed about your rights when engaging with Covington Credit ensures consumer protection and give the power tos individuals in their interactions with creditors and debt collection agencies.

One of the fundamental consumer protection principles is the right to transparency in debt collection practices.

As a consumer, you have the right to be informed about the validity of the debt, receive clear communication regarding repayment terms, and dispute any inaccuracies in the information provided.

Creditors, including Covington Credit, are obligated to adhere to regulations such as the Fair Debt Collection Practices Act, which governs how they can interact with debtors. This legislation prohibits abusive or deceptive practices and outlines standards for ethical debt collection.

Debt collection agencies play a vital role in the process between creditors and debtors. These agencies are tasked with pursuing unpaid debts on behalf of creditors but must also abide by regulations ensuring fair treatment of consumers.

Additional Resources

Exploring additional resources related to Covington Credit, such as Better Business Bureau reviews, insights on Heights Finance, and information on Curo Group Holdings, can provide valuable assistance in managing debt-related concerns.

By diving into the Better Business Bureau evaluations , individuals can gain insights into the reputation and customer satisfaction levels associated with Covington Credit, aiding in making informed financial decisions.

Understanding the services offered by established financial institutions like Heights Finance can provide alternative solutions for debt management.

Exploring the background and industry presence of Curo Group Holdings offers a broader perspective on the financial landscape, potentially offering valuable industry insights and strategic direction for borrowers.”

Seeking help with Covington Credit

When in need of assistance with Covington Credit matters, seeking guidance from Better Business Bureau reports or leveraging services like MyMoneyToGo can offer valuable support and insights.

Checking out the latest reports from the Better Business Bureau can provide you with vital information regarding Covington Credit, including customer reviews, complaints, and overall business practices. This resource serves as a trustworthy platform to gauge the reputation and reliability of financial institutions.

Services like MyMoneyToGo specialize in connecting individuals with tailored financial solutions and support services to address their specific needs.

By using such advisory platforms, you open up avenues for personalized assistance and guidance to navigate the complexities of financial issues.

Reviews and complaints about Covington Credit

BBB customer reviews

Accessing reviews and complaints regarding Covington Credit on platforms like the Better Business Bureau can provide valuable insights into customer experiences and service quality.

By diving into customer feedback, individuals can uncover common themes among complaints, allowing them to gauge the overall satisfaction level of clients.

Using platforms such as the Better Business Bureau aids in understanding the specific pain points that customers encounter, helping identify areas for improvement within Covington Credit’s service delivery.

Assessing reviews also assists in recognizing commendable aspects of the company that contribute to positive customer experiences, guiding potential clients in making informed decisions about engaging with the business.

This will also help you if you are getting calls from GLA Collections and want to stop their calls?

Locating Covington Credit’s phone number and login information

Finding Covington Credit’s phone number or login details can facilitate direct communication and access to account information for effective resolution of debt-related queries.

To get in touch with Covington Credit customer service and obtain their contact information, individuals can visit the official website where they typically provide a dedicated ‘Contact Us’ section.

Here, users can find the necessary phone numbers to reach out for assistance with debt issues or account-related queries.

For those who prefer online account access, navigating to the login page on the website using secure credentials can enable seamless communication with representatives for personalized support.

Steps for a goodwill letter for collection/charge-off removal

Crafting a goodwill letter to request Covington Credit’s collection or charge-off removal from credit bureaus can be a strategic step towards improving your credit profile.

When composing this document, it’s crucial to address it to the right department within Covington Credit and ensure it includes a clear explanation of the circumstances surrounding the negative entries.

Detailing any extenuating circumstances that led to the missed payments or collections can significantly strengthen your case.

Expressing genuine remorse and a commitment to better financial responsibility can go a long way in convincing Covington Credit to consider removing the negative items from your credit reports.

Remember, the goal is to evoke empathy and understanding from the creditor, ultimately leading to a more positive credit report for you.

Empowering yourself financially by taking action today

Taking proactive steps today to address Covington Credit’s involvement can lead to financial give the power toment, improved interactions with debt collectors, and enhanced credit score management.

By managing your relationship with Covington Credit effectively, you open doors to a more stable financial future.

Through strategic communication and negotiation, you can navigate debt situations with confidence, paving the way for improved credit scores and comprehensive financial health.

Empowering yourself with the right tools and knowledge to handle debt is a crucial step towards achieving financial stability. Utilizing debt resolution strategies and establishing healthy credit habits are key ingredients in this process.

You should also check our article on How To Stop Calls From 18003907584, if you keep getting debt collection agency calls and want to stop them.

Frequently Asked Questions

How To Stop Calls From Covington Credit?

How can I stop receiving calls from Covington Credit? To stop calls from Covington Credit, you can add your number to the National Do Not Call Registry or contact Covington Credit directly to request to be removed from their call list.

Why Does Covington Credit Call?

Why am I receiving calls from Covington Credit? Covington Credit may be calling to offer you a loan or other financial services. They may also be attempting to collect on a past due account.

Can I Block Calls From Covington Credit?

Is it possible to block calls from Covington Credit? Yes, you can block calls from Covington Credit by adding their number to your phone’s block list or by using a call-blocking app.

What Steps Should I Take To Stop Calls From Covington Credit?

What should I do to stop calls from Covington Credit? You can take several steps to stop calls from Covington Credit, including registering your number on the National Do Not Call Registry and requesting to be removed from their call list.

How Often Can I Expect Calls From Covington Credit?

How frequently will Covington Credit call me? The frequency of calls from Covington Credit may vary. They may call multiple times a week or only on occasion, depending on their business needs.

What Happens If I Ignore Calls From Covington Credit?

What are the consequences of ignoring calls from Covington Credit? Ignoring calls from Covington Credit may result in missed communication about your account or potential offers and promotions. However, if you do not wish to receive calls from them, you have the right to request to be removed from their call list.

How To Stop Calls From 18003907584?

February 27, 2024 By Kevin Keenan

To stop calls from 18003907584, Enhanced Recovery Company, you can use Call Blocking Resources or Debt Validation Letter to verify the debt.

Are you tired of constantly receiving unwanted calls, especially from numbers you don’t recognize like 1-800-390-7584?

In this article, we will delve into understanding the caller, Enhanced Recovery Company, and explore various options to stop calls from this number.

We will discuss the effectiveness of avoiding Enhanced Recovery Company, legal steps to stop unwanted calls, utilizing call blocking resources, and the importance of the National Do Not Call List.

We will cover topics such as dealing with robocalls, preventing call spoofing, settling debt issues with Enhanced Recovery Company, and alternative solutions for debt collection cases.

Whether you are facing a summons for debt collection or simply want to beat credit card companies, this article provides valuable insights and strategies to help you deal with unwanted calls effectively.

Key Takeaways:

  • Receiving unknown calls can be frustrating and may be from Enhanced Recovery (1-800-390-7584).
  • Legal steps and call blocking resources can help stop unwanted calls.

Dealing with Unwanted Calls

stop calls from 18003907584

Receiving unwanted calls can be frustrating and disruptive, especially when they come from unknown numbers. These calls could be from various sources such as spammers or debt collectors, impacting consumer peace of mind and privacy.

Such unwanted calls often lead to feelings of intrusion and annoyance among individuals, disrupting their daily activities and causing unnecessary stress. Consumers find it challenging to distinguish legitimate calls from fraudulent ones, risking potential scams and deceit.

To combat this issue, call blocking features and caller ID services have become essential tools for consumers. By utilizing these solutions, individuals can filter out unwanted calls, safeguard their personal information, and regain control over their communication channels.

Understanding the Caller: Enhanced Recovery Company

When encountering calls from Enhanced Recovery Company, it is essential to understand their role as a debt collection agency and the legal boundaries within which they operate.

As a debt collection agency, Enhanced Recovery Company works on behalf of creditors to collect outstanding debts from individuals. They are required to adhere to strict guidelines outlined by the Fair Debt Collection Practices Act (FDCPA), which prohibits abusive, unfair, or deceptive practices in the collection of debts.

Consumers may receive various types of calls from Enhanced Recovery Company, including reminders about overdue payments, notifications of outstanding balances, and discussions on potential repayment options. It is crucial for individuals to verify the legitimacy of these calls by requesting written validation of the debt and confirming details before providing any personal or financial information.

Options to Stop Calls from 1-800-390-7584

If you are receiving persistent calls from 1-800-390-7584, exploring options for call blocking and filing complaints with the relevant authorities can help mitigate the unwanted disruptions.

One effective step to stop calls from specific numbers like 1-800-390-7584 is to utilize call blocking features available on most smartphones. By adding the number to your block list, you can prevent further calls from reaching your device.

Consider reaching out to your phone service provider to inquire about additional call blocking services they may offer. These services can often provide more advanced options for handling unwanted calls effectively.

Reporting such persistent unwanted calls to the FCC is crucial. By sharing details of the calls, including the number, time, and frequency, you contribute to efforts in taking legal actions against violators of communication regulations.

Effectiveness of Avoiding Enhanced Recovery Company

Avoiding interactions with Enhanced Recovery Company can be a proactive strategy to reduce unwanted debt-related calls and ensure compliance with FCC rules regarding consumer communications.

By steering clear of engagements with collection agencies like Enhanced Recovery Company, individuals can safeguard themselves from the stress of persistent phone calls related to debts.

This approach not only helps in maintaining peace of mind but also plays a crucial role in adhering to the regulations set forth by the Federal Communications Commission.

Minimizing interactions with debt collectors also aligns with the growing trend of utilizing advanced call blocking technologies to effectively manage and filter out unwanted calls.

Such technologies give the power to individuals to take control of their communication preferences and mitigate consumer complaints associated with debt collection practices.

Legal Steps to Stop Unwanted Calls

Consumers have legal rights under FCC regulations to address unwanted calls, including taking steps to revoke consent for such calls and seeking recourse in cases of harassment or legal violations.

Screenshot 2024 02 20 at 6.33.45 PM

One avenue available to consumers is to register their phone number on the National Do Not Call Registry, which prohibits telemarketers from calling registered numbers.

By doing so, individuals can significantly reduce the volume of unwanted calls they receive. Individuals can file complaints with the FCC for unsolicited calls despite being on the Do Not Call list.

However, it is crucial to remember that companies must have prior express consent to make autodialed calls, and consumers have the right to revoke this consent at any time. Failure to respect these rules can result in significant consequences for companies, including fines and legal actions.

Use Call Blocking Resources

Harnessing call blocking resources provided by FCC initiatives and consumer guides can give the power to individuals to effectively manage and reduce the impact of unwanted calls on their daily lives.

Consumers have a variety of tools at their disposal to combat unwanted calls, such as call blocking apps, built-in smartphone features, and services offered by telecommunications companies.

The FCC’s efforts like the creation of the National Do Not Call Registry have been instrumental in curbing illegal robocalls. Reputable consumer guides also provide comprehensive information on call blocking options, helping users make informed decisions.

Utilizing gateway providers can offer advanced call protection features and customizable settings for a more tailored call blocking experience, enhancing overall efficiency and security.

Importance of the National Do Not Call List

Enrolling in the National Do Not Call List maintained by the FTC is a crucial step in reducing unsolicited telemarketing calls and text messages, safeguarding consumer privacy and preferences.

For wireless phone users, this registry serves as a shield against unwanted disruptions, ensuring a more peaceful communication environment.

By gaining consumer consent and respecting their preferences, companies uphold ethical standards and foster stronger customer relationships.

Dealing with Robocalls and Robotexts

Navigating the challenges posed by robocalls and robotexts requires a combination of consumer vigilance, effective complaint reporting, and utilization of call blocking tools endorsed by regulatory bodies like the FTC.

Robocalls and robotexts have become an increasingly prevalent nuisance in the digital age, inundating phone lines and devices with unsolicited automated messages. Consumer complaints play a crucial role in combating these intrusive practices, as they provide regulatory authorities with valuable data to identify and take action against offenders.

Leveraging resources provided by the FTC can significantly enhance consumer protection. The FTC offers a robust platform for individuals to report unwanted calls and texts, not only raising awareness but also enabling regulatory initiatives. Approved call blocking tools, recommended by the FTC, give the power to consumers to proactively filter and block suspicious communications, safeguarding privacy and preventing potential scams.

Preventing Call Spoofing

Mitigating call spoofing tactics through enhanced caller ID verification and awareness of one’s communication rights can fortify consumer defenses against deceptive practices aimed at manipulating phone interactions.

Call spoofing, a malicious practice where scammers manipulate caller ID information to appear as someone else, can lead to various fraudulent activities such as phishing scams or identity theft. By implementing stringent caller ID authentication protocols, service providers can help identify and block spoofed calls before they reach consumers.

Consumers should also exercise caution when sharing personal information over the phone, especially if the caller’s identity seems suspicious. Verifying the caller’s legitimacy through an official contact number or website can provide essential validation and prevent falling victim to potential scams.

Political Calls and Texts: Regulations and Exemptions

Understanding the regulations governing political calls and texts, including exemptions for certain categories, is essential for consumers, particularly in the context of wireless phone usage and FCC compliance.

Political communication activities, such as campaign calls and messages, are subject to strict guidelines to protect consumers from unwanted solicitations and ensure transparency in messaging.

Exemptions exist for certain types of organizations, such as those conducting surveys, political polls, or informational messages.

For wireless phone users, these rules offer protection against unsolicited political content and enable them to control the communications they receive.

The FCC plays a crucial role in upholding these regulations, monitoring compliance, and taking enforcement actions when necessary to safeguard consumer rights.

Settling Debt Issues with Enhanced Recovery Company

Resolving debt matters with Enhanced Recovery Company necessitates a comprehensive understanding of debt settlement options, safeguarding against potential scams, and managing financial obligations through secure electronic payment methods.

When dealing with debt settlement processes involving Enhanced Recovery Company, it is crucial to keep thorough documentation of any communication and transactions.

Always verify the authenticity of payment demands and confirm the accuracy of the outstanding amount.

It is vital to monitor your credit reports regularly to ensure that accurate information is being reported.

Understanding and leveraging consumer protection laws such as the Fair Debt Collection Practices Act (FDCPA), Electronic Fund Transfer Act (EFTA), and Fair Credit Reporting Act (FCRA) can provide added protection and guidance throughout the debt resolution journey.

Responding to a Summons for Debt Collection

Crafting an appropriate response to a debt collection summons requires a strategic approach focused on debt settlement negotiations, protecting credit reports, and asserting consumer rights in cases of harassment or unfair practices.

When facing a debt collection summons, it’s crucial to understand your rights and options. Begin by reviewing the details of the summons thoroughly, ensuring that you have a clear understanding of the alleged debt and the procedures involved.

Negotiating debt settlements can often lead to a more manageable repayment plan, potentially avoiding legal battles and preserving your credit score. It’s advisable to communicate with the debt collection agency or creditor to discuss repayment terms that work for both parties.

Guides on Dealing with Debt Collectors

Accessing comprehensive guides for interacting with debt collectors give the power to consumers with knowledge on their rights, effective communication strategies, and compliance with legal frameworks such as FDCPA and FCRA.

Understanding your rights when dealing with debt collectors can help you navigate through challenging financial situations with confidence.

By being aware of permissible debt collection practices outlined in laws like the Fair Debt Collection Practices Act (FDCPA) and Fair Credit Reporting Act (FCRA), consumers can protect themselves from abusive tactics and unfair treatment.

Effective communication skills play a crucial role in asserting your rights and negotiating manageable repayment plans with collectors.

Consistent, clear, and concise communication can lead to mutually beneficial resolutions and prevent misunderstandings that may exacerbate the debt collection process.

Community Support for Debt Collection Challenges

Engaging with community support networks can offer valuable assistance to individuals facing debt collection challenges, fostering communication, sharing experiences, and providing solidarity in cases of harassment or disputes.

Being part of a community support system allows you to connect with others who have gone through similar situations, creating a sense of belonging and understanding.

Through these networks, individuals can gain access to valuable resources, information, and guidance to navigate the complexities of debt collection processes.

Effective communication channels within these groups facilitate the exchange of strategies and solutions, give the power toing members to deal with creditors, negotiate payment plans, or seek legal advice.

The mutual aid and encouragement found in these support systems can significantly reduce feelings of isolation and stress commonly associated with financial burdens.

Beating Credit Card Companies: Strategies and Tips

Developing effective strategies to navigate credit card company interactions involves understanding credit reports, leveraging secure electronic payment methods, asserting consumer rights, and exploring debt settlement options in compliance with FDCPA regulations.

Understanding your credit report is essential to identify errors that could affect your creditworthiness negatively. By regularly checking your credit report, you can catch any inaccuracies early and take swift action to rectify them.

Optimizing payment practices by using secure methods like encrypted online transactions or chip-enabled cards can safeguard your financial information from potential fraudsters.

Staying informed about your consumer rights give the power tos you to challenge unfair practices by credit card companies, such as unauthorized charges or deceptive marketing tactics, by seeking assistance from regulatory bodies or consumer protection agencies.

Engaging in debt settlement negotiations within the boundaries set by the FDCPA ensures that you pursue debt relief options ethically and legally, avoiding any potential harassment or unlawful practices during the settlement process.

You must read our guide on How To Stop Calls From Covington Credit, if you are getting calls from many different numbers for debt collection.

Additional Resources for Dealing with Unwanted Calls

Accessing supplementary resources for managing unwanted calls, including verified call blocking tools and consumer protection guidelines from regulatory bodies like the FTC and FCC, enhances consumer defenses against intrusive communication practices.

One of the primary resources available to consumers is the National Do Not Call Registry, maintained by the FTC, which allows individuals to register their phone numbers to avoid telemarketing calls. Utilizing call blocking apps and services can help filter out spam calls and potential scams.

Staying informed about recent updates in regulations set forth by the FCC can also give the power to consumers to recognize and report illegal robocalls, further safeguarding their privacy and financial security.

Legal Protection Through Debt Validation Letter

Leveraging the legal safeguards provided by debt validation letters give the power tos consumers to assert their rights, challenge debt collector claims, and seek validation of debts in compliance with consumer protection statutes like FDCPA and FCRA.

Debt validation letters play a crucial role in ensuring transparency and accuracy in debt collection processes. By sending a debt validation letter, consumers can request detailed information regarding the alleged debt, such as the original creditor, amount owed, and validation of ownership rights.

This process helps consumers verify the legitimacy of the debt and identify any potential errors or discrepancies.

Debt validation letters serve as a protective shield against unlawful debt collection practices, preventing harassment and undue pressure from aggressive collectors.

If you are getting calls from 2023679070, here’s our guide on how to stop calls from 2023679070.

Frequently Asked Questions

Why am I receiving calls from 18003907584?

The number 18003907584 belongs to Enhanced Recovery, a debt collection agency. They may be trying to contact you regarding an unpaid debt.

How can I stop calls from 18003907584?

You can stop calls from 18003907584 by requesting that they stop contacting you. You can also block the number on your phone or report it to the National Do Not Call Registry.

Can I block 18003907584 from calling me?

Yes, you can block 18003907584 from calling you by using the call blocking feature on your phone. You can also contact your phone carrier to see if they offer a service for blocking specific numbers.

What should I do if I don’t owe any debt and still receive calls from 18003907584?

If you don’t have any unpaid debt and are still receiving calls from 18003907584, you should contact Enhanced Recovery and inform them of the mistake. You can also file a complaint with the Consumer Financial Protection Bureau.

Is it safe to answer calls from 18003907584?

It is generally safe to answer calls from 18003907584, as it is a legitimate debt collection agency. However, if you are unsure or uncomfortable, you can choose not to answer the call.

Are there any other steps I can take to stop calls from 18003907584?

You can also register your phone number on the National Do Not Call Registry to stop telemarketing calls. Additionally, you can ask your phone carrier about call blocking options or download a call blocking app for your smartphone.

  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 43
  • Go to page 44
  • Go to page 45
  • Go to page 46
  • Go to page 47
  • Interim pages omitted …
  • Go to page 73
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers