• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

General Personal Finance Blog

The Ideal Way To Budgeting Finances Fortnightly

December 11, 2025 By Ana Rose

Budgeting your finances fortnightly can be a comforting experience especially when your finances align perfectly well with how you get paid. For many people, getting money every two weeks means money comes in faster as compared to those monthly paychecks and when you build your budgeting plan around the two weeks timeline, you can give your finances a proper structure, making them more manageable and predictable. Instead of working on larger amounts at the end of every month, budgeting every two weeks can help you manage your finances by dividing the large sum into smaller and more manageable portions. This article will help you explore ways to budget your finances fortnightly, ensuring that your finances continue to work for you, not against you. 

The Ideal Way To Budgeting Finances Fortnightly

Understand Your Fortnightly Income Clearly

The very first step when you begin your journey of budgeting fortnightly is to understand the income that’s coming in every two weeks. Instead of depending on guesswork and assuming things, a smarter approach would be to take a moment, calculate your income, and figure out what your take-home pay is. 

This can include your main salary, your allowances, or even those side hustles that you work on occasionally. Once you have a clear starting point, the rest of your journey becomes easier, giving you a direction and kickstart regarding what the journey ahead will look like. Not only does this step help you with awareness, it helps you avoid overestimating and overspending as well, helping you become more mindful and intentional with what you spend on. 

Break Monthly Expenses Into Fortnightly Portions
Illustration of a person organizing monthly expenses into two fortnightly sections using a calendar and bill icons on a pastel pink highlighted background.

The next step is to list down all your expenses, from rent to groceries, mortgage payments to subscriptions, and bills to snacks. Most of the bill payments come every month, which is exactly why it is important to plan ahead and divide the bill payment into two, so you know exactly what to set aside every two weeks to pay the bills. 

Whether it’s rent, utility bills, subscriptions, groceries, transport, or tuition fee, breaking down these non-negotiable bills into two can help you plan effectively, planning with structure and discipline. This way you can also avoid the awful feeling of watching your entire paycheck disappear the moment a new month starts because you’ve already budgeted for them in advance, making you feel more satisfied both financially and mentally. 

Use a 50/30/20 Framework Adapted for Bi-Weekly Pay
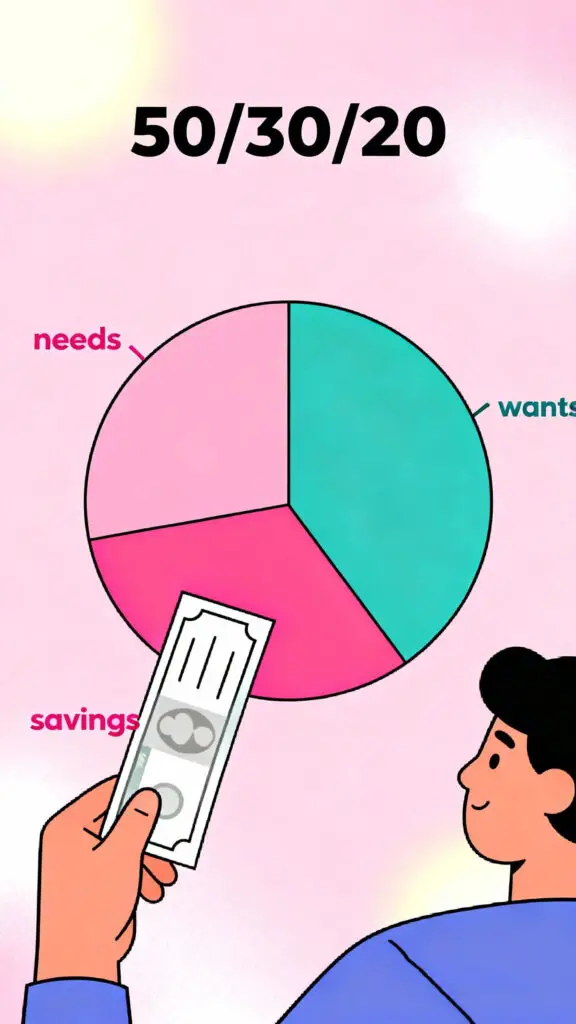
Illustration of a bi-weekly 50/30/20 budgeting pie chart with a person managing income on a pastel pink background.

The next step is to use the 50/30/20 framework which is all about dividing your paycheck into a balanced ratio with three categories. According to the rule, 50% of your income goes to your needs or those essential expenses such as rent, housing, utilities, or transport, 30% goes to your wants or the nice-to-have spending category such as takeouts, coffee runs, or subscriptions, and lastly 20% goes to savings, investments, or paying off debt, if there are any. 

What makes this different from the monthly 50/30/20 rule is that you apply the percentages to every single paycheck instead of waiting for the entire month’s income to arrive. Moreover, with this fortnight approach, you get to manage smaller amounts more frequently, making it easy to track money and adjusting your lifestyle surrounding your budgeting plan rather than struggling with big numbers each month. 

Prioritize Essential Bills First Each Fortnight

The next step is to prioritize your essential bills over the non-essential ones. This can include half of your rent, groceries, utilities, transportations, and other payments. Treat these expenses as those non-negotiable bills and set money aside for them whenever your paycheck arrives, helping you avoid confusion later on. 

Doing this simple but highly effective step can help you create peace of mind that comes along with knowing that your needs are covered before you even think about spending your hard-earned money on anything else. 

Set Up Automatic Savings Transfers

Another considerable option when it comes to budgeting your finances in an effective way is to set up automatic savings transfers. When you are paid every two weeks, small amounts build up surprisingly fast, and automating these transfers removes the temptation to spend. 

Some banking apps allow you to set up an automatic transfer so the moment your paycheck hits your account, a specific account moves to your savings account, helping you set money aside while still enjoying the money you work so hard for. What makes automation a considerable option is that it takes away the intentional effort to save, helping you save in an almost effortless way. 

Create a Cushion for Irregular Expenses

Not all expenses show up every month, some show up occasionally and some up unexpectedly which is why it is so important to prepare yourself for those expenses so you can pay for them without having to put your entire budget on stake. Instead of panicking when these expenses appear, you can create a small category in your fortnightly budget called future expenses. 

Whether it’s for a sudden medical emergency, car repair, birthdays, or holidays, having a cushion can help you plan for these expenses without having to stress over your budget. Over time this small habit can provide you peace of mind and satisfaction, knowing that in case an unexpected expense shows up, you have a safety net in place that can help you take control and make decisions with confidence. 

Use a Simple Tracking System You’ll Actually Follow

A fortnightly budget works the best if you’re tracking it in a way that doesn’t feel like a burden. You can use a budgeting app, a spreadsheet, a notebook, or something as simple as the notes app in your phone. The key is not to overwhelm yourself with details, it is more about helping you stay aware of what you spend at, allowing you to become more mindful and make changes if you identify an unhealthy spending pattern. 

Allocate Personal Pocket Money for Flexibility

When you’re budgeting every two weeks, it becomes extremely important to give yourself a little breathing room, and this is exactly where personal pocket money comes in. This small portion of your paycheck is meant just for you, allowing you to enjoy small treats or comfort purchases without feeling guilty or like you’re breaking your budget. 

Whether it’s a coffee run, a small snack, a quick outing with friends, or something fun that brightens your week, this category keeps your budget realistic and enjoyable. Allocating pocket money helps prevent overspending in other categories since you already have a space for stress-free spending, and it keeps you motivated to stick with your budget long-term because you don’t feel deprived or overly restricted.

Review and Adjust Every Two Weeks

One of the best advantages of budgeting fortnightly is the chance to reset and realign your spending habits every two weeks without waiting for an entire month to pass. This simple review session helps you understand where your money went, what categories worked well, and what areas need adjusting. 

Reviewing frequently gives you a clearer picture of your financial patterns, helping you identify small mistakes before they turn into bigger issues. It’s a chance to celebrate your small wins, correct any overspending early, and adjust plans for the next two weeks with more clarity. 

Plan Meals and Groceries Around the Fortnight Cycle

Groceries can easily take up a big portion of your income, which is why planning meals around the two-week cycle can be one of the smartest decisions. Instead of making several random trips to the grocery store and ending up with unnecessary items, you plan ahead for 14 days, listing what you need and buying intentionally. 

This helps reduce impulse buying, food waste, and the stress of last-minute meal decisions. A simple two-week meal plan can guide your shopping list and keep your food expenses within budget. Over time, this habit not only helps you save money but also saves time and energy, making your daily routine feel more organized and predictable.

Use One Paycheck for Essentials and the Other for Goals 

A helpful budgeting strategy many people find easy to follow is dividing the purpose of each paycheck into two categories, one paycheck mainly for covering essential bills and must-pay expenses, and the second paycheck for financial goals such as savings, sinking funds, debt payments, or investments. 

This method brings structure and clarity to your finances because you aren’t mixing everything together, and you always know what each paycheck is meant to accomplish. 

Conclusion

Budgeting your finances fortnightly is a practical and empowering approach that matches the flow of your income with the way you live your daily life. Instead of juggling large monthly numbers, splitting everything into two-week portions makes your expenses easier to manage, your savings easier to maintain, and your goals easier to reach. With clear steps such as dividing expenses, prioritizing essentials, automating savings, planning meals, reviewing often, and giving yourself flexible spending money, you create a system that works for you rather than controlling you. This method helps you stay consistent, confident, and financially organized, allowing your money to support you in a smoother and more intentional way.

The Best Way To Budgeting Finances For Couples

December 10, 2025 By Ana Rose

Budgeting as a couple can feel a little overwhelming in the beginning, especially when two people with different upbringings, money habits, and spending styles suddenly have to sit together and make joint financial decisions. It’s not just about numbers on a spreadsheet, it’s really about communication, trust, teamwork, and slowly creating a financial system that feels fair and comfortable for both partners. When done intentionally, budgeting becomes something that strengthens the relationship rather than creating stress. It gives both partners a sense of control, clarity, and confidence about where the money is going and how future goals will be met. And the best part is that budgeting doesn’t have to be strict or complicated, it just needs to be honest, simple, and consistent.

The Best Way To Budgeting Finances For Couples

Start With an Honest Conversation About Money

Illustration of a couple discussing finances at a table with money-related icons on a pastel pink highlighted background.

Before planning any budget, the first step is sitting down and having a very real, open-hearted conversation about money. Many couples avoid money talks because they fear disagreement, but in reality, this conversation builds understanding. Both partners should share their income, debts, spending habits, financial fears, and long-term dreams.

Make it a safe space where no one feels judged and when both people understand each other’s background and what money means to them, it becomes easier to work together. This conversation sets the foundation for future decisions, helps avoid hidden surprises, and ensures you both start the budgeting journey as a united team.

Choose Whether to Combine, Separate, or Hybrid Your Finances

Every couple is different, so there’s no single correct way to manage money. Some couples prefer fully combining finances, others prefer completely separate accounts, while many choose a hybrid system where they manage shared expenses together but maintain individual freedom. 

The key is choosing what feels fair and comfortable for both. Discuss openly how you will split bills, savings, and personal spending. The goal should be to remove confusion and resentment while giving both partners independence. When you choose the right system, budgeting becomes smoother and arguments reduce because both people understand their responsibilities clearly.

Create Shared Financial Goals Together

Illustration of a couple creating a shared financial goals board with various goal icons on a pastel pink background.

One powerful way to bond as a couple is through shared goals. Sit together and list what you want to achieve in the next few months and the next few years, maybe saving for a vacation, paying off debt, buying a car, building an emergency fund, or planning for a home. When goals are written down, they become more real and easier to work toward. 

Make sure both partners feel heard and that the goals reflect both people’s desires. You can then break these big dreams into smaller, monthly or weekly targets that feel achievable. Working toward something exciting together makes budgeting feel meaningful rather than restricting.

Track Your Combined Household Income

A couple’s budget starts with understanding exactly how much money is coming in every month. This includes salaries, freelance income, benefits, or bonuses. When both partners know the total household income, planning becomes clearer. Tracking income also helps you divide responsibilities fairly, some couples split everything 50/50, while others contribute based on their income percentage. 

There’s no right or wrong, it just needs to feel fair. Keeping a clean record of your combined income reduces confusion, makes goal-setting easier, and ensures you both have a clear picture of your financial strength as a team.

List Out All Shared Monthly Expenses

To create a stable budget, couples need to write down every fixed and variable expense, from rent and groceries to utilities, transportation, internet, subscriptions, and even small daily expenses like coffee. Many couples underestimate their monthly spending because they don’t track the tiny things. 

Listing everything helps you understand your true lifestyle costs and prevents overspending. This also makes decision-making easier because you can see where changes are needed. When both partners participate in listing expenses, it creates transparency, reduces misunderstandings, and keeps both people aligned on how the household money is being used.

Build an Emergency Fund as a Non-Negotiable

Every couple needs an emergency fund, a safe backup that protects you from unexpected situations like job loss, car repairs, medical bills, or sudden expenses. Treat this fund as a shared responsibility and aim to save at least 3 to 6 months of expenses over time. 

Start small if needed, even if it’s just a little every week because the goal is safety and peace of mind. When couples have an emergency fund, they feel more secure, argue less during stressful times, and handle challenges as a team instead of panicking or blaming each other.

Use the 50/30/20 Rule or a Similar Budgeting Framework

Budgeting becomes much easier when couples follow a simple structure because it removes the stress of guessing how much to spend or save each month. The 50/30/20 rule is a great starting point with 50% going to essential needs, 30% to wants, and 20% to savings and future planning but what makes this method truly helpful is how flexible it is. 

Every couple has different priorities, so you can adjust the percentages to match your income, goals, and lifestyle without feeling restricted. This gentle structure helps both partners stay disciplined, make more mindful spending choices, and still enjoy life without guilt. 

When the boundaries are clear yet adaptable, budgeting becomes a smooth and predictable routine that naturally reduces misunderstandings, overspending, and the small financial disagreements that often create tension in relationships.

Have Weekly or Monthly Budget Check-Ins

Budgeting is not a one-time activity, it’s something couples must revisit regularly so they can stay on track. Pick a day every week or month where you sit together, review expenses, check savings progress, and make any adjustments. 

Keep these meetings calm, short, and kind, so they don’t feel stressful. Celebrate small wins, like sticking to the budget or hitting a goal. Regular check-ins prevent misunderstandings, build trust, and ensure both partners remain involved instead of one person carrying all the financial responsibility.

Set Personal Spending Allowances

One of the biggest reasons couples fight about money is feeling controlled or judged for personal purchases. To avoid this, set personal allowances for each partner, a fixed amount each can spend freely without explaining or justifying it. 

This gives both people independence and removes guilt around treating yourself. Whether it’s shopping, hobbies, or small indulgences, having your own personal funds creates balance in the relationship. It also helps maintain the budgeting system because personal spending stays within a healthy limit.

Tackle Debt Together as a Team

If either partner has debt such as student loans, credit cards, or car financing, treat it as a shared challenge instead of one person’s burden. Discuss how you’ll prioritize repayments, whether you want to clear high-interest debt first, or focus on the smallest balance for motivation. 

Debt can create stress, so the key is building a plan that both feel comfortable with. When couples support each other instead of blaming or hiding debt, repayment becomes faster and emotionally easier. Working together makes the journey feel lighter.

Use Budgeting Apps or Shared Spreadsheets

Technology can make budgeting so much easier for couples. Apps like Goodbudget, YNAB, or even Google Sheets let you track expenses, share updates in real-time, and stay organized. 

When both partners see the numbers clearly, there’s less confusion and fewer disagreements. Use tools that match your comfort level as some prefer simple spreadsheets, while others like automated apps. The goal is to stay transparent, make tracking quick, and help both partners stay involved in managing household money.

Plan for Fun, Celebrations, and Quality Time Together

Budgeting isn’t just about bills and savings, it should also include joy. Make space in your budget for date nights, gifts, celebrations, small trips, or anything that strengthens your bond.

Couples often forget to plan for fun, and then feel guilty later when spending unexpectedly. By allocating a “fun budget,” you both enjoy life without stress. This makes financial planning feel balanced, more human, and less like a strict set of rules. A budget that includes happiness is easier to stick with long-term.

Conclusion

Budgeting for couples is not about restricting each other but about building a life together with clarity, peace, and teamwork. When both partners communicate openly, set goals together, track expenses honestly, and review progress regularly, money becomes a source of stability rather than stress. A good budget helps you achieve dreams faster, avoid unnecessary conflicts, and create a financial partnership that feels fair and supportive. Remember that budgeting is a learning process and it won’t be perfect in the beginning, but with patience, consistency, and kindness, you’ll build a financial system that works beautifully for your relationship and your future.

$10,000 Saving Challenge One Year

December 9, 2025 By Ana Rose

Saving $10,000 in a single year might feel overwhelming at first, but it becomes much more achievable once you break it down into smaller and manageable steps. A saving challenge adds discipline and direction to your financial journey, making it easy for you to stay consistent and save in an effective way. Whether you’re saving for an emergency fund, a new car, travel, or simply building long-term financial stability, committing to this challenge can be life-changing. With the right strategies, consistency, and a little creativity, you can reach your goal without feeling deprived or stressed. This article will help you explore some powerful methods you can mix, match, or follow together to successfully save $10,000 in 12 months.

$10,000 Saving Challenge One Year

Break Down the $10,000 Goal Into Monthly and Weekly Targets

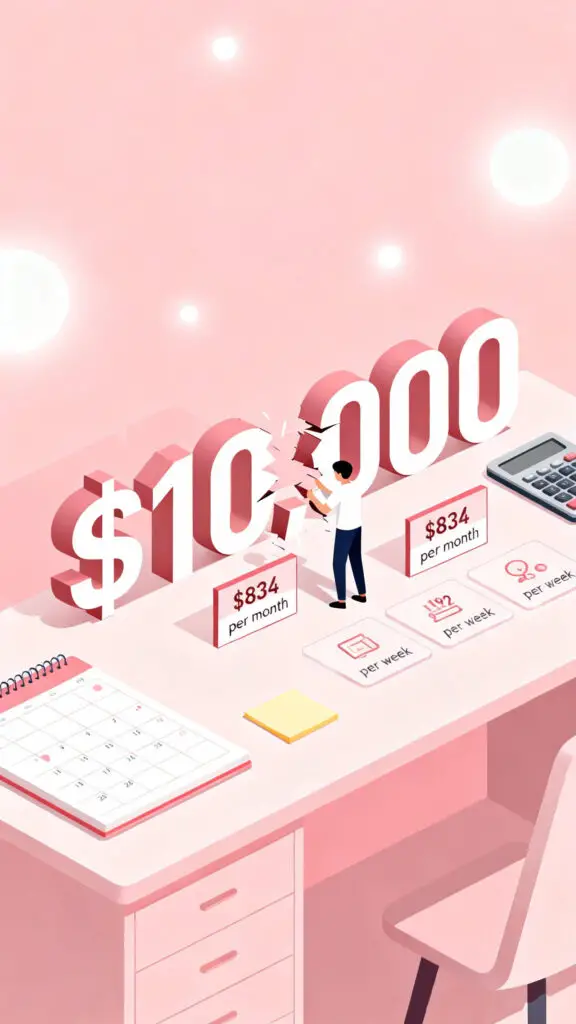
Illustration of a person dividing a $10,000 savings goal into monthly and weekly amounts using a planner and calculator on a pastel pink highlighted background.

Saving $10,000 becomes much less stressful when you stop looking at the big numbers and instead break it into small pieces that feel completely doable on a day-to-day basis. If you divide $10,000 by 12 months, it comes to around $834 every month, and when you break that down even further, it becomes roughly $192 a week. 

Suddenly, the goal feels more realistic because you know exactly what you need to save each week instead of waiting for the end of the month and hoping for the best. This structure helps you stay organized and prevents overspending because each week has a purpose. 

Follow a Weekly Cash Envelope System

Using a weekly cash envelope system is one of the simplest and most old-school methods, yet it works beautifully because it forces you to become more intentional with your spending. You simply label different envelopes for things like groceries, transport, eating out, and fun money, and you only spend the cash you have placed in each one for that week. 

Once the envelope is empty, that category closes for the week and whatever cash remains in the envelopes at the end of the week can be redirected straight into your $10,000 savings challenge, making saving feel natural rather than forced. 

Try the No-Spend Week Challenge Each Month

Illustration showing a no-spend week calendar with crossed-out non-essential items and a growing savings jar on a pastel pink background.

A no-spend week each month may sound intimidating at first, but it’s actually a freeing experience because it helps you pause your spending habits and reset your financial mindset. During a no-spend week, you only pay for true essentials like bills or urgent needs, and everything else such as online shopping, dining out, and random impulse buys, comes to a temporary stop. 

This challenge doesn’t just save money, it improves self-control and helps you notice how often you spend out of boredom or convenience. The money you would have spent during that week can go directly into your savings challenge and give it a big boost. Over the year, doing this just once a month can save hundreds or even thousands without feeling like you’re making major sacrifices.

Use the 100-Envelope or 120-Envelope Variation for $10k

The envelope challenge is extremely popular because it turns saving into a fun little game that feels motivating every single day. For the $10,000 goal, you can use a 100-envelope or 120-envelope version where each envelope has a number written on it, and you save the amount written on the envelope you pick. 

To reach $10k, you can label envelopes from 1 to 120 or adjust the amounts so they add up to the yearly target. Every time you fill an envelope, you feel a little sense of achievement because it’s visible progress you can literally hold in your hands. By the end, you see a pile of filled envelopes representing your hard work, making the challenge both emotional and exciting.

Cut Hidden Expenses and Redirect the Savings

There are so many hidden expenses in our daily routines such as subscription renewals, delivery charges, unused memberships, small convenience purchases, and random shopping that doesn’t even make us happy. When you sit down and look closely at your bank statements, you’ll often find expenses that can easily be reduced or completely removed. 

Cutting even a few of these can save you $50 to $150 every month, which adds up significantly over a year. Instead of letting that money disappear without purpose, redirect it straight into your $10,000 challenge. This way, you’re not restricting yourself, you’re simply giving unwanted expenses a new home where they actually benefit your goals. It’s such a relief to see your money being used intentionally instead of slipping away unnoticed.

Automate Transfers to a High-Yield Savings Account

Automation is one of the most powerful tools when it comes to saving because it takes emotions, hesitation, and forgetfulness out of the equation. By setting up automatic weekly or monthly transfers into a high-yield savings account, you make saving happen quietly in the background without needing to rely on willpower. 

A high-yield account also gives you extra interest, meaning your money grows even while you’re asleep. You can choose a frequency that matches your pay cycle such as weekly, bi-weekly, or monthly, and treat the transfer like a non-negotiable bill you pay to your future self. Over time, automation creates consistency, which is exactly what helps you reach a big goal like $10,000. 

Adopt the Round-Up and Top-Up Savings Method

The round-up method is one of the easiest ways to save without even noticing it because it uses tiny amounts that quickly add up over time. Every time you make a purchase, you round the transaction to the nearest dollar or nearest $5 and move the extra amount to your savings. 

For example, if you spend $7.30, you can round it to $8 or $10, and the difference goes straight to your challenge. You can even set a weekly “top-up” where you add an extra $5, $10, or $20 just to keep the momentum going. These little amounts may seem small, but they build a habit that makes saving feel effortless. By the end of the year, these micro-savings can contribute a huge portion of your $10,000 goal.

Use a Bonus, Tax Refund, or Extra Income Boost

If you receive any extra money throughout the year whether it’s a bonus from work, a small raise, a tax refund, or unexpected gift money, it can become a huge accelerator for your $10,000 challenge. Instead of spending it right away, redirecting even half of it into your savings can give you a big jump forward. 

This approach helps reduce the pressure on your monthly budget and allows you to reach your goal much faster. Extra income like overtime, commission, freelance work, or seasonal jobs can also be set aside specifically for this challenge. You don’t have to sacrifice your entire earning boost, just committing a portion of it can make the journey smoother and less stressful.

Sell Unused Items and Declutter Monthly

You’d be surprised at how much money is sitting around your home in the form of unused clothes, old gadgets, books, toys, decor pieces, and items you no longer love or need. Setting a goal to declutter once every month not only creates a more peaceful and organized living space but also gives you the opportunity to earn money through selling these items online or to local buyers. 

The money you earn goes directly into your $10,000 challenge, making your home cleaner while also supporting your financial goals. It’s a refreshing feeling to let go of things that no longer serve you and convert them into something meaningful.

Pair the Challenge With a Side Hustle

Adding even a small side hustle can make a massive difference when you’re trying to reach a big savings goal because it takes pressure off your main income and gives you an entirely separate stream dedicated to saving. This side hustle could be anything you enjoy such as online writing, tutoring, baking, selling crafts, running errands, babysitting, or even freelancing skills you already have. 

You don’t need to make hundreds every week, even earning an extra $50 to $100 consistently can speed up your progress more than you expect. When you know this extra income is solely for your $10,000 challenge, it feels exciting and purposeful. You’re not just saving, you’re growing your ability to earn and becoming more self-reliant.

Track Your Progress With a Visual Savings Chart

A visual savings tracker is surprisingly motivating because it turns your financial goal into something you can actually see. You can draw a thermometer chart, color-coded boxes, or use a printable sheet where each section represents a specific amount like $100 or $200. Every time you save, you fill in a part of the chart, and watching it slowly get completed gives you a wonderful sense of accomplishment. 

Conclusion

Saving $10,000 in one year is a big achievement, but when broken down into small steps and paired with simple, consistent habits, it becomes something completely manageable. Each strategy above helps you stay focused and motivated, whether through cutting expenses, earning extra income, organizing your money, or using fun challenges to stay on track. As the months pass, you’ll not only see your savings grow but also feel more confident, disciplined, and proud of yourself. By the end of the year, you’ll realize that saving $10,000 wasn’t just about the money, it was about creating a healthier relationship with your finances and proving you can achieve anything with patience and commitment.


Most Effective Saving Challenge For Car

December 7, 2025 By Ana Rose

Saving for a car can feel like one of those adulting goals that’s both exciting and slightly overwhelming. You know exactly why you want the car whether it’s convenience, freedom, comfort, but figuring out how to stack enough money without feeling broke is where the real challenge begins and that’s where saving challenges come in. They turn a long-term, scary financial goal into small, manageable steps that build confidence and momentum along the way. Instead of squeezing your budget till you’re stressed, these challenges help you save intentionally, consistently, and in a way that feels rewarding rather than exhausting. When you’re working toward something as big as a car, the right challenge can make all the difference, whether you’re saving slowly and steadily or aggressively aiming to get the keys as soon as possible.

Most effective saving challenge for car

The 52-Week Car Savings Challenge

The 52-week challenge is one of the easiest ways to save for a car because it grows at a gentle pace that doesn’t shock your budget. You begin with a small weekly amount, something light like $10 or $20 and slowly increase it week by week. The magic is that it feels almost effortless in the beginning, so you stay motivated instead of feeling pressured.

As the weekly deposits grow, your confidence grows with them, and watching your car fund build becomes strangely addictive. By the end of 52 weeks, you’ve accumulated a surprisingly large amount without feeling deprived. It’s perfect for anyone who wants structure, routine, and a smooth, stress-free saving experience.

The Reverse 52-Week Challenge

Illustration of a person adding large bills into a car fund jar with a calendar showing decreasing weekly amounts on a pastel pink background.

If you want fast progress in the beginning, the reverse 52-week challenge is perfect. Instead of starting with small deposits, you begin with the highest amount you can commit to in week one, for example $52, $60, or $100, and then gradually decrease it week by week. This helps you hit big savings early on, creating a strong financial cushion for your car fund. 

As the weeks go by, the challenge becomes easier, not harder, which makes it psychologically rewarding. You feel lighter with time while still moving toward your goal. This method is especially helpful if you have extra income now, expect future expenses, or simply want to reach your target way faster.

The Bi-Weekly Paycheck Challenge

This challenge fits beautifully into the rhythm of your income if you get paid every two weeks, and you simply decide on a fixed amount to save per paycheck, maybe $100, $150, or any amount that feels doable. Then you automate it so the money moves into your car fund the moment your pay hits. You never feel the stress of calculating weekly deposits or wondering how much to save next. 

Savings become a routine part of your financial life, just like bills or groceries, but without the emotional weight. Over the months, those bi-weekly contributions grow quietly, giving you consistent progress without the overwhelm. It’s ideal for people who prefer stability, predictability, and low-stress saving.

The $5 or $10 Bill Savings Challenge

This challenge is perfect for people who love simple, low-pressure ways to save money. You pick a denomination such as $5 bills, $10 bills, or even $20 bills and every time one enters your wallet, you immediately save it. There’s no schedule, no calculation, and no rigid rules. It blends effortlessly into your daily life, especially if you use cash frequently. 

What makes it effective is the element of surprise as you don’t realize how much you’re saving until you look at the pile after a few weeks or months. It’s fun, effortless, and psychologically satisfying because you’re saving without feeling restricted. Over time, these little bills add up beautifully toward your dream car.

The No-Spend Weekends Challenge

Weekends are when spending quietly spirals such as takeout, outings, impulsive shopping, coffee runs, small treats and that’s why the no-spend weekend challenge works so well. You commit to two or even four weekends a month where you intentionally spend nothing on non-essentials. 

You replace expensive plans with cozy, enjoyable activities at home like cooking, movie nights, journaling, deep cleaning, skincare sessions, or catching up on rest. At the end of each no-spend weekend, you transfer the money you would have spent into your car fund. These savings add up shockingly fast because weekends usually contain the highest impulse spending. It’s an easy, short-term sacrifice that creates long-term progress without making you feel deprived.

The Spare Change Round-Up Challenge

If you want a savings method that works quietly in the background, the round-up challenge is perfect. Every time you make a purchase, you round up the amount to the nearest dollar and save the spare change. Many banking apps automate this, but you can also do it manually by transferring the difference daily or weekly. 

It feels so small that you barely notice it, a few cents here, a couple of dollars there but over time, it becomes a consistent and meaningful contribution to your car fund. This challenge is effortless, stress-free, and perfect for anyone who struggles with strict budgeting. The small amounts accumulate quickly, turning your spare change into your future car.

The 100-Envelope Car Challenge

Illustration of a person selecting a numbered envelope from a spread of 100 envelopes with a small toy car on a pastel pink highlighted background.

The 100-envelope challenge is fun, flexible, and surprisingly powerful. You take 100 envelopes and label them from 1 to 100. Each day or each week, you randomly pick an envelope and save the amount written on it. The randomness keeps the challenge exciting, and the variation allows you to adjust according to your weekly financial comfort.

On good weeks, you can pick two envelopes and on tight weeks, you can pick smaller numbers. By the end, you’ll have saved up to $5,050, a solid step toward a car down payment. It mixes structure with freedom and gives you a sense of adventure while you save. 

The 3-Month Rapid Savings Challenge

If you want to get your car fast and don’t mind a little intensity, this challenge is your best friend. You set a strict, ambitious target for three months, something like $600, $800, or even $1,000 per month depending on your income and lifestyle. Then you commit to prioritizing this goal fully for just 90 days. 

It’s short, sharp, and focused and you cut unnecessary spending, pause luxuries, and choose purposeful habits that support your saving goal. The beauty of this challenge is that it’s temporary, you know it won’t last forever, so it doesn’t feel draining yet the money you save in three months can dramatically fast-track your car purchase timeline.

The Subscription Detox Challenge

Subscriptions are silent money-eaters whether it’s streaming services, apps, gym memberships, premium plans, all renewing quietly every month. This challenge forces you to examine all your subscriptions and cancel at least two to four that you don’t genuinely use or need. 

Then, instead of letting that money disappear, you can transfer it directly to your car fund every single month. You’re not earning more or spending less, you’re simply redirecting money that was already leaking away. It’s a low-effort, high-impact challenge because it tackles expenses you’ve stopped noticing. Over time, those monthly savings build up steadily, adding hundreds or even thousands toward your car without any extra effort.

The Sinking Fund Challenge

A sinking fund is a dedicated savings pocket created specifically for your car, and this challenge is all about consistent, intentional saving. You pick an amount that you can commit to weekly or monthly, even if it’s small, and deposit it regularly into a separate account. 

The key is discipline, you don’t touch this fund for any other purpose and over time, the money grows steadily, and because it’s separate from your main account, you’re less likely to dip into it. This challenge encourages steady progress rather than dramatic cuts, making it ideal for people who want slow, reliable growth. 

The “Cut One Major Expense” Challenge

This challenge is highly effective because it targets one significant expense that takes a noticeable chunk of your income. It could be eating out, online shopping, salon appointments, takeaway coffees, or premium services. You choose one category to reduce or eliminate for three to six months and transfer all the money you would’ve spent on it into your car fund. 

The Side-Hustle Savings Challenge 

If you want to reach your car goal much faster, this challenge can be a complete game-changer. You pick a small side hustle whether it’s tutoring, freelancing, selling items, baking, content creation, or anything you’re good at, and commit to saving every single dollar you earn from it. 

Because it’s money outside your normal income, saving it doesn’t hurt your existing budget or lifestyle. Over a few months, even a small side hustle can add thousands to your car fund. 

Conclusion

Saving for a car doesn’t have to feel overwhelming or impossible, the right challenge can completely change your experience. Whether you prefer slow and steady progress, fast and focused saving, or fun, low-pressure methods, there’s a challenge that fits your lifestyle and personality. As your savings grow, so does your confidence, and the excitement of getting closer to your car becomes its own motivation. With intention, patience, and the right saving strategy, that moment of driving your own car is truly within reach.

Achieve $5000 From This Saving Challenge For Vacation

December 6, 2025 By Ana Rose

Saving $10,000 in a single year might feel overwhelming at first, but it becomes much more achievable once you break it down into smaller and manageable steps. A saving challenge adds discipline and direction to your financial journey, making it easy for you to stay consistent and save in an effective way. Whether you’re saving for an emergency fund, a new car, travel, or simply building long-term financial stability, committing to this challenge can be life-changing. With the right strategies, consistency, and a little creativity, you can reach your goal without feeling deprived or stressed. This article will help you explore some powerful methods you can mix, match, or follow together to successfully save $10,000 in 12 months.

Achieve $5000 From This Saving Challenge For Vacation

Break Down the $10,000 Goal Into Monthly and Weekly Targets

Saving $10,000 becomes much less stressful when you stop looking at the big numbers and instead break it into small pieces that feel completely doable on a day-to-day basis. If you divide $10,000 by 12 months, it comes to around $834 every month, and when you break that down even further, it becomes roughly $192 a week. 

Suddenly, the goal feels more realistic because you know exactly what you need to save each week instead of waiting for the end of the month and hoping for the best. This structure helps you stay organized and prevents overspending because each week has a purpose. 

Follow a Weekly Cash Envelope System

Illustration of labeled cash envelopes with a person placing leftover cash into a savings jar, set on a pastel pink highlighted background.

Using a weekly cash envelope system is one of the simplest and most old-school methods, yet it works beautifully because it forces you to become more intentional with your spending. You simply label different envelopes for things like groceries, transport, eating out, and fun money, and you only spend the cash you have placed in each one for that week. 

Once the envelope is empty, that category closes for the week and whatever cash remains in the envelopes at the end of the week can be redirected straight into your $10,000 savings challenge, making saving feel natural rather than forced. 

Try the No-Spend Week Challenge Each Month

A no-spend week each month may sound intimidating at first, but it’s actually a freeing experience because it helps you pause your spending habits and reset your financial mindset. During a no-spend week, you only pay for true essentials like bills or urgent needs, and everything else such as online shopping, dining out, and random impulse buys, comes to a temporary stop. 

This challenge doesn’t just save money, it improves self-control and helps you notice how often you spend out of boredom or convenience. The money you would have spent during that week can go directly into your savings challenge and give it a big boost. Over the year, doing this just once a month can save hundreds or even thousands without feeling like you’re making major sacrifices.

Use the 100-Envelope or 120-Envelope Variation for $10k

The envelope challenge is extremely popular because it turns saving into a fun little game that feels motivating every single day. For the $10,000 goal, you can use a 100-envelope or 120-envelope version where each envelope has a number written on it, and you save the amount written on the envelope you pick. 

To reach $10k, you can label envelopes from 1 to 120 or adjust the amounts so they add up to the yearly target. Every time you fill an envelope, you feel a little sense of achievement because it’s visible progress you can literally hold in your hands. By the end, you see a pile of filled envelopes representing your hard work, making the challenge both emotional and exciting.

Cut Hidden Expenses and Redirect the Savings

There are so many hidden expenses in our daily routines such as subscription renewals, delivery charges, unused memberships, small convenience purchases, and random shopping that doesn’t even make us happy. When you sit down and look closely at your bank statements, you’ll often find expenses that can easily be reduced or completely removed. 

Cutting even a few of these can save you $50 to $150 every month, which adds up significantly over a year. Instead of letting that money disappear without purpose, redirect it straight into your $10,000 challenge. This way, you’re not restricting yourself, you’re simply giving unwanted expenses a new home where they actually benefit your goals. It’s such a relief to see your money being used intentionally instead of slipping away unnoticed.

Automate Transfers to a High-Yield Savings Account

Automation is one of the most powerful tools when it comes to saving because it takes emotions, hesitation, and forgetfulness out of the equation. By setting up automatic weekly or monthly transfers into a high-yield savings account, you make saving happen quietly in the background without needing to rely on willpower. 

A high-yield account also gives you extra interest, meaning your money grows even while you’re asleep. You can choose a frequency that matches your pay cycle such as weekly, bi-weekly, or monthly, and treat the transfer like a non-negotiable bill you pay to your future self. Over time, automation creates consistency, which is exactly what helps you reach a big goal like $10,000. 

Adopt the Round-Up and Top-Up Savings Method

The round-up method is one of the easiest ways to save without even noticing it because it uses tiny amounts that quickly add up over time. Every time you make a purchase, you round the transaction to the nearest dollar or nearest $5 and move the extra amount to your savings. 

For example, if you spend $7.30, you can round it to $8 or $10, and the difference goes straight to your challenge. You can even set a weekly “top-up” where you add an extra $5, $10, or $20 just to keep the momentum going. These little amounts may seem small, but they build a habit that makes saving feel effortless. By the end of the year, these micro-savings can contribute a huge portion of your $10,000 goal.

Use a Bonus, Tax Refund, or Extra Income Boost

If you receive any extra money throughout the year whether it’s a bonus from work, a small raise, a tax refund, or unexpected gift money, it can become a huge accelerator for your $10,000 challenge. Instead of spending it right away, redirecting even half of it into your savings can give you a big jump forward. 

This approach helps reduce the pressure on your monthly budget and allows you to reach your goal much faster. Extra income like overtime, commission, freelance work, or seasonal jobs can also be set aside specifically for this challenge. You don’t have to sacrifice your entire earning boost, just committing a portion of it can make the journey smoother and less stressful.

Sell Unused Items and Declutter Monthly

You’d be surprised at how much money is sitting around your home in the form of unused clothes, old gadgets, books, toys, decor pieces, and items you no longer love or need. Setting a goal to declutter once every month not only creates a more peaceful and organized living space but also gives you the opportunity to earn money through selling these items online or to local buyers. 

The money you earn goes directly into your $10,000 challenge, making your home cleaner while also supporting your financial goals. It’s a refreshing feeling to let go of things that no longer serve you and convert them into something meaningful.

Pair the Challenge With a Side Hustle

Adding even a small side hustle can make a massive difference when you’re trying to reach a big savings goal because it takes pressure off your main income and gives you an entirely separate stream dedicated to saving. This side hustle could be anything you enjoy such as online writing, tutoring, baking, selling crafts, running errands, babysitting, or even freelancing skills you already have. 

You don’t need to make hundreds every week, even earning an extra $50 to $100 consistently can speed up your progress more than you expect. When you know this extra income is solely for your $10,000 challenge, it feels exciting and purposeful. You’re not just saving, you’re growing your ability to earn and becoming more self-reliant.

Track Your Progress With a Visual Savings Chart

Illustration of a woman filling in a savings thermometer chart toward a 10,000 goal, on a pastel pink background with highlights.

A visual savings tracker is surprisingly motivating because it turns your financial goal into something you can actually see. You can draw a thermometer chart, color-coded boxes, or use a printable sheet where each section represents a specific amount like $100 or $200. Every time you save, you fill in a part of the chart, and watching it slowly get completed gives you a wonderful sense of accomplishment. 

Conclusion

Saving $10,000 in one year is a big achievement, but when broken down into small steps and paired with simple, consistent habits, it becomes something completely manageable. Each strategy above helps you stay focused and motivated, whether through cutting expenses, earning extra income, organizing your money, or using fun challenges to stay on track. As the months pass, you’ll not only see your savings grow but also feel more confident, disciplined, and proud of yourself. By the end of the year, you’ll realize that saving $10,000 wasn’t just about the money, it was about creating a healthier relationship with your finances and proving you can achieve anything with patience and commitment.


  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 17
  • Go to page 18
  • Go to page 19
  • Go to page 20
  • Go to page 21
  • Interim pages omitted …
  • Go to page 73
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers