• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

Blog

The Perfect Bi-weekly Savings Challenge

September 30, 2025 By Ana Rose

Saving money can often become overwhelming especially when you’re dealing with bills, unexpected expenses, and those little urges to spend on things and activities you enjoy. Many people struggle with monthly savings plans because they become too strict to follow, whereas weekly challenges may feel too frequent to manage, and that’s exactly where biweekly challenges come in. For a flexible, realistic, and perfectly in sync with how many people receive their paycheck, you can consider the option of saving biweekly instead of monthly or weekly. This article will help you explore the dynamics of biweekly savings challenges, ensuring that savings doesn’t feel like a burden but rather a habit that grows naturally over time. 

The Perfect Bi-weekly Savings Challenge Graphic

What is the Bi-Weekly Savings Challenge?

The biweekly savings challenge is a simple yet powerful strategy to help your savings grow. Instead of saving every week or waiting for the month to end, this strategy strikes the perfect balance between comfort and consistency. This means you get to set aside money 26 times in a year, making the challenge feel more manageable while allowing your savings to grow steadily. 

This challenge usually involves setting aside small amounts consistently, for instance, you might start with $20 in the first two weeks, $40 in the next, and so on and by the end of the challenge you may get to see your small savings adding up to a surprisingly large amount. 

Why Choose Bi-Weekly Over Weekly or Monthly Plans?

Many people may find it hard to set aside money weekly because life can get busy and weekly challenges may require you to remember setting money aside, almost like a chore. On the other hand, monthly challenges at times, may feel too distant which can make it easy to lose track of the progress or difficult to maintain motivation and consistency to go on with the challenge. 

However, the biweekly challenge sits perfectly in the middle as it’s frequent enough to maintain consistency and spaced out enough to feel less overwhelmed by the whole process, making it a considerable option if you’re looking to save money in an effective manner. 

How the Classic Bi-Weekly Method Works

The classic biweekly saving method is simple and straightforward which involves beginning with a small amount and gradually increasing it as you move on with the challenge. For example, you can start with $20 in the first 2 weeks of the challenge, $30 in the next, $40 in the next, and so on. 

This method helps in keeping the challenge as simple and easy as it can be by letting you start small and pace up the process as you become conditioned to setting an amount aside every two weeks. The beauty of this method is in its simplicity as it requires little thought, and yet by the end of 26 deposits, you’ll have built a savings fund that feels like it happened naturally, without harsh sacrifices.

The Reverse Bi-Weekly Savings Challenge

Illustration of a savings jar filling with cash, with larger bills going in first and smaller ones later, symbolizing the reverse biweekly savings challenge, on a pastel pink background.

Another way to approach this method is through the reverse biweekly savings challenge which involves starting with the highest amount in the beginning of the challenge and gradually moving toward the smallest amount. For example, you may begin to save $100 in the first 2 weeks, $90 in the next, and so on. 

What makes this method considerable is that it takes away the stress of sticking to the method by allowing yourself to complete the hardest part first, making it convenient to complete the easy bits of the challenge later on. 

Flexible Bi-Weekly Pick-and-Save Method

For those who prefer an easy, flexible, and convenient approach, consider going with the flexible biweekly savings challenge. Instead of following a strict and organized order, create a chart with different amounts written on it from $10- $100, and every two weeks, choose the amount that suits you the best at the moment. 

Whether you had an unexpected car repair and can only set aside $15, or you received some extra cash and can comfortably put away $70, this method gives you control and freedom while still ensuring you stay on track overall. By the end of the year, you’ll still hit your savings target, but without the stress of sticking to a strict pattern.

Setting Clear Financial Goals Before Starting

Before you start with the challenge, it’s important to pause and reflect on what your financial goals and targets are. Having a clear goal can help you add a personalized touch to the savings challenge, making it easy for you to stick with the process and turn it into a meaningful journey. 

Whether you’re planning for a big purchase, have a trip planned out, or simply want to build an emergency fund in case of unexpected expenses, having something to work for can make the challenge feel less of a chore and more of something that excites or protects you in the future. 

Automating Your Bi-Weekly Transfers

One of the easiest ways to guarantee success with this challenge is to remove the temptation to spend your hard earned money. By automating your biweekly transfers you can easily watch  your savings grow without having to rely on willpower or memory every two weeks.

Set up an automatic transfer from your checking account to a separate savings account the same day your paycheck arrives. The key is to let your savings grow in a separate yet easily accessible savings account that provides a quiet space for your money to grow without any drama or distractions.

Using Visual Trackers to Stay Motivated

Pastel pink chart with colorful progress bars and checkmarks, showing a savings tracker with boxes being filled in, representing motivation in the biweekly savings challenge.

The concept of saving money can feel a little abstract when there’s nothing to track the progress. Whether it’s a colorful savings chart you fill in every two weeks, a jar where you drop cash envelopes, or even a digital app that shows your progress like a progress bar, having something you can see makes the journey feel much more real. 

Each time you color in a box or tick off a milestone, you can feel a sense of motivation and pride kicking in. Visual cues turn your savings journey into something interactive and fun, helping you stay focused when motivation naturally starts to fade.

Fun Variations to Keep Things Exciting

Sometimes saving money can feel repetitive, and when that happens, it’s easy to lose interest. To make the biweekly savings challenge more enjoyable, try adding fun variations, for example, roll a dice every two weeks and save the number you land on times ten, or create a “savings jar challenge” where each family member picks an amount to save from a jar of slips. 

You could even tie the savings to small personal achievements, like saving an extra $10 every time you cook at home instead of ordering takeout. These little twists keep the process lighthearted and prevent it from feeling boring, making saving money something you actually look forward to.

How to Recover from Missed Savings Weeks

Life isn’t perfect, and sometimes you may miss a savings week because of an unexpected bill or expense. Instead of feeling guilty or giving up, remember that the challenge is about progress, not perfection. 

You can catch up by spreading the missed amount over the next couple of deposits, or if that feels too tight, simply add a little extra whenever you can. The important thing is to keep going, even if it’s not flawless. Missing one or two weeks won’t ruin your success, it’s your commitment to coming back that truly makes the difference.

Making it a Family or Couple Activity

Saving doesn’t have to be a solo thing, it can be even more fun when you share it with your family or partner. If you’re doing this as a family, you can encourage kids to participate with small contributions or have weekly check-ins where everyone shares how the challenge is going. 

Couples can also use it as a way to strengthen teamwork and work toward shared goals, like saving for a trip or a new home. By involving loved ones, the challenge becomes more than just about money, it becomes a bonding activity that teaches responsibility, teamwork, and patience.

Celebrating Milestones Along the Way

Saving money is a long journey, and celebrating the little wins makes it easier to keep going. For every $200 or $500 you save, allow yourself to enjoy a no-cost or low-cost reward, like a movie night at home, a long walk in the park, or cooking your favorite meal. 

These small celebrations give you something to look forward to and remind you how far you’ve come. Instead of only waiting for the final amount, marking milestones helps you stay positive and motivated all the way through the challenge.

What to Do with the Money Once Saved 

By the end of the challenge, you’ll likely have a nice sum saved up, and this is where planning matters most. Instead of letting it sit without purpose, or worse, spending it all in one go, decide beforehand what you want to do with it. 

Maybe you’ll use it to build an emergency fund, pay down debt, or put it toward a big goal like a vacation or new furniture. Having a plan for the money ensures your effort pays off in a way that really benefits your life and financial health.

Conclusion

The biweekly savings challenge is more than just a strategy, it’s a mindset shift that helps you build consistency and discipline while making saving money feel easier and more natural. Unlike weekly or monthly challenges, it strikes a perfect balance that fits comfortably into most people’s lives, giving you enough structure to stay on track without feeling overwhelmed. Each step, each deposit, no matter how small, brings you closer to financial security and peace of mind and when you finally reach the end of the challenge, you’ll not only have a healthy savings fund but also stronger habits that can carry you into a future filled with financial confidence.
52 Week Easiest Money Saving Challenge

September 29, 2025 By Ana Rose

Saving money often feels overwhelming, especially if you think it requires big sacrifices or holding back on fun or activities you enjoy doing. Building savings doesn’t have to be difficult, it’s about consistency and small steps that add up over time. The 52-weeks savings challenge is one of the simplest yet effective challenges that helps you grow your savings gradually, taking off the pressure and allowing you to focus on the progress rather than being perfect. This article will help you explore the 52-week challenge, offering strategies, tips, and motivation to stick to the challenge through every ups and downs. 

52 Week Easiest Money Saving Challenge  Graphic

What is the 52-Week Money Saving Challenge?

At its core, the 52-week challenge is a simple yet highly effective challenge in which you have to save a specific amount each week for at least a 52 week duration. The classic method of this challenge involves starting with the lowest amount for the first week which is $1, $2 for week 2, $3 for week 3, and so on to $52 in week 52. 

At the end of the challenge, you’ll have saved a total of $1378 without having it feel like a burden. What makes this challenge appealing is the fact that it starts with you collecting small amounts in the beginning, helping you build motivation to go on with the process. 

Why the 52-Week Challenge Works

The beauty of the 52-week challenge lies in its simplicity and psychological appeal because many people think saving comes with its own challenges and sacrifices, but this challenge offers an easy approach where it starts so small that it’s almost effortless and unnoticeable.

When you save $1 in the first week, the rest of the journey becomes doable or easy to follow. By the time you’ve reached putting away $40-$50 each week, you’ve already built a pattern to promote healthy saving habits. Another reason it works is the sense of accomplishment you feel along the way where every week is a small win that motivates you to keep going

How to Get Started

Starting with the 52-week challenge doesn’t require anything complicated, you just need a plan and a safe and quiet space for your savings to grow without any drama or distraction. Firstly, you need to decide whether you want your savings to grow in the form of cash or transfer the money to a separate savings account. If you prefer to go with online banking, a smart way to approach this would be to automate transfers so the process becomes easier and it also takes away the stress of having to rely on your own willpower to move the money. 

You can then pick the version of the challenge you want to follow, whether classic, reverse, or flexible, the key is to stick to the challenge and commit to saving an amount each week. 

The Classic Version

A savings jar labeled “52-Week Challenge” filled with dollar bills and coins, surrounded by neatly stacked money. The jar shows numbers from 1 to 52, symbolizing steady weekly savings. The scene is set against a pastel pink background with soft highlights.

For a simple and straightforward option, you can go with the classic 52 week challenge which involves setting aside $1 in week 1, $2 in week 2, $3 in week 3, and so on to $52 in week 52. At the end of the year, you’ll have saved an amount of $1378 without having it feel like a demanding task. 

The early weeks are easy and build your pace for the rest of the challenge, while the later weeks feel like a natural step up because you’ve adjusted along the way. This method is especially great for beginners who might feel intimidated by saving large amounts. The structure is simple, predictable, and doesn’t require much thought, making it one of the easiest ways to build savings with discipline and confidence.

The Reverse 52-Week Challenge

The reverse 52-week challenge flips the script of the classic method and involves beginning with the largest amount and gradually moving to the smaller ones. You begin by saving $52 in week 1, $51 in week 2, $50 in week 3, and so on to $1 to week 52. This approach works the best for people who become motivated at the beginning of the challenge and when the process loses its spark, it’s easier to keep up with it as the amount to be saved gradually lowers. 

While it might feel more challenging at the start, by the time you’re saving smaller amounts, it feels like a breeze, making it a smart alternative for many.

The Flexible Pick-and-Choose Method

For those who fear away from the concept of sticking to a strict schedule and prefer a flexible approach, this method may suit you best. Instead of moving in a structured and organized way, you can create a chart with all amounts, from $1-$52, written on it. Each week, you get to decide what you can realistically set aside. For instance, if money feels tight, maybe you choose $7 that week, but if you have extra cash, you might set aside $40 and by the end of the year, you’ll still have $1,378 saved, but without feeling restricted. This method offers you freedom and convenience while still holding you accountable for the choices you make. 

Automating Your Weekly Savings

One of the easiest ways to make the 52-week challenge foolproof is through automating your weekly savings. Instead of relying on willpower to remember each week, you can set up automatic transfers from your checking account to your savings account on a weekly basis.

Many banks or financial apps allow you to schedule recurring transfers, which means once it’s set up, the savings happen without you having to think about it. This method removes the temptation of skipping a week or spending the money elsewhere and also gives you consistency, which is the key to building habits. Over the year, these small, effortless, and automatic amounts add up to something significant, and because it requires little effort, it’s one of the most reliable ways to succeed with this challenge.

Adding a Fun Twist

A playful piggy bank surrounded by dice, numbered slips of paper, and small pieces of confetti, representing a gamified approach to saving money. The pastel pink background with bright highlights adds a cheerful, fun vibe.

Saving money doesn’t always have to feel serious or boring, in fact, adding a little creativity to the 52-week challenge can make it much easier to stick with and far more enjoyable along the way. You could gamify the process by rolling dice to decide your weekly savings amount, drawing slips of paper from a jar with numbers written on them, or even linking your savings to personal milestones, such as saving an extra $5 every time you hit the gym or cook a meal at home instead of eating out. 

By making the challenge interactive and fun, you’re more likely to look forward to each week instead of seeing it as another financial task.

Using the Challenge for a Specific Goal

While the 52-week challenge works perfectly just to grow a general savings cushion, it often feels more motivating if you tie it to a specific purpose that excites you. Whether it’s saving for a vacation you’ve always dreamed of, building a holiday fund so the end-of-year expenses don’t feel overwhelming, or working toward a big milestone like a wedding or a new gadget you’ve had your eye on, when you connect your savings to something meaningful, each weekly contribution feels less like money leaving your hands and more like an investment into a future moment of joy or security. 

Tracking Your Progress Visually

One of the most powerful ways to stay motivated through the 52-week challenge is by tracking your progress in a way you can actually see, because watching your savings grow week by week gives you a real sense of accomplishment. 

You can create a printable chart where you color in each week’s savings box, use a jar where you drop in slips of paper labeled with the amounts saved, or simply update a savings app that shows your growing balance in real time. These little visual cues act as reminders that even small amounts add up and that you’re moving forward, even if some weeks feel slow or difficult. 

How to Handle Setbacks

No savings journey is perfect, and that’s absolutely okay because life happens and sometimes you may miss a week or find yourself dipping into the money you’ve already saved. The key is not to let one setback discourage you or make you quit the challenge altogether. 

If you miss a week, you can always double up the next time or adjust the amounts slightly to catch up. Remember that this challenge is meant to help you build better habits, not to make you feel guilty or pressured. 

Making the Challenge a Family Activity

Turning the 52-week challenge into a family activity can not only make saving more fun but also teach children valuable lessons about money from an early age. You could create a savings jar that everyone contributes to each week, letting kids drop in coins or small bills while explaining the importance of working together toward a shared goal. 

Families can set fun targets like a weekend getaway, a new board game, or even a home project, making the process something everyone looks forward to rather than just a financial task for the adults. This shared experience not only builds savings but also strengthens bonds, because every family member feels included in the journey. 

Conclusion

The 52-week money saving challenge is proof that big financial changes don’t always come from massive sacrifices, they can come from small, consistent actions taken one week at a time. Whether you choose the classic version, reverse order, or a flexible approach, what matters most is that you commit to showing up each week and keeping your goals in sight. By making the process fun, tying it to something meaningful, and even involving your family, you transform saving from a chore into something you actually enjoy. At the end of the 52 weeks, you’ll not only have built up a meaningful cushion of savings but also developed habits and confidence that will serve you far beyond the challenge itself.

17 Best Savings Strategy Biweekly Ideas

September 28, 2025 By Ana Rose

Saving money can seem difficult when you look at it in terms of big annual goals, but when you break it down in small and more manageable chunks, it becomes much easier to stick with it. That’s exactly why you need a biweekly savings challenge which allows you to save consistently in smaller amounts every two weeks instead of waiting until the end of the month or struggling with one large deposit. This method aligns perfectly well with anyone who gets paid every other week, but even if you don’t, the habit of saving biweekly can help you build momentum and stay committed and consistent with the process. This article will help you explore the 17 best strategies for biweekly savings challenge, helping you develop healthy financial habits that can serve you in the long run. 

17 Best Savings Strategy Biweekly Ideas Graphic

1. Automate Your Biweekly Transfers

One of the easiest and most effective strategies to save is to automate your biweekly transfers so it can take away the stress of deliberately transferring money and makes the savings process easier to carry out. 

Even if it’s as little as $20 or $50, these small amounts can add up quickly over time, helping you save through an effortless yet effective strategy. The key is to set up a separate yet easily accessible savings account that allows your money to grow in peace. 

2. Try the Biweekly 52-Week Challenge

For a simple yet effective strategy to save, go for the biweekly 52-week challenge. Instead of saving weekly, commit to save every two weeks by starting small and staying consistent and committed with the process. 

For example, you might begin with just $10 in your first pay period and add an extra $10 every following two weeks. By the end of the year, you’ll have saved a substantial amount without it feeling overwhelming

3. Split Large Bills into Biweekly Payments

Instead of stressing over big monthly payments, a smart move would be to divide those monthly deposits into small and manageable chunks by splitting the cost into two smaller payments from each paycheck. For instance, if your monthly rent is $800, you can set aside $400 from your first paycheck and $400 from the second one. 

This method can help reduce the pressure of one big deposit and keeps the budget more balanced and manageable. 

4. Round Up and Save the Difference

Illustration of a person at a grocery store checkout rounding up their purchase, with extra coins and small bills being placed into a jar labeled “Round-Up Savings,” on a pastel pink background with highlight accents.

Every time you make a purchase, try to round up your spending to the nearest $5 or $10. For instance, if you spend $43 on groceries, you can round it up to $45 or $50 and save $2 or $7 respectively. 

While it may not feel like much at the moment, over time these tiny amounts can add up quickly over time, helping you save effectively.  

5. Biweekly “No-Spend” Weekend Savings

Aim to pick one weekend every two weeks where you commit to not spend on non-essential spending categories or those extra expenses. This can include no takeouts, no shoppings, no coffee runs, or no subscriptions, helping you make the most of what you already have at home. 

This no spend challenge can help you build creativity and helps you learn that contentment and fulfillment doesn’t always have to come with a price tag. Over time, these small biweekly no spend resets can help you figure out your unhealthy spending patterns, teaching you to enjoy life without spending constantly. 

6. Use the 50/30/20 Rule Biweekly

The 50/30/20 rule isn’t just for monthly budgets, you can break it down biweekly for better control over your money. With each paycheck, allocate 50% toward essentials like rent, bills, and groceries, 30% toward wants like dining out or hobbies, and 20% toward savings or debt repayment. 

Applying this method biweekly makes it easier to track your spending in smaller chunks and keeps you from feeling overwhelmed. It’s a simple yet powerful way to make sure your needs are covered, you enjoy some wants, and you stay consistent with savings every two weeks.

7. Create a Biweekly Emergency Fund Goal

Building an emergency fund may feel less intimidating when you break it down into smaller biweekly targets. Instead of stressing over saving $1,000 or three months of expenses all at once, you can commit to adding a set amount from each paycheck. For example, $40 every two weeks adds up to over $1,000 in a year without feeling like a huge burden. 

By treating your emergency fund like a non-negotiable expense, you slowly build a safety net that will protect you from unexpected bills, job loss, or sudden repairs.

8. Envelope Method Every Two Weeks

To add structure and discipline to your spendings, consider using the envelope method with a biweekly routine. Each payday, put cash into envelopes labeled as food, groceries, gas, rent, or utilities. When the envelope gets empty, that’s your signal to stop spending on that category, helping you prevent overspending. 

9. Biweekly Side Hustle Savings

If you have a side hustle or earn extra income occasionally, make a habit of saving it every two weeks. Whether it’s tutoring, petsitting, babysitting, selling unused items, or putting your freelancing skills to work through freelancing platforms like Fiverr, Upwork, or Freelancer.com, saving these side hustle incomes can help you save effectively over time. 

10. Set a Biweekly Savings Percentage

Instead of saving a fixed amount each paycheck, try a different and flexible approach of committing to save a fixed percentage of your income biweekly. For example, you can commit to saving 15% of your paycheck, no matter how much you earn that week. 

Over time, this percentage-based approach can help you create consistency with the saving process, allowing room for your money to grow. 

11. The Biweekly Reverse Savings Challenge

Instead of slowly building up your savings by starting small and increasing over time, the reverse savings challenge encourages you to flip the process around, putting away a larger amount at the very beginning while your motivation is fresh and your excitement about the challenge is still high. You can gradually lower the amount every two weeks so that it feels easier and lighter as you move forward. 

This approach is great because it gives you that satisfying sense of progress right away and when you see a decent balance in your savings early on, it can feel real and motivating, helping you stay consistent with the process.

12. Match a Small Expense Every Two Weeks

Digital illustration of a person buying coffee while dropping the same amount of money into a smiling piggy bank, symbolizing matching expenses with savings, on a pastel pink background with highlights.

This strategy is simple but surprisingly powerful which involves picking one small expense from your spending every two weeks, whether it’s a coffee date with a friend, a new book, or a dinner out, and match that amount by moving the same number into your savings. What makes this method so motivating is that you don’t have to cut out the things you enjoy.

13. Save Raises or Bonuses Biweekly

When you get a raise or a bonus, the natural urge is to celebrate by upgrading your lifestyle, whether it’s eating out more often, buying new clothes, or planning a trip, but one of the smartest moves you can make is to set that extra money aside biweekly as savings.

This doesn’t mean you can’t enjoy a little of it for something fun, but even saving half of your raise or bonus ensures that you’re steadily building wealth without feeling deprived. Over time, this strategy makes a huge difference, because those extra dollars are quietly growing into a larger amount.

14. Biweekly “Spare Change Sweep”

This one feels like cleaning out your wallet, but for your bank account. At the end of every two weeks, take a quick look at what’s left, maybe it’s $7 in your account or $12 from your grocery budget and move it straight into savings. 

It may seem small but those little amounts add up quickly, plus it gives you a nice feeling of closure before the next paycheck arrives.

15. Try a 1% Savings Increase Biweekly

If saving feels hard, this gentle method can help you ease into it. Start by saving just 1% of your paycheck, something small enough that you hardly notice and then, every few pay periods, bump it up by another 1%. 

For example, if you earn $2,000, that first 1% is only $20 every two weeks. Over time, those tiny increases don’t feel like a sacrifice, but they steadily build a big savings habit. 

16. Debt Repayment as a Savings Strategy

It may not feel like “saving” when you’re paying down debt, but every extra payment is money you’re saving on interest later. By sending a little extra toward your loans or credit card bills every two weeks, you’re freeing up your future paycheck from going to interest. 

17. Celebrate Biweekly Milestones

Saving can sometimes feel slow and a little boring, so don’t forget to celebrate your wins along the way. Whether it’s your first $100, sticking to your budget, or paying off a small debt, it’s important to give yourself a moment to acknowledge it. 

You don’t have to spend money to celebrate, you could treat yourself to a cozy self-care night, write down your progress in a journal, or just share the win with someone you trust. 

Conclusion

At the end of the day, saving money isn’t about making huge sacrifices or cutting out every joy in your life, it’s about building small, consistent habits that make your future a little more secure with every paycheck. Whether you’re automating transfers, trying fun challenges, or simply sweeping your spare change into savings, each little choice is proof that you’re taking control of your financial story. And while the numbers in your account will grow over time, what matters just as much is the confidence and peace of mind you gain along the way.

Budgeting Tips For Saving Money Fast

September 27, 2025 By Ana Rose

When it comes to building financial freedom and security, budgeting can help you transform your financial life. A good budget gives you clarity and direction, reduces stress, and helps you use your money with a more mindful and thoughtful approach instead of wondering where it all went at the end of the month. Whether you’re planning a big future purchase, trying to build an emergency fund, or something as simple as saving money so it can serve you in the future, learning how to budget effectively can transform the way you manage your finances. This article will help you explore some of the most practical budgeting tips to help you save money, stress less, and create a plan that actually works for your life.

Budgeting Tips For Saving Money Fast Graphic

1. Start by Tracking Your Spending

Before you get to budgeting, it is important to track your current spending patterns and habits. Spend at least a month writing down every expense you spent your money on, no matter how small or big, including rent, utilities, medical expenses, transportation, subscriptions, coffee runs, or takeouts. 

You may come to realize that you’re spending way more on those seemingly harmless ’small’ expenses than you thought. By allowing yourself to track the spending, you give yourself a clear picture of where your money is going, giving yourself the opportunity to take action and become more mindful and intentional of what you spend on. 

2. Set Clear Financial Goals

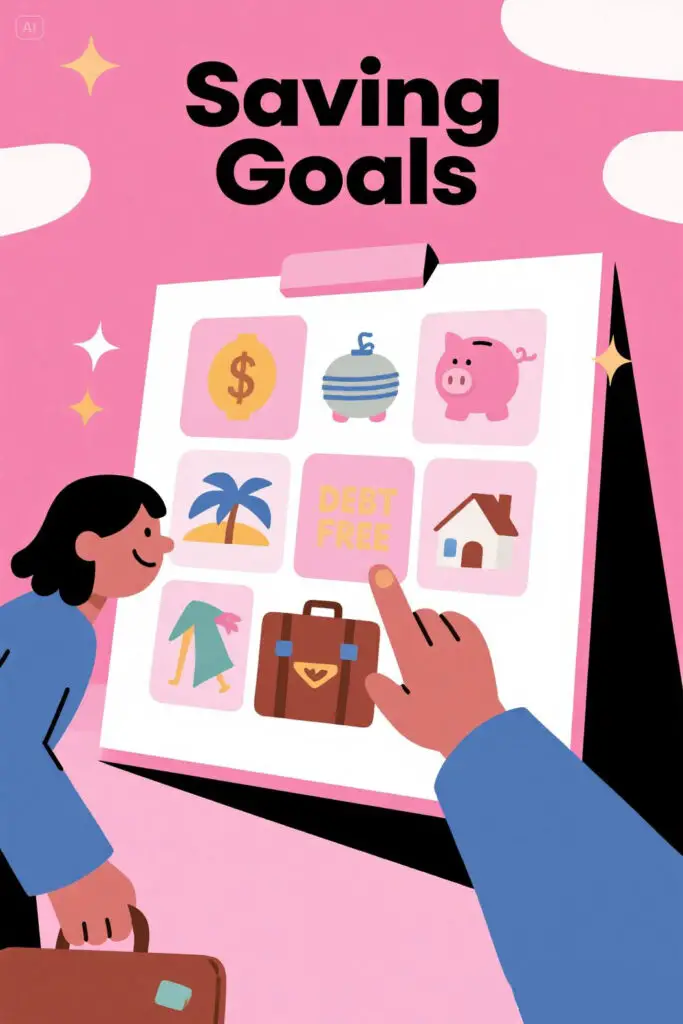
Illustration of a person standing in front of a vision board filled with financial icons like a piggy bank, house, suitcase, and debt-free sign, on a pastel pink background with highlight accents, symbolizing setting clear financial goals.

Another helpful tip is to make the process feel a bit more personalized by associating it with a clear purpose or target. You can ask yourself questions like “What do I want my money to do for me?”, or “Do I have something important coming up that I’d rather use my money for later?”. Asking yourself these can help you reflect on what your future goals and targets are. 

Whether it’s building an emergency fund, paying off credit card debt that feels overwhelming, or saving for a family trip, having a specific and realistic goal can help you become more motivated and consistent to achieve the goal. 

3. Use the 50/30/20 Rule as a Guideline

For a simple yet effective budgeting framework, you can consider the 50/30/20 rule that is all about prioritizing your basic expenses over those extras. The catch of this budgeting method is simple, 50% of your paycheck is spent on basic expenses or anything that falls under ‘needs’ such as rent, groceries, utilities, or gas. 30% of your income is spent on those ‘wants’ such as dining out, subscriptions, shopping, or streaming services. Lastly, 20% of your income goes to savings or paying off debt, if there is any. 

What makes this budgeting method a considerable option is that it makes your finances structured and organized, without being overly strict or cutting back on fun and entertainment.  

4. Prioritize an Emergency Fund

Life has its way of throwing unpredictable surprises when you least expect them, and not all of them are pleasant. Whether it’s a sudden car repair, job loss, or unforeseen medical expenses, it’s essential to have an emergency fund in place so your entire budget isn’t thrown off track when life throws a curveball your way. 

Start small if you need to, aim for $500–$1,000 as a starter goal, and then gradually work your way up to cover three to six months’ worth of essential expenses. Knowing you have that safety net in place not only keeps you financially secure but also reduces stress and gives you peace of mind.

5. Pay Yourself First

One of the smartest budgeting habits is to pay yourself first which means treating your savings like a non-negotiable bill, just like rent or electricity. Instead of waiting until the end of the month to see what’s left, set aside money for savings as soon as you receive your paycheck. 

Even if it’s a small amount, consistently putting money away builds discipline and helps you reach your goals faster. Over time, these contributions add up, and you’ll be surprised at how much you can save when you prioritize your future self first.

6. Cut Back on Non-Essentials Mindfully

Saving money doesn’t mean you have to stop doing everything you enjoy or find comfort in, it just means becoming more thoughtful about where your money goes. Look at your non-essential spending categories, like dining out, streaming subscriptions, or impulse shopping and instead of cutting them out completely, ask yourself which ones bring you the most joy and which ones you barely notice. 

Keep the meaningful ones and try to cut back on the rest. This way, you’re saving money without feeling deprived, making it easier to stick to your budget in the long run.

7. Use Cash for Discretionary Spending

Illustration of a person holding cash and budgeting envelopes labeled “Food,” “Fun,” and “Shopping,” with a wallet full of cash beside unused credit cards, on a pastel pink background with light highlights, representing mindful cash-based spending.

In today’s world of credit cards and online banking, it’s easy to swipe a card or tap your phone without realizing how much you’ve spent. One effective way to manage discretionary spending like entertainment, eating out, or personal treats is to use cash instead of cards, so you can actually feel the money leaving your hands. 

Decide how much you want to spend in a week, withdraw that amount, and use only that cash for your expenses. This simple habit makes you more aware of your choices and helps you stay within the spending limits and avoid impulse buying and overspending. 

8. Review and Cancel Unused Subscriptions

Many people waste money every month on subscriptions they barely use or forgot they have subscribed to. These small and recurring charges like extra streaming platforms, unused gym memberships, or apps can quietly eat away your budget. 

Take a moment to review your bank statements, list all your subscriptions, and ask yourself which ones you actually use regularly and cancel the rest. Even if it’s just $10 or $20 a month, cutting back on these hidden expenses adds up to big savings over the course of a year.

9. Meal Plan and Shop Smart

Food is one of the biggest expenses in most households, but it’s also one of the easiest to overspend on. Without planning, you might find yourself eating out often or making frequent grocery runs that add up quickly. 

A simple way to handle this is to plan ahead meals for the week by creating a list of meals, shopping with a clear grocery list, and making the most of what you already have at home. Buying in bulk, using coupons, and avoiding shopping when you’re hungry can also save a surprising amount. Not only does meal planning save money, but it also reduces food waste and makes mealtimes less stressful.

10. Avoid Lifestyle Creep

As your income grows, it’s tempting to upgrade your lifestyle by buying nicer clothes, going for bigger purchases, or enjoying more frequent outings. This is called “lifestyle creep,” and it’s one of the fastest ways to lose sight of your financial goals. 

Instead of spending more every time you earn more, focus on keeping your expenses steady and using that extra income to boost savings, investments, or debt repayment. By resisting lifestyle creep, you’ll make real progress toward financial freedom without feeling like you’re stuck living paycheck to paycheck.

11. Review Your Budget Regularly

A budget isn’t something you create once and forget, it needs regular check-ins and adjustments. Whether you’ve paid off a loan, moved to a new place, or your income has shifted, reviewing your budget monthly or quarterly helps you stay on top of these changes and make adjustments where needed. 

Think of it as a financial health check-up where you want to make sure your budget is still serving your goals and supporting your lifestyle in the best way possible.

12. Use Apps or Spreadsheets to Stay Organized

Budgeting doesn’t have to feel like a complicated or overwhelming task, in fact, with all the tools available today, staying organized can be easier than ever before. There are apps that automatically track your spending, sort it into categories, and even send you reminders when you’re close to going over budget. 

On the other hand, if you prefer something simpler and more hands-on, a basic spreadsheet can work just as well because it allows you to see your numbers laid out clearly and in a way that makes sense to you. What matters most isn’t which tool you use, but whether you stick with it consistently. 

When all of your income, expenses, and goals are in one place, it not only gives you clarity about where your money is going but also makes it so much easier to track your progress and stay accountable to the financial future you’re trying to build.

Conclusion

Budgeting is one of the most powerful tools for saving money and building financial security and stability in the long run. It isn’t about saying no to things you enjoy and find comfort in, it’s about saying yes to a secure and stable financial future. By tracking your expenses, setting clear goals, and sticking to a budget that suits you, your income, and lifestyle the best, you can take control of your money instead of letting it control you. The sooner you start budgeting, the sooner you’ll feel the freedom and confidence that comes with financial stability.

7 Most Effective No Spend Challenge Ideas

September 26, 2025 By Ana Rose

In today’s world, it feels like there’s always something to spend money on, whether it’s grabbing your comfort coffee way back home, buying something from the sale, or having a fun hangout with friends that ends up getting costly. This is exactly why a no spend challenge is necessary to reset your financial habits and direct your money towards more essential and meaningful expenses. The no spend challenge is less about being restrictive and more about becoming mindful of your money, figuring out your unhealthy spending habits, and breaking free of them. This article will help you explore the 7 most effective no spend challenge ideas, allowing you to regain control over your finances and become financially free and stable in the long run by developing healthy spending habits. 

7 Most Effective No Spend Challenge Ideas Graphic

Why Try a No-Spend Challenge?

Many of us don’t realize how our spending usually runs on autopilot with us buying things whenever we feel like it and then end up wondering where all our money went at the end of the month. Whether you’re saving for a big goal, trying to break the paycheck-to-paycheck cycle, or simply curious about your spending patterns, this challenge can be an eye-opening experiment. 

The no spend challenge urges us to pause and rethink our spending habits, pushing us to ask questions like, “Do I really need this?”, “Is this purchase worth my hard earned money?”, or “Am I buying this just for the sake of buying it?”. Asking yourself these questions can help you reflect your choices and become more mindful towards the money you work hard for.  

Key Benefits of No-Spend Challenges

Saving money might be an obvious advantage of this no spend challenge, but it goes way beyond that. A no spend challenge can help reduce impulse buying, encourage creativity, and strengthen self-discipline, essential for financial freedom and stability. 

It can also bring unexpected perks like more family time at home, a cleaner pantry, or the joy of rediscovering hobbies you’ve neglected and no longer pursue. In short, the no spend challenge can help you learn that fulfillment and contentment doesn’t always have to come with a price tag.

How to Prepare for a No-Spend Challenge

Person organizing groceries and essentials in a kitchen while marking a checklist on a clipboard, with a calendar showing marked days in the background, pastel pink backdrop with soft highlights.

To ensure that the challenge works the best for you, it’s essential to prepare beforehand so that when the challenge starts, you don’t have to fight the temptations to spend. Before starting, you can set clear rules such as what counts as an essential expense and what may fall under the non-essential spending category. 

Stock up on household basics so you’re not caught off guard, and let your family or roommates know what you’re doing so they can support you. Moreover, planning free activities ahead of time can also make it easier to fight temptations when boredom or the urge to spend shows up.

7 Effective No Spend Challenge Ideas

1. The Weekend No-Spend Challenge

Weekends are usually when the urge to spend shows up the most, whether it’s eating out, going to the movies, or hanging out with friends, weekends have their way of eating away your wallet before you even realize it. 

That’s why the weekend no-spend challenge is the perfect starting point for beginners. For two days, commit to spending only on those basic expenses like groceries or transportation, and cut out all the extras. Instead of going to the mall, you can plan a family picnic, explore a local park, try new recipes at home, or even host a game night. 

2. The Weekday Coffee or Lunch Swap

Coffee runs and daily lunches may seem like tiny expenses, but when added up, they can eat a huge chunk of your monthly budget. This challenge focuses on replacing those daily purchases with home alternatives such as trying to brew your coffee before leaving for work or prepping your lunch the night before so you don’t rely on dining out or takeouts. 

Not only will you save money, but you’ll also likely eat healthier, making this no spend challenge idea a considerable option.

3. The 7-Day Essentials-Only Challenge

For one week, challenge yourself to spend only on absolute necessities, such as on things like groceries, rent, utilities, or medical needs. Everything else, whether it’s snacks, takeout, or impulse shopping, is put on hold. 

While it can feel restrictive at first, this challenge helps you recognize how often spending happens out of habit and it’s truly needed. By the end of the week, you’ll likely feel more disciplined and in control, with a clearer understanding of what truly counts as essential.

4. The Pantry and Freezer Clean-Out Challenge

Most households have a pantry or freezer full of food items that often go unused. The pantry and freezer clean-out challenge encourages you to make meals using only what you already have at home before buying more. 

It pushes you to get creative in the kitchen, reduces food waste, and saves money at the same time. Moreover, it’s surprisingly satisfying to see your pantry organized and your freezer finally cleared of things you’d forgotten about. This challenge not only organizes your food budget but also teaches you to be more mindful about grocery shopping in the future.

5. The No Online Shopping Challenge

Online shopping is one of the biggest spending loopholes where we’re caught up in the never ending track of scrolling, clicking, and buying, all within minutes. For this challenge, you can try to delete shopping apps, log out of your accounts, and unsubscribe from promotional emails to avoid any triggers. 

The idea is to create a space between yourself and the temptation to shop and while it may feel uncomfortable at first, especially if online shopping has become a habit, you’ll quickly notice how much money you save by the end of the challenge. 

6. The Entertainment Swap Challenge

Group of friends enjoying a board game night at home with snacks and laughter, with faint icons of hiking, books, and movies floating in the background on a pastel pink highlighted backdrop.

Entertainment can be one of the most expensive parts of a monthly budget, but it doesn’t always have to be. This challenge is all about replacing costly outings with free or low-cost alternatives such as instead of going to the cinema, you can plan a cozy movie night at home, trade concerts for free community events, or swap expensive dinners for a fun potluck with friends. 

Activities like hiking, biking, or visiting a library with a friend can provide just as much enjoyment but without draining your wallet and can also serve as a reminder that making memories doesn’t always have to mean spending money.

7. The 30-Day No-Spend Challenge

This is the ultimate version of the challenge which is all about an entire month of no unnecessary spending. This 30 day no spend challenge requires commitment and planning but can completely reset your financial habits. 

For 30 days, you’ll stick to only essential expenses and cut out all extras. The first week may feel tough, but as the month goes on, you’ll likely notice positive changes and by the end, you’ll feel empowered and confident about managing your money.

Common Mistakes to Avoid During a No-Spend Challenge

While a no spend challenge may sound simple and easy to follow, it’s common to make mistakes. One of the biggest mistakes people make is not setting clear rules, and without those clear rules, it is easy to justify spending on those ‘small’ yet harmful expenses that affect the whole point of the no spend challenge. 

Another mistake is that some people focus too much on what they can’t do which makes the whole challenge feel more of a punishment than a liberation from those unhealthy spending habits. Lastly, some people start too big, for example, starting a 45 day no spend challenge as a beginner. This usually leads to burnout and frustration, ultimately resulting in quitting the challenge midway. 

How to Stay Motivated Through the Process

The hardest part of the challenge is not starting, it is staying motivated and committed to the challenge throughout the journey.  To keep your motivation high, try to find ways to track your progress such as writing down each no-spend day on a calendar or using a savings app to see your balance grow. 

Celebrate small wins with free rewards, like a relaxing self-care night or a fun outing that doesn’t cost money. Sharing the challenge with a friend or family member can also keep you accountable and make the process feel more fun. 

Life After the Challenge

When the challenge ends, you may feel drawn towards a costly celebration but that often erases all your hard work. Instead, use the end of the challenge as an opportunity to reflect on the journey and the choices you made. You can ask yourself questions like “What did I learn?”, “What habits were the hardest to break?”, or “Did I make any progress?”. 

You may come to realize that you don’t have to grab a coffee everyday on your way to work, or that those seemingly harmless online shopping was eating more of your budget than you thought. 

Conclusion

A no-spend challenge is much more than skipping purchases, it’s a powerful tool for self-awareness and financial growth. By planning ahead, staying motivated, and avoiding common mistakes, you can turn a simple challenge into a life-changing experience. Along the way, you’ll save money, build discipline, and discover that happiness and fulfillment don’t always come with a price tag. And when the challenge is over, the real reward isn’t just the money you’ve saved, it’s the confidence and control you gain over your financial life.

  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 47
  • Go to page 48
  • Go to page 49
  • Go to page 50
  • Go to page 51
  • Interim pages omitted …
  • Go to page 170
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers