• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

Blog

20 Smart Christmas Budgeting Tips

October 5, 2025 By Ana Rose

The holiday season is the time of happiness, togetherness, and love, but along with the joy, the season brings financial stress with multiple expenses hanging over your head. From pricey decorations to hosting family feasts, the expenses for Chrismtmas can pile up quickly and without a plan, they may leave you behind wondering where all the money went. The good news is that with a little foresight and smart planning, you can enjoy Christmas without draining your wallet and stressing over the finances. This article will help you explore 20 smart Christmas budgeting tips, helping you enjoy the holiday season instead of overwhelming yourself financially. 
20 Smart Christmas Budgeting Tips Graphic

1. Set a Realistic Holiday Budget

One of the most effective budgeting tips when saving for Christmas is knowing your limits. Sit down with a pen, paper, or budgeting app and figure out how much money you can comfortably set aside for the holidays.

The key is to be honest with yourself and create a budget based on that honesty. Once you have a total, break it down into categories like gifts, food decorations, or travel, and once you have a clear picture of your expenses too, you can easily align your income with those holiday expenses, helping you set a realistic holiday budget.

2. Make a Gift List and Stick to It
Person sitting at a desk writing a Christmas gift list in a notepad, with small icons of presents, checkmarks, and price tags around them. A decorated Christmas tree with ornaments and lights is in the background, set against a pastel pink background with soft highlights.

It’s easier to get carried away when shopping for Christmas, which is why it is essential to make a list and more importantly, stick to it. Write down every person you’re buying for, assign a spending limit to each, and when you go shopping, try to stay within the spending limit to avoid impulse buying or overspending. 

3. Start Saving Ahead of Time

This holiday season may come once a year, but it doesn’t have to sneak up on your wallet each time it shows up. Start setting aside little money each week or each month before December comes around, and at the end of the year, these small but consistently saved amounts can add up quickly, making Christmas far less overwhelming. 

4. Create a Separate Christmas Fund

One of the easiest ways to deal with the expenses of Christmas is to create a separate Christmas savings fund. This could be a physical jar or envelope in which you save cash or a savings account if you prefer digital banking. 

If you prefer to go with a savings account, a better approach would be to save the amount in a separate yet easily accessible account so that the savings are given a quiet room to grow with no drama and distractions. 

5. Track Every Expense

It’s easy to lose track of your spending when you’re caught up in the holiday spirit. From extra wrapping paper to spontaneous treats, these small purchases can add up faster than we may realize. Try to track your expenses through budgeting apps, spreadsheets, or something as simple as a notebook. 

This simple yet highly effective budgeting tip can help you stay aware of your spending choices, helping you become more mindful and intentional about what you spend on.  

6. Shop with Cash or Debit Instead of Credit

Holiday cheer often feels exciting at the moment, but it can quickly turn into holiday debt if you rely too much on credit cards. To save yourself from that stress, try sticking to cash or a debit card for your holiday shopping, since cash gives you a clear boundary and you can only spend what you have in hand. 

This way, you keep yourself grounded, enjoy the season within your means, and avoid the post-Christmas financial hangover of carrying high-interest credit card debt into the new year.

7. Take Advantage of Seasonal Sales

Sales are everywhere during the holiday season, whether it’s Black Friday, Cyber Monday, or countless discounts or deals before Christmas. The trick is to be intentional, make a list of what you need ahead of time, and then look for those items when sales come up. 

Avoid buying just because something is “70% off,” since that can actually make you spend more.

8. Buy in Bulk to Save Money

Holiday essentials like wrapping paper, ribbons, or cards often cost more when bought individually, which is why buying in bulk can be a considerable budgeting tip. Not only does buying in bulk lower the cost per item but it also leaves you with extra material you can use later on in life. 

9. Embrace DIY and Handmade Gifts

Gifts don’t have to be pricey or branded to be meaningful, in fact, handmade gifts carry more thought than anything you could buy in a store. You can bake cookies, make homemade candles, or put together a playlist of meaningful songs. 

These kinds of thoughtful gifts show effort and care, reminding us that not everything has to come with a price tag to be considered special.

10. Suggest a Gift Exchange (Secret Santa/White Elephant)

If you’re a part of a big family or a big friend circle, suggest the possibility of exchanging gifts, like the Secret Santa or White Elephant. This way, each person has to buy only one gift, yet everyone still gets to feel included in the gift exchanging process. 

Moreover, this idea can push you to get more creative, since you’ll focus on buying one meaningful gift rather than stretching your budget buying many. . 

11. Give Experiences Instead of Things

Not everything has to be wrapped up in paper and bows to be considered a gift, because sometimes the best gifts are the ones that turn into memories. Instead of buying another sweater or gadget, consider offering an experience like cooking someone a special dinner, taking them out for a cozy coffee date, or even creating a handmade “coupon” for a fun day together. 

12. Reuse and Repurpose Decorations

Cheerful person holding a box of old Christmas ornaments, ribbons, and fairy lights while a nearby crafting table shows scissors, glue, and paint for DIY repurposing. A cozy living room with a wreath and stockings is subtly visible, all on a pastel pink background with glowing highlights.

Every year, stores are filled with new holiday décor trends, but you don’t actually need to buy everything fresh. 

Before heading out to shop, take a look at what you already own and you might be surprised at how easily old ornaments, lights, or wreaths can be repurposed or refreshed with a little creativity. Sometimes a simple coat of paint or rearranging decorations in a new way can make them feel brand-new. Not only does this save you money, but it also gives your home a warm, nostalgic feel that new decorations often can’t replicate.

13. Plan Holiday Meals on a Budget

Holiday feasts are special, but they can also become one of the biggest expenses of the season if you’re not careful. Instead of overspending on elaborate meals, plan ahead by creating a simple yet delicious menu that uses budget-friendly ingredients. 

You can also turn gatherings into potluck-style celebrations, where everyone contributes a dish, as this way, the financial and cooking responsibilities are shared. 

14. Cut Back on Non-Essential Extras

When the holiday season arrives, it’s tempting to spend on those little extras like fancy wrapping paper, expensive gift tags, or over-the-top table décor, but the truth is these small purchases can pile up faster than you expect. 

Instead of going all out, focus on the essentials and maybe even get creative by using things you already have at home, like old ribbons, brown paper bags, or even recycled gift boxes, which not only saves money but also makes your holiday feel more thoughtful and personal.

15. Use Coupons, Cashback, and Discounts Online

Shopping online during the Christmas season can feel overwhelming with so many offers flashing across your screen, but if you take a little time to hunt for coupons, use cashback apps, or apply discount codes, you can actually stretch your budget much further without cutting down on what you want to buy.

16. Set Realistic Expectations with Kids

Children often get caught up in the excitement of Christmas and may want every toy or gadget they see, but it’s important to gently set realistic expectations so they don’t feel disappointed and you don’t feel pressured to overspend. 

You can explain to them in a warm way that Christmas is more about love, family, and making memories than about piles of presents, and by being honest early on, you’re not only protecting your budget but also teaching them valuable lessons.

17. Avoid Last-Minute Shopping

One of the biggest traps during Christmas is leaving everything to the last minute, because when you’re in a rush, you’re more likely to buy whatever is available, often at higher prices, and without thinking much about your budget. Planning ahead gives you time to compare prices, look for discounts, and choose gifts and essentials with care, while avoiding impulse buying or overspending.

18. Be Honest About Your Budget with Loved Ones

There can be a lot of unspoken pressure during Christmas to spend more than you’re comfortable with, especially if friends or family have bigger budgets, but being honest about your own limits is a healthier and kinder approach in the long run.

A simple conversation about keeping things affordable can help everyone feel included without unnecessary financial stress, and your loved ones may respect your openness as well.

19. Save on Travel by Booking Early

If your Christmas plans involve traveling to see loved ones, waiting until the last moment to book tickets or hotels almost always costs more, so the earlier you can plan, the better your chances of finding affordable options. Planning your travel early not only saves money but also gives you peace of mind knowing everything is already arranged.

20. Focus on the True Spirit of Christmas 

At the heart of it, Christmas isn’t meant to be about how much you spend or how many things you buy, but about the warmth of family, the joy of giving from the heart, and the simple moments that make the season special. By focusing on togetherness, kindness, and love rather than on expensive gifts, you can create memories that last far longer than any material item and enjoy a holiday that feels full of happiness instead of financial stress.

Conclusion

Christmas can sometimes trick us into thinking that joy comes from shiny presents, lavish meals, and expensive decorations, but the truth is that it’s the simple, thoughtful choices that make the season truly magical. By planning ahead, staying within your means, and being creative with how you give and celebrate, you not only protect your wallet but also free yourself to focus on what really matters. With these smart Christmas budgeting tips, you can welcome the holidays with peace of mind, a lighter financial load, and a heart that feels full without the burden of overspending.
The Best Ever Budgeting Tips For New Homes

October 4, 2025 By Ana Rose

Moving into a new home is one of the greatest milestones in one’s life. Whether it’s your very first house or you’re moving into a new home with your growing family, this big step can feel like a fresh start. Along with the joy of decorating, organizing, and customizing your new home according to your taste, the responsibility of managing the expenses and finances come along. From mortgage payments to utility bills, the expenses can pile up quickly, especially if you don’t have a plan to deal with them, which is exactly why it is essential to create a realistic budget and stick to it throughout the process. This article will explore some helpful budgeting tips for new homeowners, guiding them as they begin this exciting chapter in their new home.

The Best Ever Budgeting Tips For New Homes Graphic

Start With a Clear Financial Picture

The first step in managing money for your new home starts with having a clear picture of where you stand financially. Moving into a new place often brings excitement, but it can also tempt you into spending more than you may realize. This is exactly why it is important to have a clear financial picture before making any big decisions. 

Take notes of your monthly income, your expenses, and debts, if there are any. This can help you align your spending habits with the money coming in every month, helping you avoid overspending and keeping you from overcommitting yourself financially.

Create a “New Home Budget”

A new home always brings along a whole new set of expenses that can sometimes feel overwhelming, which is why having a separate “new home budget” can really make life easier. Instead of mixing all your costs together and then wondering where the money went, try to divide things into clear categories like your mortgage or rent, the utility bills, furniture, décor, appliances, and the regular maintenance that every home eventually needs. 

When you do this, you can actually see where your money is going, and it stops that uneasy feeling of money slipping away without you noticing. For example, you might realize that you’re spending a little too much on decorations while completely forgetting to plan ahead for electricity or heating costs, and that small realization can make a big difference.

Don’t Overspend on Furniture Right Away

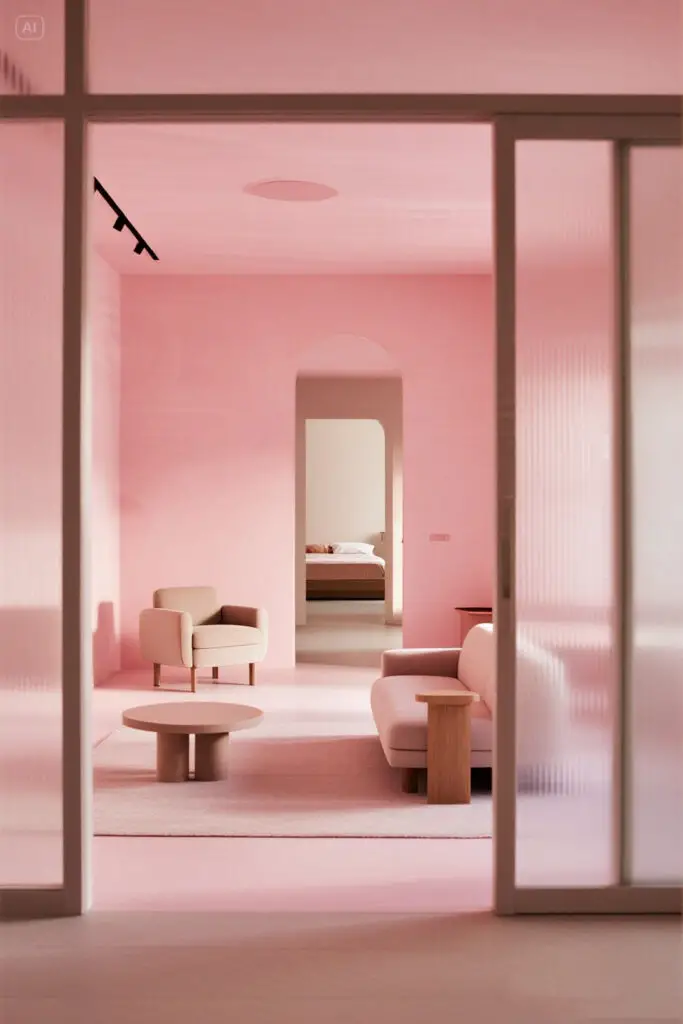
Minimal living room with only a sofa, coffee table, and bed, leaving empty spaces to show waiting before buying extra furniture.

One of the biggest mistakes new homeowners make is that they rush to fill in every room right away. While it’s natural to want your home to look complete, it’s essential to consider your finances as well.  

You can focus on essentials first such as a comfortable bed, a sofa, or a dining table for the family, and slowly move toward the non-essential furniture. This approach not only protects your budget but it also gives you the time and space to rethink your choices and buy pieces you’ll truly love, rather than settling for something just to fill the space. 

Account for Hidden Costs

When you first move in, it’s easy to focus on those big and obvious expenses like the mortgage or rent but new homeowners are often surprised by all the hidden costs that sneak in. Things like property taxes, HOA fees, trash collection, lawn care, and even small repair bills can add up quickly and if you don’t plan for them, they can feel like an unwanted shock each month. 

That’s why it’s smart to include them in your budget right from the start. Even if some of these expenses don’t apply to your situation, knowing they might pop up helps you stay prepared. Planning for hidden costs means fewer surprises and more control, which keeps your finances steady and stress-free in the long run. 

Prioritize Needs Over Wants

When setting up your new home, it’s easy to get carried away with aesthetic decor or high-tech gadgets, but before you start buying your wants, make sure your needs are covered. For instance, a working fridge, reliable stove, and furniture should take priority over trendy extras like smart lights or expensive art pieces. 

Focusing on needs can ensure that your daily life is taken care of and is functional, on the other hand, wants can wait until your finances are ready. By taking this approach, your home will feel both practical and personal, and your wallet will thank you for being mindful with spending. 

Build an Emergency Fund for Home Repairs

Piggy bank with coins and small tools beside it, symbolizing saving money for unexpected home repair costs.

No matter how new your home is, unexpected expenses show when you least expect them, which is exactly why it is necessary to have an emergency fund in place. Whether it’s a burst pipe, a broken appliance, or sudden roof repair, having a safety net can help you deal with these unexpected expenses with confidence without having to put your entire budget off track.  

You can start with a small and achievable target, maybe $500 or $1000, and build it up over time to cover a few months’ worth of essential expenses. Even a modest amount of money can give you peace of mind, knowing that you don’t have to rely on credit cards or loans can prevent you from stressing over the future. 

Compare Utility Providers

Utility bills are a regular part of homeownership, but many people don’t realize that they may be paying more for these services than necessary. Another effective budgeting strategy is to take time to compare providers and see if you can get a better deal without sacrificing quality. 

Even if the savings seem small, like $10 or $20 a month, these amounts can add up quickly and free up money for your other needs as well. Moreover, being mindful of how you use these utilities, like turning off lights, unplugging devices, or adjusting the thermostat can help reduce the costs even more. 

DIY Where You Can

Whether it’s painting a wall, planting a garden, or even assembling the future, try not to hire professionals, instead, let your creative side unleash and get the work done with a bit of creativity and effort. 

The best part about DIY projects is that they not only help you cut back on costs but they also provide you with a sense of accomplishment and pride. Not everything should be tackled on your own but those smaller projects are a fun and rewarding way to make your home feel truly yours, making this option a considerable budgeting tip for new homeowners.  

Avoid Debt Traps

While setting up your new home, the temptation to finance Pinterest-worthy furniture or high-tech gadgets on credit may kick in, and although this may seem like an easy way to get everything quickly, it often leads to high-interest debt that becomes a long-term burden. 

Instead, try to pay for items with cash or savings whenever possible, and if you must use credit, stick to purchases you can pay for right away to avoid carrying a balance over your shoulders. Avoiding debt traps can help you protect your financial health, letting you enjoy the comfort and blessing of your new home instead of burdening yourself with the pressure of repayments and debts. 

Plan for Seasonal Expenses

Every season brings different expenses, and if you’re not well prepared to deal with these expenses, they can throw your entire budget off track. Whether it’s winter bringing higher heating bills, summer bringing higher cooling costs, or holiday seasons bringing along the expenses of decorations, planning ahead for these seasons can help you deal effectively with the finances, without having to use your entire budget. This approach can help you stay in control of your money and enjoy the season rather than stressing over the finances. 

Use Second-Hand and Discount Options

When setting up a new home, it’s natural to want everything brand-new, but sometimes the smarter move is to mix in second-hand or discounted pieces that save you money without taking away from your home’s beauty or comfort. Thrift stores, online marketplaces, or clearance sales, can be full of hidden gems that look just as good as new items but cost only a fraction of the price. 

You might be surprised to find that a solid wooden table from a thrift shop lasts longer than an expensive new one from a big store. By being open to second-hand or discounted options, you leave more room for important priorities, while also giving your home a unique touch.

Keep a Home Maintenance Calendar

One of the biggest money drains for homeowners often comes from neglecting small issues until they become large and costly repairs, which is why keeping a simple home maintenance calendar is such a wise budgeting habit. Scheduling regular checks for things like changing air filters, servicing appliances, cleaning gutters, or inspecting your plumbing and roof can help you spot problems early before they turn into emergencies. A maintenance calendar also takes the stress out of remembering everything, giving you peace of mind that your home is being cared for in a steady and manageable way. 

Conclusion

Moving into a new home is one of life’s most exciting milestones, but it also comes with responsibilities that require thought, care, and planning. By creating a budget that prioritizes needs over wants, preparing for emergencies, being smart about utilities, and avoiding the traps of debt, you give yourself the chance to build a home that feels not just beautiful but financially secure. Little habits like shopping second-hand, keeping up with maintenance, and tracking your spending regularly can make a big difference in keeping your finances balanced and stress-free. At the end of the day, your home should be a place of comfort and peace, not a source of financial worry.

10 Steps To Financial Freedom

October 3, 2025 By Ana Rose

Financial freedom is one of those goals everyone dreams to achieve but very few of us manage to get there. For everyone, the definition of financial freedom is different, some see it as the ability to live life on your own terms while some may see it as being debt-free, having money in savings, or simply not stressing over bills every month. In today’s age where inflation is rising, debts and unexpected financial emergencies are a part of life, financial freedom can feel like a distant dream. But the truth is, financial freedom isn’t reserved for the wealthy only, it can be built step by step through conscious efforts while maintaining discipline and confidence. This article will help you explore a step by step guide towards financial freedom, helping you become financially secure and stable in the long run. 

10 Steps To Financial Freedom Graphic

Step 1: Define What Financial Freedom Means for You

For the first step towards financial freedom, you need to think about what financial freedom truly means to you. If you don’t know what you’re aiming for, no amount of saving, budgeting, or investing will feel satisfying because you won’t have a clear finish line. 

You can take some time and reflect on your values and priorities. Whether it’s saving a specific amount, securing your children’s education, or reaching a level of income that allows you to live life on your own terms, having a clear goal can help make the process more personalized, ultimately helping you become more motivated and consistent to achieve your target. 

Step 2: Track Your Money

A woman writes expenses in a notebook on a pastel pink background, surrounded by floating receipts, coffee cups, and shopping bags. Soft glowing highlights symbolize awareness of spending habits.

Once you know what financial freedom looks like for you, the next step is to track your money. The key point of this step is to know your income and modifying your spending habits considering your hard earned money. Most people believe they know their spending habits, but the truth is, small purchases like daily coffees, takeout meals, subscriptions, or impulse shopping add up faster than we realize and quietly drain our income.

You can track your money through budgeting apps, spreadsheets, or something as simple as a notebook. Record all sources of income and every expense, either big or small, for at least one month. When you review the results, you’re likely to find some spots where money slips away, offering you the opportunity to modify your spending habits and redirect that money towards your bigger goal. 

Step 3: Create a Realistic Budget

The next step is to create a realistic budget that feels empowering for your money, rather than a restriction or punishment. A good budget can help you balance your needs, wants, and long-term goals perfectly without making you feel deprived or holding back on things you enjoy. 

One popular method is the 50/30/20 rule where 50% of your income goes to the basic expenses which include rent, groceries, transportation, or utilities. 30% of the income is spent on non-essential expenses that include takeouts, shopping, subscriptions, or hobbies. Lastly, 20% of the income goes to savings and debts, if there is any. 

You can also consider the envelope method where every dollar is assigned a purpose to serve. In this budgeting method, categories are made, such as groceries, transportation, or food, and envelopes are labeled with each category’s name. A certain amount of cash is placed into each envelope at the start of the month, and once the money in a particular envelope is spent, you can’t add more or borrow from another category. This method forces you to stay disciplined, spend within limits, and become more mindful about where every dollar goes.

Step 4: Build an Emergency Fund

Life has its way of throwing curveballs when we least expect them, such as medical bills, job loss, or sudden car repairs can turn your financial world upside down if you’re not prepared. This is why building an emergency fund is one of the most important steps towards financial freedom, because it gives you a safety net instead of relying on loans or credit cards in times of financial crisis. 

You can save three to six months’ worth of essential living expenses, but if that feels overwhelming, start small by setting a goal of $500, then $1,000, and gradually build from there. Even a modest emergency fund can offer you peace of mind, because knowing that you have money set aside allows you to face challenges without panicking or stressing over the future. 

Step 5: Eliminate High-Interest Debt

Debt is one of the biggest obstacles standing between you and financial freedom, especially high-interest debt like credit cards, payday loans, or personal loans that seem to grow faster than you can pay them off. The first step to tackling debt is to list all your balances along with their interest rates, so you can see clearly where your money is going.

From there, you can choose between two proven strategies, the debt snowball method, where you focus on paying off the smallest balance first while making minimum payments on the others, which builds confidence and momentum along the way, or the debt avalanche method, where you pay off the highest-interest debt first, saving more money in the long run. 

Step 6: Increase Your Income Streams

Relying solely on one income in today’s economy is risky, because if that job disappears, so does your financial stability. That’s why it’s important to explore different ways to earn money on the side, no matter how small they may seem at first. You can think about your skills and hobbies, whether it’s writing, teaching, baking, or even creating digital content, use your skills to create a side hustle that brings in extra income. 

The purpose is not to overburden yourself but to make your financial life more secure and flexible. Even an additional $100 or $200 earned in a month can make a difference when directed toward savings, debt repayment, or investments. Having multiple streams of income gives you peace of mind and more choices in life, because you’re not tied down to one source of money or worried about what will happen if it suddenly stops.

Step 7: Save and Invest Consistently

A woman places coins into a flourishing money plant against a pastel pink background, with a savings jar and a stack of books beside her. Glowing highlights represent long-term financial growth.

Saving money is the foundation of financial security, but investing is what truly helps your wealth grow over time. Many people hesitate to invest because it feels complicated or risky, but the truth is, you don’t need to be an expert or start with a huge amount. Savings keep your money safe for short-term goals, but investments help your money work for you in the long run through the power of compounding. Even if you start with something small like $50 or $100 a month in a retirement fund, mutual fund, or index fund, it can grow into something much bigger over the years. The key is to keep adding to it, no matter how small the amount, and not pull it out for temporary wants. When you save and invest consistently, you create a sense of security and freedom, knowing your future is taken care of and you’re not just depending on your paycheck alone.

Step 8: Protect Yourself with Insurance

No matter how well you plan, life can bring unexpected challenges, and without proper protection, a single event can wipe out years of progress. This is where insurance becomes essential, it acts like a shield to protect you, your family, and your money. Health insurance, life insurance, and even property insurance may feel like an extra expense, but in reality, they save you from massive financial loss when something unexpected happens. 

By getting the right insurance for your situation, you’re not only protecting yourself but also giving your family the security they deserve. It’s not about expecting the worst to happen but being smart enough to prepare in case it does, so that your journey to financial freedom doesn’t get derailed.

Step 9: Keep Learning About Money

Money is not something you figure out once and never look at again, it’s a lifelong learning process. The financial world keeps changing, with new tools, new opportunities, and new risks, and the more you learn, the better choices you can make for yourself. 

You don’t need to become a finance expert, just making small efforts to read personal finance books, listen to podcasts, or follow reliable money experts can make a huge difference. When you keep learning, you also protect yourself from falling into scams, making poor investment decisions, or staying stuck in unhealthy financial habits. 

Step 10: Live Below Your Means & Stay Disciplined 

At the heart of financial freedom lies discipline, and one of the most important habits to develop is living below your means. This doesn’t mean you have to live a boring or joyless life, it simply means resisting the urge to spend more every time your income grows. Many people earn high salaries but are still stressed about money because their lifestyle expenses keep increasing with their paycheck. 

On the other hand, people with average incomes often build wealth because they are careful, thoughtful, and consistent with how they spend and save. Living below your means allows you to create a gap between what you earn and what you spend, and that gap is where savings, investments, and true financial security come from. 

Conclusion

Financial freedom may sound like a distant dream, but in reality, it is built step by step through conscious decisions, discipline, and patience. By defining what financial freedom means for you, tracking your money, budgeting wisely, saving, investing, and protecting yourself with the right tools, you gradually build a life where money is no longer a constant source of stress. Each small step adds up, and even if progress feels slow, remember that every dollar saved or invested is moving you closer to peace of mind and independence. The beauty of financial freedom is that it doesn’t require you to be rich, it just requires you to be intentional, thoughtful, and consistent with your choices. 

100 Powerful Financial Freedom Quotes For Women

October 2, 2025 By Ana Rose

Financial freedom is not just about money, it’s about building confidence, boosting self-esteem, and having the ability to live life on your own terms and conditions. For women, the journey towards financial freedom may be more difficult due to differences in gender pay gaps, limited opportunities, and balancing family responsibilities with personal goals. However, with determination and the right mindset, women all across the globe continue to rise above and work towards financial security and freedom, proving themselves resilient, courageous, and strong. This article will help you explore 100 financial quotes for women, inspiring you through powerful words and reminders.

100 Powerful financial freedom quotes for women Graphic

100 Powerful Financial Freedom Quotes

1. “Financial independence is about choosing your life’s direction without waiting for someone else’s permission.”

2. “Every dollar you save is not just money, it’s a step closer to freedom.”

3. “When a woman controls her money, she controls her future.”

4. “A budget is telling your money where to go instead of wondering where it went.” — Dave Ramsey

5. “Money is not the goal, freedom is. Money is just the tool to get there.”

6. “Financial freedom for women means never having to stay where you don’t belong.”

Illustration of a confident woman standing tall on a pastel pink background, holding a briefcase with a rising financial growth chart behind her, glowing highlights symbolizing strength and empowerment.

7. “Budgeting is not a restriction, it’s a roadmap to the life you truly want.”

8. “When women learn to invest in themselves, they open doors to endless possibilities.”

9. “Debt may feel heavy, but discipline will set you free.”

10. “Financial independence allows you to walk away from what doesn’t serve you.”

11. “An investment in knowledge pays the best interest.” — Benjamin Franklin

12. “A financially strong woman is unstoppable.”

Illustration of a woman walking away from a closed door with floating money and freedom icons, pastel pink background with glowing highlights on her path, symbolizing courage and independence.

13. “You don’t need to have it all to start, you just need to start.”

14. “Money can’t buy happiness, but it can buy choices, and choices bring peace.”

15. “Do not save what is left after spending, but spend what is left after saving.” — Warren Buffett 

16.  “Wealth isn’t about how much you earn; it’s about how wisely you manage what you have.”

17. “Financial freedom is the art of saying yes to your dreams and no to your fears.”

18. “Your bank balance doesn’t define you, but it can empower you.”

19. “Smart women don’t wait for luck; they plan for freedom.”

20. “It’s not your salary that makes you rich, it’s your spending habits.” — Charles A. Jaffe

21. “A budget is not about cutting back, it’s about creating space for what matters.”

22. “Financial independence means your voice is never silenced by dependence.”

23. “Women who invest in their future change the future for everyone around them.”

24. “You can’t build wealth overnight, but you can build it over time.”

25. “Financial discipline is the bridge between dreams and reality.”

26. “Don’t just earn money, make it work for you.”

27. “Freedom is having your needs covered and your dreams within reach.”

28. “Financial literacy is the strongest form of empowerment a woman can have.”

29. “Your budget reflects your values; let it reflect freedom, not fear.”

30. “Investing is not just for the wealthy, it’s how you become wealthy.”

31. “A strong woman knows that financial security is self-care.”

32. “Debt does not define you; your decisions do.”

33. “True freedom begins when you stop living paycheck to paycheck.”

34. “Financial freedom is available to those who learn about it and work for it.” — Robert Kiyosaki

35. “A woman with a plan is stronger than circumstances.”

36. “Financial independence is not about being rich, it’s about being in control.”

37. “Money is a tool. Use it to build your future, not your worries.” — Unknown

38. “Earning is power; saving is security; investing is freedom.”

39. “True wealth is the ability to live your life as you wish.” — Henry David Thoreau

40. “Financial confidence shines brighter than diamonds.”

41. “A wealthy mindset comes before a wealthy life.”

42. “Be the woman who writes her own checks and her own story.”

43. “Money doesn’t change who you are; it amplifies your choices.”

44. “A woman who masters money masters her destiny.”

45. “Your worth is not in your wallet, but your wallet should reflect your worth.”

46. ““The goal of financial freedom is not to have more stuff, but to have more choices.” — Suze Orman

47. “You don’t have to know everything about money, you just have to keep learning.”

48. “A budget is a love letter to your future self.”

49. “Do not go where the path may lead, go instead where there is no path and leave a trail, even in your finances.” — Ralph Waldo Emerson

50. “The journey to financial freedom is long, but every step counts.”

51. “Being broke is temporary, financial discipline is forever.”
52. “Independence is when your choices are not controlled by your circumstances.”

53. “A wealthy woman is not one who spends a lot, but one who saves and grows her money.”

54. “Money doesn’t bring happiness, but it gives you the freedom to create it.”

55. “A woman’s financial independence is her shield and her sword.”

56. “True wealth is when your money works harder than you do.”

57. “Financial empowerment means living life on your own terms.”

58. “You don’t have to be born rich to build wealth.”

59. “Financial independence is the ability to live from the income of your own personal resources.” — Jim Rohn

60. “The goal isn’t more money. The goal is living life on your own terms.” — Chris Brogan

61. “Money is not the end, it’s the means to a free and fulfilled life.”
62. “Financial security is not selfish, it’s smart.”
63. “Wealth is not about flaunting; it’s about sustaining.”
64. “Freedom means having the courage to leave situations that don’t serve you, money makes that possible.”
65. “Wealth is not about having a lot of money; it’s about having a lot of options.” — Chris Rock
66. “Financial freedom is a form of self-love.”
67. “Financial peace isn’t the acquisition of stuff. It’s learning to live on less than you make, so you can give money back and have money to invest.” — Dave Ramsey
68. “Dream big, save consistently, invest wisely.”
69. “Money is a terrible master but an excellent servant.” — P. T. Barnum
70. “Wealth doesn’t come from what you earn but from what you keep.”
71. “Every woman deserves the freedom that comes with financial confidence.”
72. “Investing in yourself is the first step to financial success.”
73. “The best thing money can buy is financial freedom.” — Rob Berger
74. “Freedom comes from building habits, not waiting for windfalls.”
75. “A disciplined woman is a wealthy woman.”

76. “Financial independence means your dreams don’t need approval.”
77. “Money is a tool, don’t let it control you, learn to control it.”
78. “The more you learn about money, the more empowered you become.”
79. “Whatever your income, always live below your means.” — Thomas J. Stanley
80. “Wealth is built on patience and discipline, not luck.”
81. “Every smart financial choice builds a stronger tomorrow.”
82. “A secure woman doesn’t ask for freedom, she already owns it.”
83. “Live like no one else now so later you can live like no one else.” — Dave Ramsey
84. “Financial freedom doesn’t just change your life, it changes generations.”
85. “You don’t need millions to be free, you need control over what you have.”
86. “A wise woman invests in her future before she invests in luxuries.”
87. “The lack of money is the root of all evil.” — Mark Twain
88. “Every woman deserves a savings account with her own name on it.”
89. “A woman’s best protection is the little money of her own.” — Clare Boothe Luce
90. “Financial independence allows you to choose love, not dependency.”
91. “Budgeting is not about limits, it’s about freedom.”
92. “Financial independence is paramount. My mom always says that when a woman is financially independent, she has the ability to live life on her own terms.” — Priyanka Chopra Jonas
93. “Every sacrifice you make today plants freedom for tomorrow.”
94. “Your financial journey is personal, don’t compare, just keep moving.”
95. “A wealthy woman invests in both assets and herself.”
96. “Money management is a life skill every woman deserves.”
97. “Financial freedom means your time belongs to you.”
98. “A woman with financial independence is in a powerful position to make a difference in the world.” — Melinda Gates
99. “When women win with money, families and communities win too.”

100. “Every woman has the power to build wealth, no matter where she starts.”

Conclusion

At the end of the day, financial freedom isn’t just about dollars, cents, or numbers written in a bank statement, it’s about the peace of mind that comes when you know you’re in control of your life. For women especially, building financial independence means so much more than paying bills or saving for the future, it’s about creating choices, gaining confidence, and refusing to let circumstances or dependence hold you back from the life you deserve. Each of these quotes is a gentle reminder that freedom doesn’t happen overnight, but grows slowly through courage, patience, and small, consistent actions. Whether you’re learning to budget, paying off debt, saving for your dreams, or simply trying to believe in yourself again, know that every step matters. You don’t have to be perfect, you just have to keep moving forward.

The Most Effective Bi Weekly Savings Challenge 3000

October 1, 2025 By Ana Rose

Saving money is easier said than done when you’re dealing with pending bills, unexpected expenses, and family responsibilities that put your entire budget off track. However, the secret to building savings is in creating a plan that’s realistic, practical, and most importantly, manageable. Unlike strict monthly plans or too frequent weekly saving plans, biweekly plans work best for saving, and even better for those who get paid every two weeks, offering a plan that aligns with their pay schedule. This article will help you explore the dynamics of a biweekly savings plan, helping you save $3,000 in a year without feeling like you’re depriving yourself.

The Most Effective Bi Weekly Savings Challenge 3000 Graphic

Understanding How the Bi-Weekly Savings Challenge Works

The biweekly savings plan is a structured plan designed to help you gradually build savings without having to feel overwhelmed and deprived. Unlike those irregular attempts at saving, this challenge uses the consistency of your pay cycle to your advantage. 

This challenge involves setting aside small amounts more frequently rather than having to save a large amount each month, making this plan more manageable and less stressful. Over time, these small and regular contributions can add up to a significant sum, in this case, $3,000, without requiring big sacrifices.

Break Down the $3,000 Goal

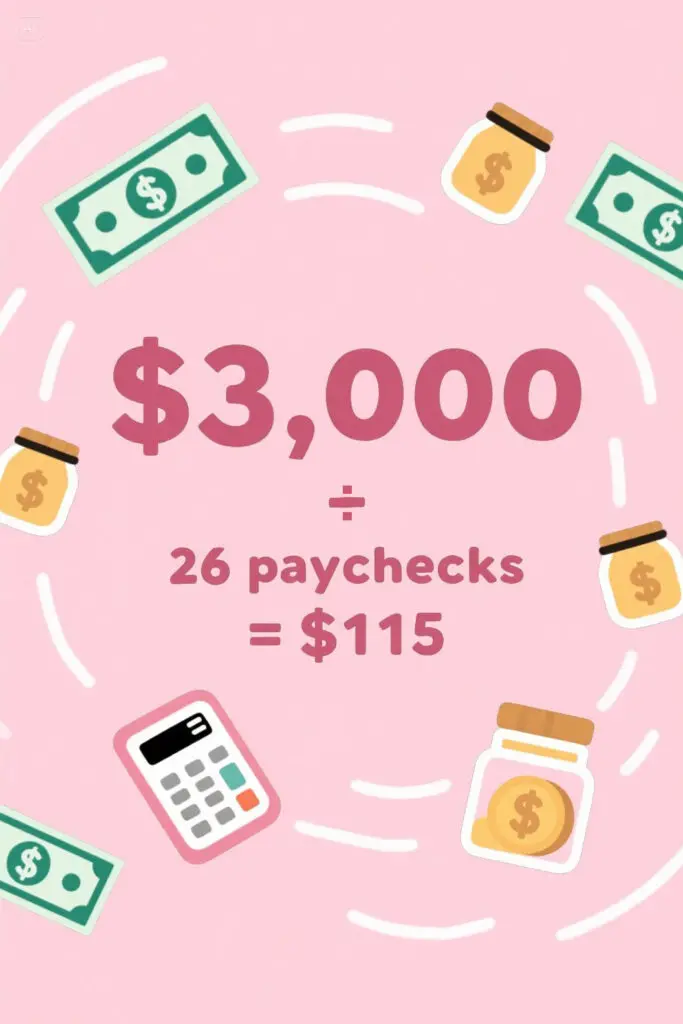
Illustration on a pastel pink background showing “$3,000 ÷ 26 paychecks = $115” with icons of dollar bills, a calculator, and small savings jars, representing how to break a big savings goal into smaller, manageable amounts.

Big financial targets can feel intimidating, but breaking them into smaller and more manageable chunks can make the challenge easier to follow. To save $3,000 in one year, you need to divide this number by 26 pay periods in a bi-weekly cycle, which comes out to about $115 per paycheck. 

When you look at the smaller figure of $115, the challenge may seem easier instead of focusing on the intimidating $3,000 figure. For example, if you know you need $115 from each paycheck, you can adjust your spending on non-essentials, such as coffee runs, dining out, or entertainment to cover it.

Start Small and Increase Gradually

For many people, even $115 may seem like a huge amount, especially if you’re struggling with other financial responsibilities. Instead of sticking to a strict order of setting aside $115 every two weeks, you can begin with a smaller amount, such as $50 or $75, and increase the amount as your budget allows. For example, in the first three months, you might consistently save $75 per paycheck, and once you’ve built momentum and adjusted your spending habits, you can raise it to $100 or $115.

This approach works the best for people who are new to disciplined saving, as it builds confidence and reduces the risk of burnout. 

Automate Your Savings

One of the most effective ways to succeed with the biweekly savings challenge is to automate the biweekly transfers. You can set up an automatic transfer from your checking account to your dedicated savings account. This method flips the script and allows you to prioritize saving. 

What makes this strategy more considerable is that it takes away the stress of deliberately transferring money, helping you rely less on willpower and more on consistency. When the transfer happens automatically, saving becomes as routine as paying a bill, and you don’t have to constantly remind yourself to set money aside. It also removes the temptation to spend that amount on something else, since the money is gone before you can even touch it.

Use a Separate Savings Account

One of the most common reasons people fail to stick to a savings plan is that their money is too easily accessible. When savings sit in the same account as daily spending funds, it becomes tempting to use them for non-essentials, especially when expenses feel tight. 

To avoid this, it’s best to use a separate savings account that is available to you but not easily accessible for you to use whenever the urge to spend arises. A better option would be to use a high-yield savings account where your money can earn interest while it just sits there, growing in peace without any drama or distraction. 

Pair the Challenge with a Spending Audit

Saving money doesn’t always mean earning more, it often means making better use of what you already have. Pairing your bi-weekly challenge with a spending audit is a smart way to free up the funds you need. You can start by reviewing your past two or three months of expenses to identify areas where money is slipping away unnoticed which might include unused subscriptions, frequent dining out, online impulse purchases, or daily coffee runs.

Once you’ve identified these leaks, you can try to manage or eliminate them and redirect that money into your savings challenge. A spending audit not only helps you stay on track but also builds awareness about your financial habits, ensuring your money works for you instead of against you.

Use Cash Envelope Tricks

For those who struggle with overspending, the cash envelope can be a powerful strategy for the biweekly challenge. This strategy is all about allocating a fixed amount of cash to spending categories like rent, food, groceries, or transportation, and keeping that cash in separate envelopes with the category’s name written on them. 

The catch of the cash envelope trick is to avoid overspending on a certain category and staying within the spending limit. What makes this trick more appealing is that it creates natural savings opportunities. For instance, if you have leftover cash in an envelope at the end of the two weeks, you can deposit it directly into your savings account as an extra contribution to your $3,000 goal.

Create Mini-Milestones

Saving $3,000 can feel like an intimidating commitment, and without motivation, it’s easy to quit midway through the challenge, which is why it is necessary to have mini-milestones. Breaking the challenge into smaller checkpoints makes it more manageable and rewarding. For example, aim to save $750 every three months or $1,500 by mid-year, and each time you reach one of these milestones, take a moment to acknowledge your success. 

You can even create visual markers, such as filling in a progress chart or thermometer-style tracker as you save. Small celebrations at each milestone, like a budget-friendly family outing or a favorite home-cooked meal, make the journey feel less like a grind and more like an accomplishment. These mini victories remind you that even though the ultimate goal is $3,000, every step forward is a win worth celebrating.

Add Side Hustle Earnings

Sometimes, cutting expenses isn’t enough to hit your savings target comfortably, that’s why supplementing your income with side hustle earnings can make all the difference. Whether it’s freelancing, tutoring, babysitting, selling handmade crafts, or even decluttering and selling unused items online, every extra dollar adds up. For example, earning an additional $50 from a freelance gig and putting it into your bi-weekly savings means you’ll reach your $3,000 goal faster. 

The best part is that side hustle income often feels like “extra” money, so setting it aside doesn’t affect your regular budget. Instead of spending it impulsively, dedicate those earnings entirely to the challenge, and over time, these small contributions can amount to hundreds of dollars. 

Make it a Family Challenge

Saving money doesn’t have to be a solo effort, instead try turning the challenge into a family activity so that it becomes fun and easier to follow. If you have a spouse, partner, or kids who are old enough to understand the concept, get them involved and turn the savings challenge into a collaborative challenge. 

Together, you can brainstorm small ways to cut costs, like cooking meals at home, choosing free entertainment, or reducing utility bills. Each family member can contribute in their own way, whether it’s skipping an unnecessary purchase or suggesting cost-saving ideas. You can also set family rewards for reaching milestones, like a special picnic or a game night. 

Track Progress Visually

Savings tracker illustration on a pastel pink background with a thermometer-style chart filling up with money icons, stars, and confetti, symbolizing motivation and progress toward the $3,000 biweekly savings challenge.

Humans are naturally motivated by progress they can see, which is why tracking your savings visually can be a powerful tool in this challenge. Create a simple savings tracker chart, thermometer graphic, or even use a jar where you deposit cash every two weeks. 

Each time you add money, update your tracker so you can physically see how close you are to your $3,000 goal. This visual reminder keeps you accountable and motivated, especially on weeks when saving feels tough. By turning your progress into something visible and interactive, you transform the challenge from a financial task into a rewarding, motivational journey.

Reward Yourself Smartly

One of the best ways to stick with long-term goals is to reward yourself along the way, but the trick is to do it wisely. When you hit milestones in your $3,000 challenge, take a moment to celebrate your progress without undoing your hard work.

You can treat yourself to a cozy at-home spa day, cook your favorite meal, or plan a budget-friendly family activity. These small rewards give you something to look forward to and make the journey feel lighter. By rewarding yourself wisely, you build positive habits and keep your eyes on the bigger goal and when you reach the end, the best reward of all will be the $3,000 you’ve saved.

Conclusion

The bi-weekly savings challenge is one of the easiest and most practical ways to build a solid financial cushion without feeling stressed. It works because it fits into your pay schedule, breaks a big goal into smaller, manageable steps, and keeps you moving forward with simple strategies like automation, spending audits, and visual trackers. Along the way, little milestones and small rewards make the process exciting, while support from family or a little extra income can help you reach your goal even quicker. The best part is that this challenge doesn’t require extreme sacrifices, it’s all about steady, consistent action. By the end of the year, you won’t just have $3,000 in savings, you’ll also have stronger money habits that prepare you for bigger financial goals in the future. 

  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 46
  • Go to page 47
  • Go to page 48
  • Go to page 49
  • Go to page 50
  • Interim pages omitted …
  • Go to page 170
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers