• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

General Personal Finance Blog

13 Key And Powerful Financial Freedom Habits

September 21, 2025 By Ana Rose

Financial freedom is not something that just happens to show up in your life one morning, it is something you slowly build through the small choices you make every single day about how you earn, how you save, how you spend, and how you invest your money. For many people, the whole idea of financial independence can feel scary or even too big to reach, but the truth is that it is not about doing everything at once or being perfect, it’s about creating steady routines that change the direction of your financial life. These habits are not about living a life where you never enjoy yourself or cutting out every single thing you love, they are about finding balance and creating peace of mind so that money works for you instead of you always working for money. This article will explore 13 healthy financial freedom habits, helping you become financially stable and free in the long run. 

13 Key And Powerful Financial Freedom Habits Graphic

1. Live Below Your Means

Illustration of a person happily carrying a small shopping bag labeled “Living Below Means,” while a larger bag labeled “Overspending” sits aside. The pastel pink background with golden highlights represents balance, simplicity, and financial discipline.

One of the most powerful money habits you can ever develop is the ability to live below your means. This doesn’t mean you have to live a boring life, it means you spend less than you earn so that there is always room to save, invest, and grow. 

Many people fall into the trap of lifestyle inflation, where every raise or bonus is quickly matched with new expenses like a bigger car, fancier gadgets, or pricier outings. Living below your means is about resisting that temptation and choosing a lifestyle that allows you to enjoy today while still preparing for tomorrow.

2. Create and Follow a Budget

When you create a budget, you are simply telling your money where to go instead of wondering where it disappeared at the end of the month. A budget helps you cover your essentials, plan for savings, and still enjoy some of the things you love without guilt. 

The key is to be realistic and not cut everything fun out of your budget, or you’ll burn out and give up. Instead, design a plan that balances needs, savings, and wants in a way that feels sustainable. Following your budget consistently turns money into a tool you control rather than something that controls you.

3. Build and Maintain an Emergency Fund

Illustration of a glass jar labeled “Emergency Fund,” filled with coins and dollar bills, with a glowing shield behind it. A smiling person stands nearby, symbolizing security and preparedness. The pastel pink background with golden highlights conveys financial protection and peace of mind.

An emergency fund is your shield against the unexpected, whether it’s a car repair, a medical bill, or an urgent home expense. Without this cushion, many people are forced to rely on credit cards or loans, which only dig them deeper into financial stress.

Building an emergency fund, even a small one to start, gives you peace of mind because you know you’re prepared for the bumps in the road. Over time, growing this fund to cover three to six months of expenses makes you strong enough to handle bigger challenges like job loss or sudden health issues without panic. 

4. Avoid and Eliminate Debt

Debt is one of the biggest barriers to financial freedom, because every dollar you send to lenders is a dollar you can’t use to build your own future. Whether it’s credit cards, car loans, or personal loans, debt limits your choices and keeps you tied down. 

Avoiding unnecessary debt is one side of the habit, and the other side is actively working to eliminate the debt you already have. Using strategies like the debt snowball, where you pay off smaller balances first to build momentum, can give you both practical and emotional wins. 

5. Pay Yourself First (Save Before You Spend)

Most people spend first and save whatever is left over, but the truth is there’s rarely much left at the end of the month. The habit of paying yourself first flips that script and you make saving a priority by setting money aside as soon as you get paid, before you pay bills or buy anything else. 

This simple shift ensures that your goals, whether they’re building an emergency fund, investing for retirement, or saving for a dream, are always moving forward. 

6. Invest Consistently for the Long Term

Saving is important, but saving alone won’t make you wealthy, your money needs to grow and work for you. Investing consistently is how you turn today’s effort into tomorrow’s wealth. The key is to invest regularly, even in small amounts, and to focus on the long term rather than quick wins. 

The power of compound interest, where your money earns returns, and then those returns earn returns, works best with time and consistency. Whether you use retirement accounts, index funds, or other long-term investments, the habit of putting money into the market regularly helps you create a future where you’re not just surviving but thriving.

7. Diversify Your Income Sources

Relying on one single source of income, like a salary, can be risky, because if that source disappears, your entire financial stability shakes. Building multiple streams of income is a habit that creates resilience and builds a strong financial foundation. 

This could mean starting a small side hustle, freelancing, investing in rental properties, or building passive income sources like digital products or dividends. Even if each stream is small at first, together they give you more security and flexibility and over time, this habit helps you move from working only for money to having money work for you.

8. Plan for Retirement Early

Retirement may feel like it’s far away, especially if you’re young, but planning for it early is one of the smartest financial habits you can adopt. Time is your greatest ally because the earlier you start, the more your investments have years or even decades to grow. 

By consistently putting aside money into retirement accounts, you’re building not just a financial future but also independence and dignity. Without this planning, many people end up working much longer than they want to or depending on others. 

9. Track Your Spending Regularly

It’s easy to underestimate how much small purchases add up, and that’s why tracking your spending is such a powerful habit. By paying attention to where your money actually goes, you can uncover patterns and areas where you can adjust and alter your habits without feeling deprived. 

Tracking doesn’t have to be complicated, you can simply use an app, a spreadsheet, or even a notebook if you prefer to keep a tangible record. The point is awareness, because awareness leads to better decisions and when you track your spending regularly, you’re no longer blind to your habits, you’re in control of them.

10. Set Clear Financial Goals

Financial freedom doesn’t happen by accident, it requires direction and setting clear and specific goals to give your money a purpose. Whether your goal is to pay off debt, save for a home, build a business, or retire early, having a target keeps you motivated and focused.

Without goals, it’s easy to spend aimlessly and wonder why you’re not making progress. Goals give you a reason to say “yes” to some things and “no” to others, and they turn daily habits into a personalized and much more meaningful progress.

11. Keep Learning About Money and Finance

The world of money is always changing, from new technologies to evolving investment opportunities, therefore, building the habit of continuous learning can help keep you prepared and confident. This could mean reading books, listening to podcasts, following financial educators, or simply asking questions when you don’t understand something.

Knowledge empowers you to make better decisions and avoid costly mistakes because the more you learn, the less intimidating money feels, and the more control you gain over your financial future.

12. Practice Delayed Gratification

In a world where everything feels instant, such as shopping online, credit cards, or fast delivery, it’s tempting to spend impulsively. Practicing delayed gratification means pausing, waiting, and saving before you buy. 

It doesn’t mean you never get what you want, but it means you enjoy it even more when you’ve prepared for it. Over time, this habit not only saves you from debt but also helps you appreciate what you have because you earned it without financial stress.

13. Give Generously and With Purpose 

The final habit may surprise some people, but generosity is one of the most freeing financial practices you can adopt. When you give, whether it’s to family, friends, charities, or causes you believe in, you break the grip that money can sometimes have over your heart.

Generosity brings joy, builds community, and creates a sense of fulfillment that no bank balance can match. Giving generously doesn’t require you to be rich, it only requires you to share what you can with intention, care, and love.

Conclusion

Financial freedom is about building a life where money is no longer your constant source of stress but instead becomes a tool that helps you create stability, opportunities, and joy. These 13 habits, when practiced consistently, can transform the way you think about and use money. The journey takes patience and discipline, but every small choice adds up over time and when you’ll look back, you’ll realize that financial freedom is not just about money, it is about peace of mind, independence, and the ability to live and give in ways that truly matter.
7 Baby Steps To Financial Freedom

September 19, 2025 By Ana Rose

Financial freedom is something that almost everyone dreams of but a very few of us manage to achieve it. For some people, the idea of financial freedom may be too big, for example, some may think that financial freedom is reserved for those with high-paying jobs or family wealth, but the matter of fact is that financial freedom isn’t about luck or overnight success, it’s about small and steady steps that create a strong foundation over the course of time. The beauty of baby steps is that it breaks down complex and complicated procedures into simple and understandable chunks, helping people follow and stay consistent with the process. This article will help you explore 7 baby steps to financial freedom, helping you take control of your finances and giving you the ability to live life on your own terms and conditions.

7 Baby Steps To Financial Freedom Graphic


Step 1: Build a Starter Emergency Fund

The very first step on the journey to financial freedom is to put aside a small emergency fund, usually around one thousand dollars or whatever amount feels realistic in your situation. This little cushion is not meant to cover every possible disaster but rather to give you some breathing room when life throws those smaller and very common surprises. 

Having even a small emergency fund helps you avoid falling into that cycle, because instead of panicking, you know you have something to rely on, and that brings a sense of confidence and calm that makes a huge difference. 

To gather this starter fund quickly, you might need to cut back for a while by cooking at home instead of eating out, selling items around the house that you no longer use, or picking up a small side hustle just to speed things up, because the goal here is not to be perfect but to take action fast. Once you set aside that small amount, you’ll notice the pressure easing, and you’ll be able to move forward without constantly living in fear of the unexpected.

Step 2: Pay Off All Debt (Except Your Mortgage)

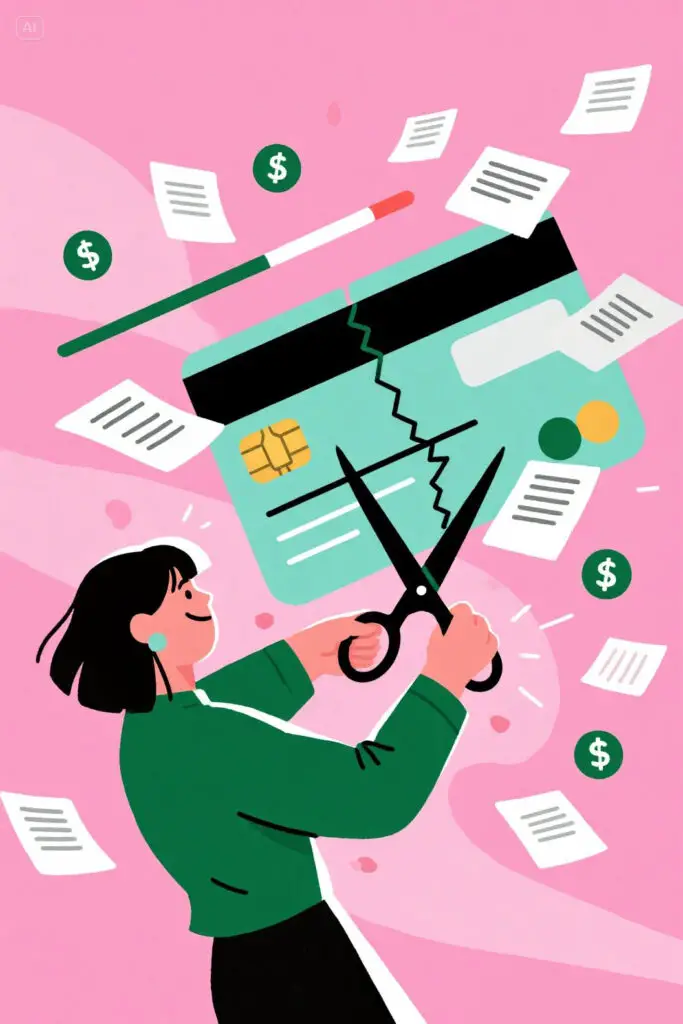
A woman cutting a giant credit card in half with scissors, as loan documents and bills dissolve into dust. The pastel pink background features bright green dollar icons and a glowing progress bar, symbolizing freedom from debt.

Debt is one of the biggest obstacles when it comes to financial freedom because things like credit cards, car loans, and personal loans quietly take a big portion of your paycheck before you even get the chance to enjoy what you have earned. A very practical way to do this is the debt snowball method, which simply means you line up all your debts from the smallest balance to the largest. This approach works so well because it gives you visible progress, and with each debt cleared you feel a rush of motivation that makes you believe you can keep going, which is often more powerful than the math itself. 

Debt is not only about numbers on paper, it carries an emotional weight that limits your choices, puts stress on relationships, and can even keep you stuck in jobs you don’t love simply because you need the paycheck to keep the payments going. 

Step 3: Build a Fully Funded Emergency Fund

Once you have freed yourself from the weight of debt, the next step is to create a much stronger safety net by building a fully funded emergency fund that can cover three to six months of your living expenses. With this cushion in place, you no longer have to live in survival mode, always worrying about what might go wrong, because you know you are protected against the bigger unfortunate situations that life can bring, such as losing a job, facing medical emergencies, or even going through an unexpected crisis that could shake your stability. 

This fund acts like a shield that stops panic from taking over when something major happens, because instead of scrambling for solutions, you already have a plan built into your finances.

 It may not be an exciting step like investing or buying assets, but it is the strong protective wall around everything else you are working so hard to build, and that peace of mind is priceless.

Step 4: Invest for Retirement

After you have created a strong sense of security with your emergency fund, the next step is to shift your focus from protecting what you have to building real wealth for the future, and this is done by setting aside around fifteen percent of your income for retirement. Even though retirement might feel like something far away, the truth is that time is your greatest friend when it comes to investing, because the earlier you begin, the more years your money has to grow. 

By consistently putting a portion of your income into retirement accounts such as a 401(k), an IRA, or a pension plan depending on what is available in your country, you are allowing your money to quietly multiply in the background over the decades. 

Without retirement savings, many people are forced to keep working past the age when they would prefer to slow down, or they end up relying on family members or government assistance just to get by. By starting early and being consistent, you are building a future where you get to decide how your days are spent, where money is no longer a master but simply a tool that gives you freedom to live the life you choose.

Step 5: Save for Children’s Education (If Applicable)

If you are a parent, one of the greatest gifts you can give your children is the chance to step into adulthood without the heavy burden of student loans or education debt weighing them down, and that is exactly what step five is about. The cost of schooling and higher studies is rising everywhere, and many families end up facing the painful choice of either sacrificing their own financial goals or allowing their children to borrow large amounts of money that will take years, even decades, to pay back. 

By starting early, even if it’s with small amounts, you can build an education fund over time that grows steadily and provides a head start for your children when they need it most. Whether you are doing it for your children or for yourself, this step is about planting seeds for the future so that opportunities are easier to reach and financial struggles never stand in the way of education and growth.

Step 6: Pay Off Your Home Early

A smiling family stands in front of their cozy home with a bold red “PAID” stamp across the roof. The pastel pink background includes golden sparkles and upward arrow highlights, representing security and financial freedom.

For many families, a mortgage is the single biggest bill they face each month, and while people often call it “good debt” because it is tied to an asset like a home, the truth is that it still takes away a large part of your income and keeps you tied to the bank for decades. Step six is about breaking free from that long-term burden by paying off your home early, and while it may sound ambitious at first, the feeling of security and freedom it brings is worth every bit of effort.

The way to get there is through steady, intentional actions like making extra payments toward the principal whenever you can, rounding up your monthly payments so that a little more goes toward the balance, or using bonuses, tax refunds, or any unexpected income to chip away at the loan. 

Once the debt is gone, your cost of living drops dramatically, and that means more freedom in retirement, more flexibility in your choices, and more peace knowing that your home is a safe and permanent place for your family. 

Step 7: Build Wealth and Give Generously

This step is not about survival or even stability anymore, it is about growth, impact, and joy where you can invest more confidently in areas like real estate, businesses, or the stock market, letting your money work for you and multiply over time. However, wealth is not only about the numbers in your accounts, it is also about the ability to share what you have with others. 

When you give from a place of abundance, whether it is helping a family member in need, supporting causes close to your heart, or simply blessing someone who is struggling, you experience a kind of happiness and fulfillment that money alone can never buy. 

Conclusion

Reaching financial freedom does not happen overnight, and it certainly is not always easy, but by following these simple baby steps in order, you can slowly but surely move from a place of stress and struggle to a life built on peace, stability, and confidence. Each step has a purpose and together they create a clear path that anyone can follow, no matter what their income or starting point may be. The journey requires patience and consistency, but every effort brings you closer to a future where you are no longer tied down by money but are instead free to enjoy the life you have worked so hard to build. 

How To Be Great At Investment For Future

September 18, 2025 By Ana Rose

Investment can feel intimidating, especially when you’re in the initial phases of the process. There are countless terms and opinions that make investment feel daunting and like it’s only meant for the wealthy and finance experts, but the truth is that investing is simply the process of putting your money to work so that it grows over time, instead of sitting idle in your bank account. Whether your goal is to retire comfortably, buy a home, or something as simple as not having to worry over finances, learning how to invest can be one of the wisest skills you can build. This article will help you explore how to invest so that in the longer run, you don’t only become financially stable and free, but you also figure out ways to make that money work for your greater good.

How To Be Great At Investment For Future Graphic

Step 1: Build a Strong Financial Foundation

Before you get to investing, it’s essential to strengthen your financial foundations. You can start by building an emergency fund which can include three to six months’ worth of living expenses, set aside in a separate yet easily accessible savings account.

Once you’re done with building an emergency fund, now focus on repaying your debts. You can start by paying down high-interest debt like credit card balances because the interest you pay is likely higher than any return  you’d earn from investing. 

Finally, create a simple budget that aligns well with your income, lifestyle, and spending habits. You can go with classic budgeting technique 50/30/20 rule, where 50% of your income goes to your essential expenses such as paying rent, bills, or groceries. 30% of your pay goes to non-essential expenses such as hanging out with friends, takeouts, or subscriptions you barely use, and lastly, 20% of your income goes straight to your savings. You can also opt for the envelope budgeting method where every single dollar serves a purpose. Envelopes are made with a specific amount put into each with the category’s name written on front. The catch is to stay within the limit and stop spending on a specific category once you run out of money in the envelope. 

Step 2: Learn the Basics of Investing

Investing can feel overwhelming at first but you don’t need to become a finance expert to succeed. You can start by understanding the key terms such as stocks represent ownership of companies, bonds are loans you give to the government or cooperations, and funds like mutual funds or ETFs bundle many investments together for easy diversification. 

You can learn about risk versus reward and how different assets are like over time. The more you understand these basics, the more confident you’ll feel and you’ll be less likely to panic when the market shifts.

Step 3: Define Your Goals and Timeline

Investing isn’t one-size-fits-all, because your goals shape the journey ahead. If you’re saving for retirement 30 years from now, you can afford to take on more risk with stocks because you have time to recover from market shifts but if your goal is to buy a house in the next 5 years, you’ll want safer and more stable investment options.

Clarity and direction regarding your goals and timelines gives your investing a purpose and helps you make better decisions without having to second-guess yourself every time there’s a shift in the market. 

Step 4: Embrace Long-Term Thinking

The stock market will rise and fall and it can feel tempting to react to every bump along the way but one of the golden rules of investing is patience. Instead of trying to “time the market” or chase quick wins, focus on staying invested for the long haul. 

Over decades, the market has historically trended upward, rewarding those who hold steady. By thinking long-term, you allow compounding to work in your favor. The earlier you start and the longer you stay in, the more powerful this effect becomes.

Step 5: Diversify Your Investments

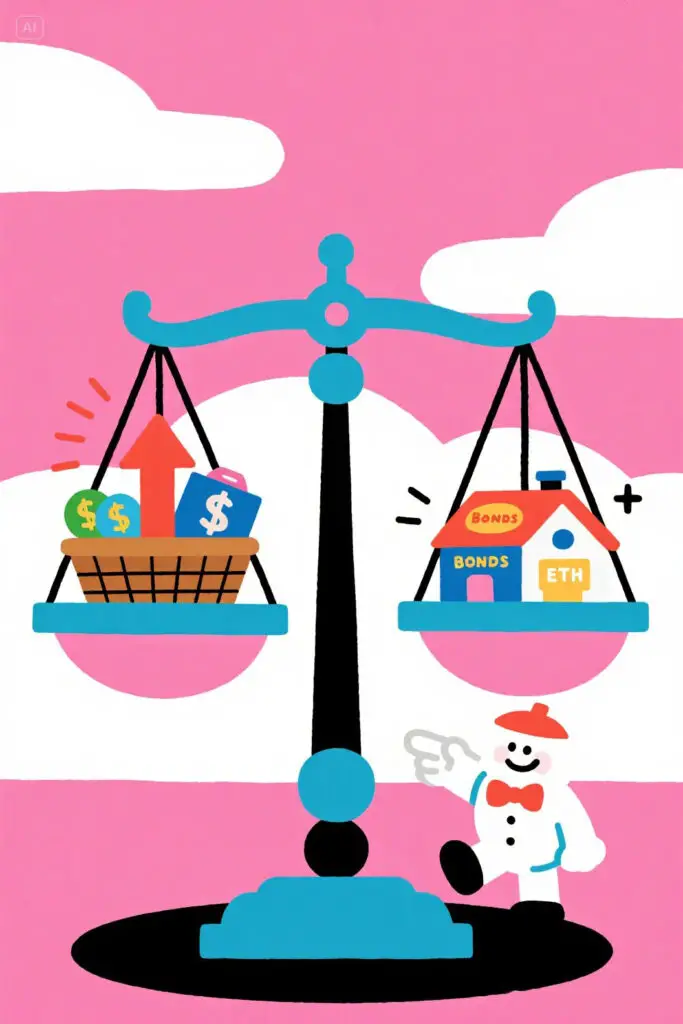
Flat digital illustration of a balanced scale with stocks on one side and bonds, real estate, and ETFs on the other. A smiling character points to the scale, symbolizing diversification. Pastel pink background with a calm, positive investing theme.

Diversification simply means spreading your money out instead of keeping it all in one place. You can put some in stocks, some in bonds, some in real estate, and even spread it across different industries and countries. This way, if one area of your experiment isn’t doing so well, there’s a good chance another part is doing fine or even growing, and that balance helps protect you. 

Diversification doesn’t mean you’ll never face risk, because investing always carries some level of uncertainty, but it does mean you won’t be relying on one single outcome. Over time, this approach gives your money a smoother and stable path to grow, and it brings you peace of mind knowing that one bad situation won’t completely undo all the effort you’ve put into your financial future.

Step 6: Keep Costs Low

When it comes to investing, many people focus only on how much their money might grow, but they often overlook how much they’re paying just to stay invested. The truth is, investment fees and charges might look small on paper, maybe 1% or 2% but over years and decades, those little percentages quietly eat away at your profits. 

This is why choosing low-cost options, such as index funds or ETFs, is such a smart move as they give you access to a wide range of investments at a fraction of the cost of actively managed funds. The less you pay in fees, the more of your hard-earned money stays in your account, working for you and compounding over time. 

Step 7: Automate Your Contributions

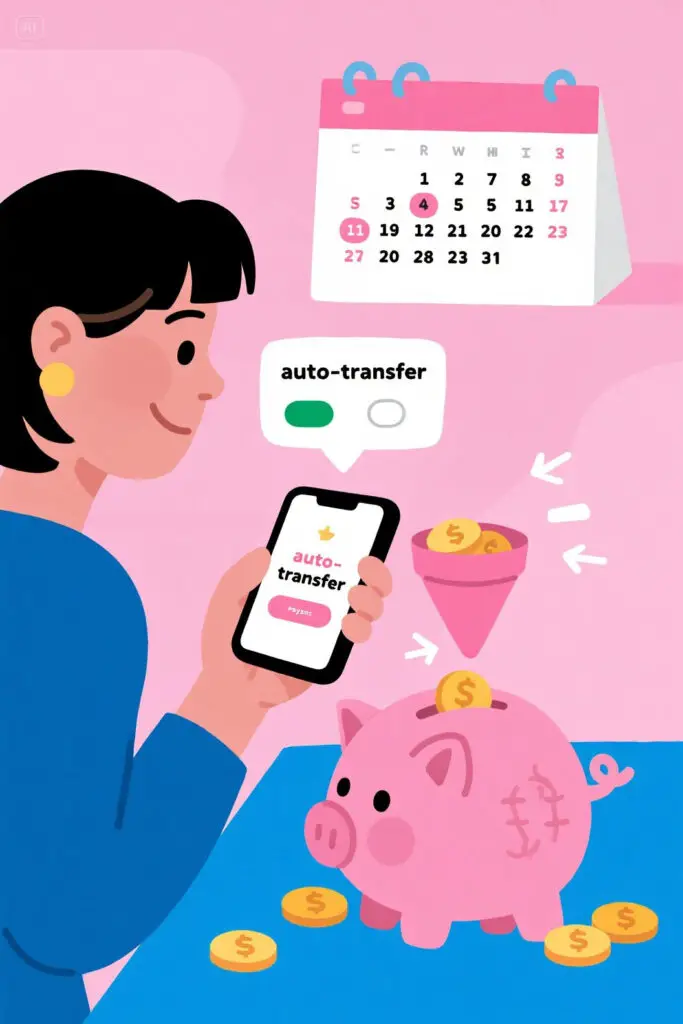
Flat digital illustration of a woman enabling auto-transfer on her phone while coins flow automatically into a piggy bank. A calendar with recurring marks is shown in the background, symbolizing consistency. Soft pastel pink background for a simple and reliable investing mood.

One of the biggest secrets to successful investing isn’t about picking the perfect stock or timing the market, it’s about consistency and the best way to stay consistent is to take the decision-making out of your own hands and automate the process. 

By setting up automatic contributions from your paycheck or bank account into your investment account, you make sure that money is being invested regularly without you having to remember or overthink it. This approach, often called dollar-cost averaging, means you’re buying a little bit whether prices are high or low, and over time it smooths out the ups and downs of the market. Automation also protects you from the temptation to skip a month or spend that money elsewhere. 

Step 8: Avoid Emotional Decisions

Money has a way of stirring up our emotions, and when it comes to investing, those emotions can lead us into trouble. Emotional decisions might feel right in the moment, but they usually end up costing you. 

Great investors learn to step back, breathe, and remind themselves that investing is a long game. The market will always have ups and downs, but if you stay calm and stick to your plan, you give your money the time it needs to recover and grow. Avoiding emotional decisions doesn’t mean ignoring your feelings, it means training yourself to act on logic and strategy instead of fear or hype.

Step 9: Keep Learning and Stay Curious

Investing isn’t something you figure out once and then forget, it’s a journey where staying curious pays off. Keep an open mind and pay attention to timeless lessons like patience, diversification, and compounding, rather than chasing every new trend that pops up in the headlines. 

Being curious also helps you see investing as an opportunity to grow, not just your money, but your knowledge and mindset too. The more you understand, the less intimidating the process feels, and the easier it becomes to stay committed for the long run.

Step 10: Review and Adjust Regularly 

Investing isn’t something you set up once and never look at again, it’s a living plan that needs attention as your life changes. Checking in on your investments once or twice a year helps you make sure they still match your goals, your risk comfort, and your timeline. For example, if you’re young and saving for retirement, you might be comfortable with more stocks but as you get closer to retirement or a big financial goal, shifting some money into safer options like bonds makes sense. 

You might also find that your income has grown, giving you the chance to increase your contributions. These reviews don’t have to be complicated or frequent, but they keep you in control, making sure your investments are always aligned with the life you’re building. 

Conclusion

Becoming great at investing for the future isn’t about finding shortcuts, predicting the market, or chasing the next big thing, it’s about building steady habits that grow stronger over time. When you lay a solid foundation, keep your costs low, stay consistent, and let patience guide you, you put yourself miles ahead of the average investor. Even small and regular steps can lead to big results when you give them years to compound. So instead of worrying about doing everything flawlessly, focus on staying consistent, curious, and calm through the ups and downs. 

2 Week No Spend Challenge

September 17, 2025 By Ana Rose

Sometimes our spending habits tend to run on autopilot, whether it’s grabbing coffee everyday before going to work, ordering takeout when we’re tired, or adding products to your online cart because we’re tempted to buy it. While these small purchases may seem harmless at the moment, they add up quickly and eventually we’re left behind wondering where all our money went. A short-term reset like a 2-week no spend challenge, gives you a chance to pause, reflect, and reset your financial habits, helping you regain control over your impulses and finances while also giving you space to think and make intentional spending choices when it comes to money.

2 Week No Spend Challenge

What the Challenge is All About

Illustration of a woman smiling while holding a piggy bank, set against a pastel pink background. A calendar marked “14 Days” is displayed, with icons of shopping bags, coffee cups, and takeout meals crossed out. Around her, icons for essentials like groceries, rent, utilities, and bills are highlighted.

A two-week no spend challenge is exactly what it sounds like, for fourteen days you make an intentional decision to spend only on the basic essentials and hit pause on everything else. This means the bills still get paid, groceries still come home, and any real necessities are covered, but all the extras such as shopping, eating out, new gadgets, or that daily coffee runs are put on hold. 

It can be thought of as a mini financial detox or a short break where you spend only on the basics and give yourself space to notice your habits. It’s a way to prove to yourself that you can live with less, find joy in what you already have, and start looking at your spending through a clearer and more mindful approach.

Why Two Weeks is the Perfect Timeframe

Illustration of a large hourglass with 14 blocks of sand, each labeled for a day in the two-week challenge. On the left side, a person appears stressed carrying shopping bags and takeout boxes. On the right side, the same person looks calm and happy holding a savings jar. Background in soft pastel pink with light highlights.

Some people try a month-long no spend challenge, but for beginners that can feel overwhelming and difficult to follow. Two weeks strikes the perfect balance as it’s short enough that you can see the end in sight and not feel deprived, on the other hand, it’s also long enough to experience meaningful results. 

Fourteen days is plenty of time to break the cycle of impulse spending, to build new habits, and to watch your savings add up in a noticeable way. It’s also realistic because anyone can commit to just two weeks of change without feeling like they’re cutting themselves off from life for too long. Moreover, knowing that it’s temporary makes it easier to push through tough moments and you’re much more likely to stay strong and stay consistent with the process.

Setting Your Ground Rules

Every successful challenge needs clear boundaries otherwise you’ll find yourself debating with your own willpower when temptation shows up. Before you begin, sit down and define what essentials mean to you. For most people, this includes housing costs, utilities, groceries, necessary transportation, and medical expenses. 

What matters is that you’re honest with yourself about where you tend to overspend and set rules that address those areas. By writing these down ahead of time, you take the pressure off your future self, because when temptation comes, the decision has already been made.

Preparing Before You Begin

Preparation makes all the difference to help you through the challenge and staying committed to it. Start by looking at what you already have by checking your pantry, freezer, and fridge, and creating a meal plan around those items so you won’t feel the need to run out and shop unnecessarily. 

Take inventory of your household supplies such as things like toiletries, cleaning products, or laundry detergent and restock anything that might run out mid-challenge so you’re not forced into a shopping trip. Moreover, If you have subscriptions or recurring payments you don’t actually need for the next two weeks, you can consider pausing or canceling them. Preparation isn’t about spending more before you start, it’s about setting yourself up so you can focus on the challenge without feeling unprepared or frustrated.

Identifying Your True Essentials

One of the most eye-opening parts of the no spend challenge is learning what truly counts as a need in your life. Essentials are the things you simply cannot function without such as your rent or mortgage, electricity and water, groceries that keep you nourished, and transportation that allows you to get to work or school. 

Beyond these expenses, a lot of what we spend on falls into the “wants” category, even if we’ve grown used to treating them as needs. For example, grabbing takeout might feel like a necessity on busy nights, but when you’re in challenge mode, you start to see that a quick, simple homemade meal can fill the gap just as well. 

This realization is powerful because once you separate true essentials from nice-to-haves, you gain perspective on where your money is actually going and how much freedom you have to redirect it toward things that matter more.

Finding Free Alternatives to Spending

The first few days of cutting out extra spending can feel a little dull and you may suddenly realize how often you rely on shopping or entertainment that costs money. But this is also the fun part, because it pushes you to get creative and rediscover the free or low-cost joys you may have forgotten. 

Instead of going to the movies, host a cozy film night at home with what you already own. Instead of paying for a night out, invite a friend for a long walk or a game night. Instead of browsing stores online, dive into a book you’ve been meaning to read, reorganize a corner of your home, or pick up an old hobby. 

Many people come out of the challenge realizing that the things that brought them the most joy during those two weeks were completely free, and that shift can change your relationship with spending long after the challenge ends.

Staying Motivated During the Challenge

There will be moments when temptation hits hard, and that’s perfectly normal. Maybe you’re scrolling online and see a big sale, or you’re having a tough day and craving takeout, or your friends are going out and you feel the urge to join. Staying motivated means reminding yourself why you started in the first place.

Some people also find it motivating to track their “would-have-spent” amounts, writing down how much money they avoided spending each day, and watching the total grow. When you see in black and white that you’ve saved $100, $200, or more in just two weeks, it can give you the motivation and energy to keep going.

Tracking Your Progress and Savings

Nothing keeps you motivated quite like seeing results, and tracking your progress is key. Each time you skip a purchase, whether it’s avoiding that morning latte or saying no to an impulse buy online, write down the amount you didn’t spend and at the end of each week, add it up. 

By the end of the challenge, you’ll likely be shocked at the total savings, because it’s money that would have slipped away without you even noticing. Having this tangible record doesn’t just make the challenge feel rewarding, it also gives you proof that your small daily choices add up to something much bigger.

Common Challenges and How to Overcome Them

You might feel bored without your usual entertainment, frustrated when you can’t order your favorite meal, or even tempted to give up halfway. If boredom is your weak spot, write down a list of fun, free activities you can turn to, if online shopping is your habit, unsubscribe from marketing emails and remove shopping apps from your phone for two weeks, and if eating out is your comfort, try prepping quick, comforting meals at home so you’re not left empty-handed. By planning ahead for your weak points, you make it easier to stay on track when temptation shows up.

Benefits You’ll Notice Right Away

The most exciting part of this challenge is how quickly the benefits show up. Within days, you’ll notice extra money in your account and a sense of relief that you’re not spending constantly. You may also feel calmer, because you’re not caught in the cycle of wanting and buying. 

Many people even discover hidden creativity such as experimenting with meals from pantry staples, finding joy in free activities, or learning to make the most of what they already own. 

Conclusion

The 2 Week No Spend Challenge isn’t about saying no to fun or joy, it’s about saying yes to control and intentional living. By hitting pause on non-essential spending for just fourteen days, you give yourself the chance to break old habits, discover new joys, and watch your savings grow in ways that surprise you. When it’s over, you may go back to some of your usual routines, but you’ll do so with fresh perspective and more awareness of where your money is going. It’s a small, temporary challenge that can create a lasting shift in how you view spending, and once you experience that freedom, you may find yourself coming back to this challenge again whenever you need a reset.

Financial Planning For Women

September 14, 2025 By Ana Rose

Financial planning isn’t just about having big numbers in your bank account, it’s about building security, independence, and freedom to make your own choices in the future. For women the importance of financial planning can not be denied because they often face unique challenges such as career breaks, lower lifetime earnings due to wage gaps, and balancing family responsibilities alongside personal goals. This is why having a clear, realistic, and relevant financial plan is essential to help women build financial freedom and security with confidence. This article will help you explore the complex dynamics of financial planning for women that not only supports their present needs but also safeguards their future. 

Financial Planning For Women Graphic

Understanding Your Financial Situation

Before you begin planning, you need to truly understand where you stand right now, because without knowing your current situation it becomes almost impossible to make plans for the future. This means taking a close look at your income, your monthly expenses, any debts you owe, and the savings or assets you already have. 

Many women are used to managing household budgets or taking care of family needs but often forget to check in on their personal financial health, so taking time to review your bank statements or your spending patterns can give you a clear starting point and help you feel more in control.

Setting Clear Financial Goals

Once you know your present situation, the next step is to set goals that are realistic and meaningful for you, because without goals your money doesn’t have direction and it can easily get spent on things that don’t add value to your life. 

Your goals may look different depending on your stage of life, for example saving for a car, buying your own home, paying for your children’s education, or building a retirement fund, but what matters is that you put those goals into words and even break them into plans. Having clarity on why you are saving and what you are working towards makes financial planning much easier to follow and motivates you to stay consistent.

Budgeting and Expense Tracking

Budgeting may sound boring or strict but in reality it is simply a way of telling your money where to go instead of wondering where it went at the end of the month, and this is especially important for women who often balance family responsibilities alongside personal goals. 

By creating a simple monthly budget and tracking your expenses, you can identify which areas take up most of your money and where you can cut down without affecting your quality of life.

Building a Strong Emergency Fund

A woman with long dark brown hair places coins into a transparent glass jar labeled Emergency Fund, with dollar bills inside, against a pastel pink background with shield and heart icons representing protection.

Life can be unpredictable and challenges come when we least expect them, whether it is a medical emergency, a sudden job loss, or a household repair, and in such moments having an emergency fund acts like a shield that protects you from stress and debt. 

A good way to build this fund is by saving little by little until you have at least three to six months’ worth of living expenses tucked away in an account that is easy to access but separate from your everyday spending money.

Managing Debt Wisely

The key is not to ignore debt but to face it with a plan, such as paying off the smallest amounts first to build confidence or tackling the highest interest debts to save money in the long run. 

Making regular payments, avoiding unnecessary borrowing, and tracking progress can slowly but surely bring you to a debt-free life, and with each loan paid off you gain more control and freedom over your finances.

Saving vs. Investing 

While saving money is essential to cover short-term needs and emergencies, relying on savings alone is not enough because inflation reduces the value of money over time, and this is where investing becomes important. Investing allows your money to grow and work for you, whether through stocks, mutual funds, real estate, or retirement accounts, and even small amounts invested regularly can grow significantly.

Retirement Planning for Longer Life Expectancy

Women on average live longer than men, which means they need to plan for more years of retirement, and this makes saving for retirement not just important but absolutely necessary. It is easy to delay retirement planning when there are more immediate responsibilities like children or household expenses, but the earlier you start the easier it becomes to build a comfortable retirement fund.

Whether you have access to employer-sponsored retirement plans or need to set up your own individual savings account, make sure to contribute regularly, and remember that retirement savings is not an expense but a gift to your future self.

Insurance and Financial Protection

Insurance is often overlooked but it is one of the strongest pillars of financial planning because it protects you and your family from unexpected financial burdens. Health insurance ensures medical costs do not drain your savings, life insurance provides security to your loved ones if something happens to you, and disability insurance can protect your income if you are unable to work. 

For women who are often the primary caregivers in their families, having the right protection means having peace of mind that no matter what happens, their families will not be left struggling.

Career Breaks and Family Planning Considerations

A woman sits at a desk with a laptop, balancing a baby stroller on one side and a stack of coins with a calendar on the other, on a pastel pink background with faint clock and family icons.

Many women take career breaks for reasons like raising children, taking care of parents, or relocating due to a partner’s job, and while these decisions are meaningful and valuable, they also affect long-term financial growth and savings. Planning ahead for these breaks by building extra savings, keeping skills updated, or exploring flexible work options can reduce the financial impact. 

Financial Independence and Security

The most powerful part of financial planning for women is the sense of independence it creates, because when you have your own savings, investments, and financial stability, you are free to make choices based on your own values and not just out of financial necessity. Financial independence is not about being rich but about being confident that you can handle your needs and make decisions for yourself and your family without fear.

Wealth Building Through Smart Investments

Beyond just saving for goals, women should also focus on building wealth over time, because wealth is what provides long-term freedom and stability. Smart investments such as real estate, stocks, or starting a small business can help create multiple streams of income, and while it may feel intimidating at first, learning step by step and seeking advice makes the process more comfortable. 

Estate Planning and Protecting Your Legacy

Estate planning may sound like something only for the wealthy, but in reality it is important for every woman because it ensures that the assets you work so hard for are passed on according to your wishes and without unnecessary stress for your loved ones. 

Creating a will, designating beneficiaries, and understanding inheritance laws are all part of protecting your legacy, and these steps make sure your children or dependents are taken care of in the future. 

Seeking Professional Financial Advice

Sometimes financial planning can feel overwhelming, especially when there are so many options and decisions to make, and in such cases seeking guidance from a financial advisor can be very helpful. 

A professional can help you design a plan that matches your goals, risk level, and income, and they can also point out areas you may have overlooked. For women who may not always feel confident discussing money, having someone to guide them can bring clarity and confidence, and over time you will learn enough to make informed choices independently.

Empowering Yourself Through Financial Education

The best tool for financial planning is knowledge, because when you understand how money works you no longer feel afraid or dependent on others for every decision. Financial education doesn’t mean formal courses only, it can be as simple as reading books, following trusted financial blogs, or attending workshops that teach you about budgeting, saving, investing, and planning for the future. 

Conclusion

Financial planning for women is not a one-time task but a lifelong journey that grows with you, your family, and your dreams, and while it may seem overwhelming at first, every small step you take today brings you closer to the life of independence, security, and freedom you deserve. By understanding your situation, setting clear goals, saving and investing wisely, and protecting yourself with insurance and estate planning, you create not just financial stability but also the confidence to live life on your own terms. 

  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 27
  • Go to page 28
  • Go to page 29
  • Go to page 30
  • Go to page 31
  • Interim pages omitted …
  • Go to page 73
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers