• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

Blog

Zero Based Budget and Financial Planning: A Step-by-Step Guide

November 4, 2025 By Ana Rose

If you’ve ever wondered why your money disappears so quickly even when you’re being careful, the zero-based budgeting method can give you a clear and structured plan that helps you see where every single dollar or penny goes. The zero-based budgeting method is not about being restrictive or holding back on all the fun, it’s about giving your money direction and purpose, knowing exactly where it goes instead of wondering where it all went at the end of the month. This plan can help you spend with intentions, making sure nothing is left unaccounted for and that your money is actually working for you, not against you. This article will help you explore the dynamics of zero based budgeting method, making sure your finances feel simple, doable, and effective. 
Zero Based Budget and Financial Planning: A Step-by-Step Guide

What Is Zero-Based Budgeting

Illustration of a woman planning her monthly budget at a desk with a laptop and floating money icons on a pastel pink background, symbolizing the concept of zero-based budgeting and financial organization.

The zero based budgeting method is all about planning your finances at the start of the month. This method includes starting with your total income and assigning every dollar a meaning and purpose until there;s nothing left behind. 

This doesn’t mean you spend every penny right away, it just means you plan your spendings, whether it’s for groceries, bills, utilities, or even for savings. The main catch of this method is simply being more intentional and planning more responsibly for your finances, instead of spending it without any directions. It can also give you a clearer picture of how much you can really spend, save, or invest, all while helping you feel more in control. 

Why the Zero-Based Method Works So Well

The reason why this method works the best for many of us is that it promotes logical reasoning and problem solving, allowing you to be fully aware of our decisions and their consequences, rather than relying solely on guesswork. 

Every time you earn, you can tell your money where to go, which means there’s no room for impulse purchase or careless spending. Moreover, this method isn’t only limited to organizing your finances, it also gives your sense of calm and peace of mind, knowing there’s no uncertainty when it comes to your hard-earned money. 

Step 1: Calculate Your Real Income

The first and most important step when you step into zero-based budgeting is calculating your real income. You need to have an exact figure, after all the taxes and deductions, called the net income, which is your take home pay. 

This can include your salary, freelance gigs, side hustles, or any other source of income. When you start working with the figure coming in every month, the process can feel a bit more realistic, helping you stick to the budgeting method and making it work for you rather than beginning with an unrealistic figure. 

Step 2: List All Your Monthly Expenses

Once you understand your income, the next step is to list all your monthly expenses, no matter big or small. You can start with those fixed expenses like bills, rent, or loans and then move on to the variable ones like groceries, gas, or entertainment. 

Once you list down these expenses, it is important to include those occasional expenses as well including subscriptions, gifts, or holiday costs, because those small things often add up quickly and eat away most of your income. 

Step 3: Assign Every Dollar a Purpose
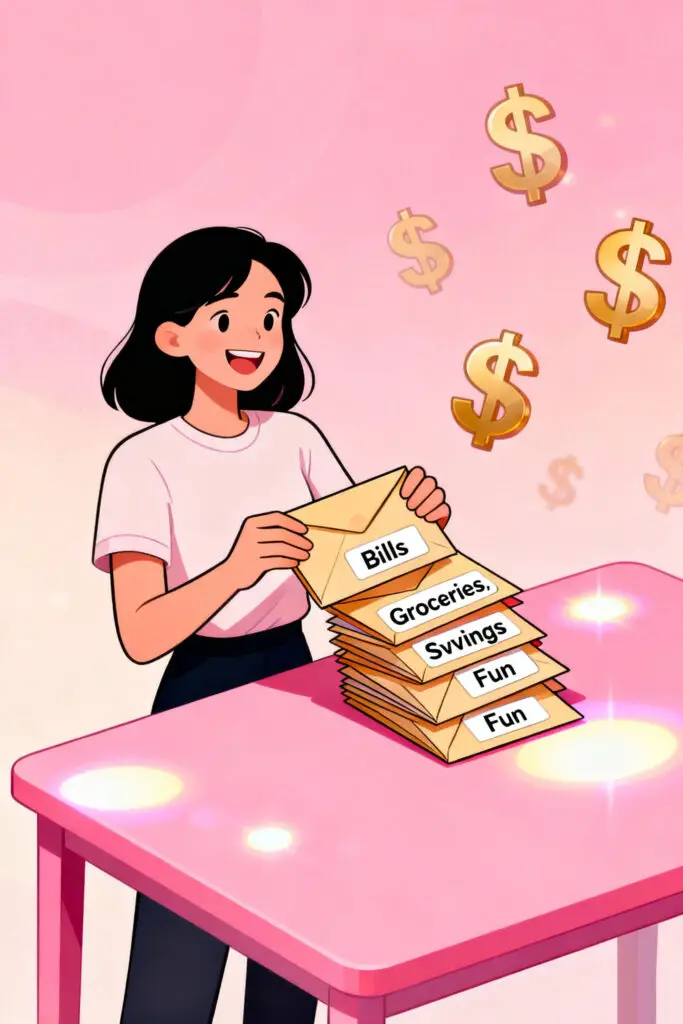
Illustration of a woman organizing envelopes labeled with spending categories on a pastel pink background, representing assigning every dollar a purpose in zero-based budgeting.

Once you’re done with income and expenses, the next and the main part of zero based budgeting is assigning every dollar a purpose. You can start by covering your essential expenses such as housing, groceries, utilities, or transportation, and once you’re done with that, plan for savings, debt repayments, investments, or personal spending. 

Keep assigning money to these categories until there’s nothing left behind unplanned, and this way, you can have a structured and organized way to plan your finances.  

Step 4: Track Your Spending Through the Month

The next step is to track your spending throughout the month. This means keeping a check on your expenses, what you spend on, and how much you spend on it. If you prefer a digital approach you can use budgeting apps that help you track your spending, create a spreadsheet, or simply use a notebook and write your spendings down. 

This step is not about judging your spendings, it is more about controlling every little move while staying aware of your spending habits. When you keep checking in, you can notice small leaks or overspending habits before they put your entire budget off track. 

Step 5: Adjust and Rebalance When Needed

Life doesn’t always go as planned which is exactly why it is essential to adjust and rebalance whenever needed. If you notice that you spend a little more on one category, adjust the budget by taking some of the amount from that category to another meaningful one. 

For example, if you notice that you spend more on groceries than you should, a smart way would be to reduce the spending amount for groceries and readjust that amount in another meaningful category such as savings. The main idea of this step is to maintain balance and make small adjustments in order to ensure the effectiveness of the whole budgeting method. 

Step 6: Include Savings and Debt Payments as Expenses

Many people make the mistake of treating savings as something that comes after spending, but in the zero-based budgeting method, savings are treated as an actual expense, something that must be planned for from the very start. When you create your budget, write down savings and debt repayments just like you would list your bills or groceries. 

This helps you make saving and paying off debt a natural part of your financial routine instead of something you try to fit in later. 

Step 7: Create an Emergency Fund

An emergency fund is one of the most important parts of financial stability because life is full of unexpected moments that can throw your plans off track like medical bills, car repairs, or sudden job changes. Having a small emergency fund helps you handle these situations without needing to borrow money or use your credit card. 

Start with a small goal, such as saving enough to cover one month of expenses, and then slowly build it up over time until you have three to six months’ worth saved. 

Step 8: Review Your Progress Every Month

Budgeting isn’t something you set once and forget about, it’s a habit that gets stronger the more you practice it. At the end of each month, take a few minutes to review how you did. Look at where your money went, which areas you stayed on track with, and where you might have overspent. 

This isn’t about being hard on yourself, it’s about learning and improving little by little. Maybe your needs changed, or maybe you realized one category needs more money next month, that’s completely okay. 

Step 9: Use Simple Tools to Stay Organized

You don’t have to be a financial expert or use complicated software to manage your budget. There are many easy tools that can help you stay organized without making the process stressful. You can use budgeting apps, spreadsheets, or even a notebook and pen if that feels more comfortable. 

What matters is that you’re keeping track of your money in a way that makes sense to you. Some people like using cash envelopes for certain categories, others prefer using digital trackers, there’s no single right way. Choose what feels the easiest and most natural because the simpler it is, the more likely you’ll keep doing it.

Step 10: Stay Patient and Keep Going

The truth about budgeting is that it takes time to get used to, and you might not get it perfect in the first few months, and that’s completely normal. You might make small mistakes, forget to record an expense, or spend too much one week, but what matters is that you keep trying and adjusting. 

Over time, budgeting becomes a habit, and you’ll start seeing how much more confident and in control you feel about your money. Being patient with yourself is just as important as being consistent with your budget. 

How Zero-Based Budgeting Helps You Plan for the Future

One of the best parts of using the zero-based budgeting method is how it changes the way you look at your future. When every dollar has a clear purpose, you begin to understand your financial habits and priorities better. 

You’re not just spending randomly anymore, you’re making thoughtful choices that align with your long-term goals. Over time, this method helps you build a stronger foundation, where you can start planning for bigger dreams like buying a home, starting a business, or retiring comfortably. You stop feeling like your money is controlling you and instead start feeling like you’re the one in charge, guiding it exactly where you want it to go.

Conclusion

Zero-based budgeting might sound like a lot of work at first, but once you understand the concept behind it, it starts to feel easy and doable. It’s not about strict limits, it’s about giving your money a clear purpose and making sure it serves your needs and goals. By tracking, planning, and adjusting each month, you build financial habits that make your life easier, calmer, and more organized. The most beautiful part of this method is that it grows with you and as your income changes or your goals evolve, your budget adapts too. Step by step, you’ll find yourself feeling more confident, more mindful, and more in control of your money than ever before.
Budgeting Tips For Beginners: How To Start A Budget That Actually Works

November 3, 2025 By Ana Rose

Budgeting may sound boring to people until they realize how much power it gives to them when it comes to controlling their money. Budgeting can help you understand where your hard-earned money is going, allowing you to take mindful and measured decisions. Budgeting is not about cutting every fun thing out of your life, it is about understanding what you earn, what you spend, and how you can make your money last longer. Once you start looking at your spending closely and planning where your money should go, you begin to feel more calm and in control instead of worried all the time. This article explores some budgeting tips for beginners, helping them choose and create a budget that actually works for them and is realistic. 

Budgeting Tips For Beginners: How To Start A Budget That Actually Works

Think About Why You Want to Budget

Illustration of a woman writing in a notebook labeled “My Budget Goals” with floating icons of travel, savings, and peace of mind on a pastel pink background, representing motivation for budgeting.

Before you even start writing numbers down, it helps to take a moment and think about why you want to make a budget in the first place, because understanding your reason gives meaning to every step you take after that. Maybe you want to stop feeling stressed every time you check your balance, or you’re saving up for something important like a trip, a new phone, or just a little financial peace of mind. 

When you know your “why,” budgeting starts to feel less like a boring task and more like something that’s actually helping you live the life you want. It’s about giving your money a direction, instead of letting it slip away without you realizing where it went.

Know How Much Money You Really Get

The next step is to find out how much money you actually bring home each month, not the total amount before taxes or deductions, but the amount that truly reaches your hands or account and is available for spending. This is called your net income, and it’s the number you’ll use to plan everything else in your budget. 

It’s easy to forget that things like taxes, insurance, or retirement contributions are already taken out, so knowing your real income helps you stay realistic and avoid planning for money you don’t actually have. When you start your budget based on what’s real, you can make better choices that actually work in your everyday life.

Write Down Every Expense You Make

Illustration of a woman writing down her daily expenses in a notebook with receipts and coins around her on a pastel pink background, symbolizing mindful money tracking.

To really understand where your money goes, you need to write down every single expense, even the small ones that seem unimportant at the time, like a snack, a bus ticket, or a quick coffee. These small things add up quietly, and before you know it, they become the reason your money feels like it disappears too soon. You can write them down in a notebook, use your phone’s notes app, or try a simple spreadsheet, whatever feels the easiest for you. 

The goal isn’t to judge yourself but to see the truth of your spending habits, because once you know where your money actually goes, you can start taking control of it instead of wondering where it went.

Group Your Spending Into Simple Categories

Once you’ve tracked your expenses, it helps to group them into a few easy categories that make sense to you, such as needs, wants, savings, and maybe debt payments if you have any. Needs include things like rent, bills, and groceries, while wants are the extras like eating out, entertainment, or buying clothes. 

Savings and debt payments are about your future, making sure you’re ready for emergencies or working to pay off what you owe. Keeping your categories simple makes the whole process less confusing, and it becomes easier to see which areas are taking up most of your money and where you might need to cut back a little.

Set a Few Money Goals That Matter to You

When you start budgeting, it helps to have a few clear goals in mind, because goals give your plan direction and purpose. Maybe you want to save for something fun like a short trip, or something serious like an emergency fund or paying off a loan. 

You don’t need ten different goals all at once, even one or two can make a big difference, especially when they mean something to you personally. Each time you put money aside, you’ll feel like you’re getting closer to something real, not just restricting yourself, and that feeling makes it much easier to stick with your plan for the long run.

Choose a Simple Way to Budget

There are many ways to make a budget, but as a beginner, the best one is always the one that feels easy and natural to follow. Some people like the 50/30/20 rule, where 50% goes to needs, 30% to wants, and 20% to savings, while others prefer using envelopes or digital apps. 

You don’t need anything fancy, even a basic notebook or notes app can do the job perfectly well. The goal is to find a method that fits your lifestyle, not one that makes you feel stressed or confused. Once you find what works for you, sticking to your budget starts to feel like second nature instead of a chore.

Save a Little Before You Spend

A helpful habit to build early is to save a little money as soon as you get paid, instead of waiting to see what’s left after spending. This way, saving becomes automatic and you’re less likely to spend money that was meant for your future self. Even if it’s a small amount, like 5% or 10% of your income, it still counts, because saving is more about consistency than size. 

When you pay yourself first, you’re telling yourself that your goals matter just as much as your bills or daily spending, and that mindset slowly builds long-term security and confidence.

Keep Some Money Aside for Emergencies

Life can be full of surprises, and not all of them are pleasant, which is why having a small emergency fund can save you a lot of worry later. It doesn’t have to be a huge amount at first; even setting aside a small portion each month can make a difference over time. This money is not for regular shopping or treats, it’s for those unexpected moments like a car repair, a sudden medical bill, or a job change. Knowing that you have something to fall back on helps you stay calm and prevents you from turning to credit cards or loans every time something goes wrong.

Learn to Tell the Difference Between Needs and Wants

One of the hardest but most important parts of budgeting is learning to tell what you truly need versus what you just want. Needs are the things you must have to live like food, shelter, and basic bills while wants are the things that make life more fun or comfortable. 

It doesn’t mean you have to give up everything you enjoy, but it helps to be mindful so you don’t spend too much on wants and forget about your essentials or goals. Over time, this small habit teaches you balance, so you can enjoy life without feeling guilty or stressed about your money.

Check Your Budget Often and Make Changes When Needed

A budget isn’t something you set once and never touch again; it’s something you keep checking and adjusting as your life changes. Maybe your income increases, or your expenses shift, or you set a new goal that matters more to you now. 

Reviewing your budget every month or two helps you stay on track and spot small problems before they become big ones. You don’t have to make major changes all at once just small, simple updates that keep your plan working for your real life.

Use Simple Tools That Help You Stay on Track

You don’t need fancy software or complex systems to manage your money, there are many easy ways to stay organized, from using a basic notebook to free budgeting apps that track your spending automatically. 

The idea is to make things easier for yourself, not harder. If writing things down helps you remember, do that and if an app gives you reminders, use it. The simpler and more natural it feels, the more likely you are to stick with it in the long run.

Be Patient With Yourself and Don’t Give Up

Budgeting takes time to get right, and no one gets it perfect from day one, so it’s important to be patient and gentle with yourself. Some months will go smoothly, while others might feel messy, but that’s completely normal. The goal isn’t to be perfect, it’s to keep trying and improving little by little. Every time you make a smart choice with your money, you’re getting stronger and more confident. With time, you’ll realize that budgeting isn’t about limits, it’s about learning to control your money instead of letting it control you.

Conclusion

Starting a budget can feel tricky at first, but once you understand your income, track your spending, and set clear goals, it becomes something that helps you, not something that holds you back. The key is to keep it simple, stay honest with yourself, and make small, steady changes that fit your life. Over time, you’ll notice that budgeting brings peace instead of stress, and freedom instead of pressure, because it helps you see exactly where your money goes and how you can use it in a way that truly supports your future.

Budgeting 101: A Beginner’s Guide to Managing Your Money

November 2, 2025 By Ana Rose

Budgeting is less about restriction or holding back on things you enjoy, it’s more about being mindful and intentional where your hard-earned money goes, making it work for you and controlling it rather than letting it control you. Whether you’re trying to pay off a debt, build an emergency fund, or simply want to stop living paycheck to paycheck, budgeting can help you create a plan that gives your money purpose and direction. This article will help you explore the basics of budgeting, allowing you to understand where your money goes and how to make every dollar you earn work for you, not against you. 

Budgeting 101: A Beginner’s Guide to Managing Your Money Graphic

Why Budgeting Matters

Many people tend to avoid budgeting because it may sound restrictive, intimidating, or overwhelming, but the truth is that budgeting is a tool that makes your financial life easier to deal with. When you know where exactly your money goes every month, budgeting helps you stop living in uncertainty, prevents overspending, helps you avoid impulse purchasing , and eventually allows you to make mindful decisions when it comes to the money you work so hard for. 

Budgeting makes all the difference between controlling your money and letting it control you, and this shift is all that brings both confidence and peace of mind in the long run. 

Understanding Your Income

Your budget starts with understanding your income and calculating how much money is coming in every month. Whether it’s your salary, freelance gigs, side hustles, or other sources of income, it is important to give yourself a figure instead of relying on guess work. 

Once you have a total, calculate your net income, which is after all the taxes and deductions and is your take home pay. Having a clear number can help you plan your spending and expenses accordingly instead of relying on credit cards to fill the gaps. While this step may seem simple, it is crucial to give your finances a solid foundation to begin with. 

Tracking Your Expenses

Illustration of a woman tracking her expenses in a notebook with floating icons of groceries, coffee, and bills on a pastel pink background, symbolizing mindful money tracking.

The next step is to track your expenses and stay aware of your spending habits. Track your expenses for at least one month and explore your spending pattern. Whether it’s those midnight snacks, coffee runs, groceries, or gas, tracking your expenses can help you see those underlying unhealthy spending habits that put your entire budget off track. 

Being in the clear with your spending habits can help you take action, getting an honest picture of your habits so you can make smarter financial choices in the future. You can track your expenses through budgeting apps, by creating a spreadsheet, or by using something as simple as a notebook. 

Categorizing Your Spending

Once you’ve tracked your expenses, organize them into categories like housing, utilities, groceries, transportations, or entertainment. Categorizing your spending can help you see the bigger picture, helping you identify areas where adjustments are needed. For example, you may come to realize that those streaming subscriptions or those random online shopping sprees cost you way more than you thought. 

Categorizing helps you simplify your budget, making it easier to find the right balance between needs and wants. 

Setting Realistic Financial Goals

A budget becomes more meaningful and easier to follow when there’s a goal associated with it. Whether you’re planning for a big future goal, trying to save up for an emergency fund, or simply want to manage money more effectively, having a specific, clear, and realistic goal can add a personalized touch to the whole process, making it easy for you to stay consistent and committed with the process. 

These goals can keep you motivated and help you stay focused when temptations to spend or the impulse to purchase something hits you out of nowhere. It is essential to remember that specific goals are easier to achieve and more satisfying to reach rather than undefined and unclear goals. 

Choosing a Budgeting Method

The next step is to choose a budgeting method that fits you, your income, and lifestyle the best. You can consider the 50/30/20 rule where 50% of your income goes to your needs, 30% to your wants, and 20% to savings or debt repayments, if there are any. 

You consider the envelope method as well which includes creating different spending categories and assigning cash to each category. The catch of this method is to stay within the spending limit and once you run out of cash placed inside those envelopes, that’s your cue to stop spending on that specific category. Lastly, you can also go with zero-based budgeting method which is all about assigning a purpose to every dollar until there’s nothing left behind. 

Prioritizing Needs vs. Wants

One of the most important parts of budgeting is learning the difference between your needs and your wants, because this simple step can completely change how you manage your money. Needs are the things you can’t live without like rent, groceries, electricity, and transport, while wants are the extras that make life more fun, such as going out for dinner, shopping for new clothes, or buying the latest gadgets. 

The goal isn’t to cut out every little thing you enjoy, but to spend wisely so that your wants don’t get in the way of your real priorities. When you learn to give your needs the first place in your budget and allow space for your wants only after covering your essentials, you start to feel more in control of your money without feeling restricted. 

Building an Emergency Fund

Illustration of a woman saving money in a glass jar labeled “Emergency Fund” with icons of safety and planning on a pastel pink background, representing financial security and preparedness.

Life doesn’t always go according to plan, and that’s why an emergency fund is one of the most important parts of any strong budget. Whether it’s a sudden car problem, a health emergency, or an unexpected job change, having some money saved can help you stay calm and avoid going into debt. It’s okay to start small, even saving a little bit from each paycheck can make a difference over time because the goal is to build a safety net that grows slowly and steadily. Try to work your way toward saving at least three to six months’ worth of living expenses so you can handle anything unexpected without worrying about how you’ll pay for it. 

Managing Debt Wisely

Debt can easily feel stressful and heavy, but a good budget can help you take back control and manage it one step at a time. The first thing to do is write down all your debts, like credit cards, personal loans, or anything else you owe  and note down their interest rates and payment dates. 

This helps you see the full picture instead of feeling lost or overwhelmed. Try to pay off the debts with the highest interest first while still making the minimum payments on the rest, or follow the snowball method, where you clear the smallest debts first to build confidence and motivation. 

Saving and Investing

Saving money gives you stability, but investing it helps you grow your wealth over time. Once you’ve built your emergency fund and handled your basic expenses, try setting aside a small amount every month just for savings or future goals. Automating your savings, where money moves directly to your savings account, can make it easier to stay consistent without overthinking. 

When you’re ready, learn about simple investment options like mutual funds or retirement accounts that let your money work for you. You don’t need a lot to start, even small investments made regularly can grow with time because of compounding. 

Using Budgeting Tools and Apps

Budgeting doesn’t have to be complicated, especially when there are so many easy tools and apps that can help you stay on track. You can use free apps like Mint, YNAB (You Need A Budget), or Goodbudget to automatically track your income and expenses, set spending limits, and get reminders. 

If you prefer something simple, a spreadsheet or a notebook works just as well. The goal is to choose a method that feels comfortable for you, something you can actually stick to every day. 

Reviewing and Adjusting Your Budget

Your budget isn’t something you make once and forget, it’s something that should grow and change with your life. Your expenses, goals, or income might change over time, and your budget should adjust with them. Reviewing your budget every month or every few weeks helps you see what’s working and what isn’t, allowing you to fix small problems before they turn into big ones. Maybe your grocery costs went up, or you started a new job, small adjustments keep your plan realistic and flexible. 

Conclusion

Budgeting might seem like a lot of work in the beginning, but once you start, you may come to realize that it gives you freedom instead of limits. It helps you understand where your money goes, make smarter choices, and stay focused on your goals without feeling lost or anxious about your finances. Whether it’s tracking your expenses, categorizing them, or managing debt wisely, what matters the most is your consistency and willingness to keep moving forward. Over time, these small habits can help you build something meaningful in the long run, finally helping you make money for you, not against you. 

A Beginner’s Guide to Budgeting Finances with the 40-30-20-20 Rule

November 1, 2025 By Ana Rose

If you’ve ever wondered where your paycheck disappears every month or why saving feels so hard, you’re not alone. Managing money is not as simple as it may sound but with a budget that is simple, practical, and realistic, managing money can become easier to deal with. One of the easiest and most balanced ways to budget your income is the 40-30-20-20 rule which is all about dividing your spending into 4 categories, needs, wants, savings, and paying off debt or investing. If you’re new to the 40-30-20-20 budgeting method, this article will help you explore the dynamics of the rule that is structured enough to maintain discipline and flexible enough to make it feel less overwhelming and more like something you can work with. 

A Beginner’s Guide to Budgeting Finances with the 40-30-20-20 Rule

Understanding the 40-30-20-20 Rule

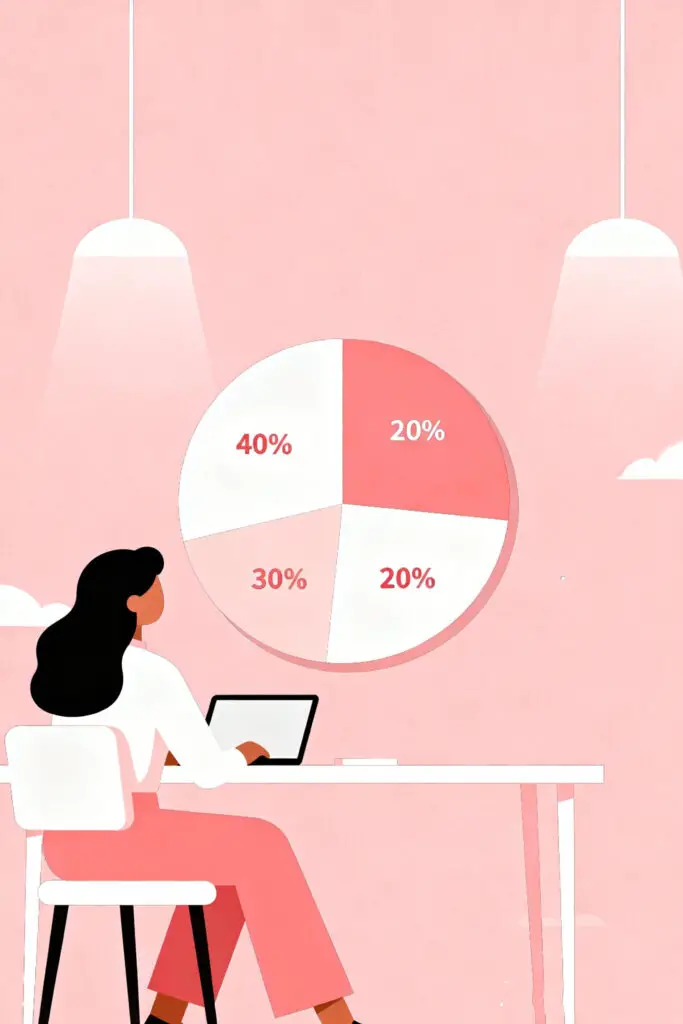
Illustration of a woman studying a pastel pie chart labeled needs, wants, savings, and investments, representing the breakdown of the 40-30-20-20 budgeting rule.

The 40-30-20-20 is a modern and more flexible approach that makes room for needs, wants, savings, and debt repayment or investments as well. The rule suggests that 40% of your income goes to your needs, 30% to wants, 20% to savings, and lastly 20% to investments or debt repayments. 

This balanced system of distribution can help you prioritize your expenses, preferring needs over all other spending categories. It makes sure you cover your day-to-day necessities , save for savings, while still making room for things and activities you enjoy, debt payments if there are any, or pay your future self by investing. 

Why This Rule Works for Beginners

The reason the 40-30-20-20 rule works so well for beginners is that it takes away the confusion and complexity that often comes with traditional budgeting. Instead of dealing with dozens of categories and endless sub-lists, it keeps things simple and focused by grouping all your spending into four easy-to-understand sections. 

You instantly get a clear view of where your money is going, what’s necessary, what’s enjoyable, what’s being saved, and what’s helping you grow. It also helps you stay balanced between living comfortably today and preparing for tomorrow, which is something most people struggle to find. It’s less about strict restrictions and more about giving your money direction and purpose.

Breaking Down the 40%: Covering Your Essential Needs

The first 40% of your income goes toward your needs, which are the foundation of your financial life. These are the unavoidable, must-pay expenses that keep your household running such as things like rent or mortgage payments, groceries, utilities, healthcare, insurance, transportation, and basic personal care. 

The idea is to make sure your essential expenses are comfortably covered without spilling over into the money you’ve allocated for wants or savings. This also helps you identify when you might be overspending on something that should be considered a want rather than a need, giving you a clearer picture of your true living costs and where adjustments may be necessary.

The 30% for Wants: Enjoying Life Without Guilt

Illustration of a smiling woman enjoying coffee and shopping with icons of leisure and treats around her on a pastel pink background, symbolizing mindful spending on wants.

The next 30% is reserved for your wants, which are the things that add comfort and happiness to your life, making your daily routine feel more enjoyable and less mechanical, even though they’re not necessary for survival. This portion of your budget is where you allow yourself room to breathe and enjoy the small luxuries that bring you joy, whether that’s going out for dinner with friends, taking a weekend getaway, or treating yourself to that morning coffee that starts your day on a comforting note. 

What makes this budgeting rule truly practical is that it doesn’t force you to completely give up the things you love, it simply helps you manage them with balance and mindfulness, so you can indulge in them without feeling the guilt that often comes with overspending.

The 20% for Savings: Building Your Financial Cushion

The next 20% of your income should go directly into savings, which acts as your personal safety net for the future, giving you a sense of stability and reassurance no matter what life brings your way. This portion of your budget can be divided into different purposes such as an emergency fund for unexpected situations, short-term goals like buying a new car or renovating your home, and long-term goals like retirement or future investments that help you build wealth over time. 

Every dollar you set aside is a step toward independence and confidence, reminding you that you’re not just earning for today but also protecting tomorrow. 

The Other 20%: Paying Off Debt or Investing for Growth

The final 20% of your income is dedicated to debt repayment or investments, depending on where you are in your financial journey, and this is the part that truly helps you move forward and grow beyond simply managing expenses. If you’re dealing with debts such as credit cards, personal loans, or student loans, this portion should go toward paying them down consistently, reducing your financial burden and freeing up future income for other goals.

Once your debts are under control or completely paid off, you can then channel this same amount into investments such as mutual funds, index funds, or retirement accounts that allow your money to grow passively and steadily over time.

How to Calculate Your Income and Apply the Percentages

To make the 40-30-20-20 rule truly work in your favor, the first step is to calculate your net income, which is the actual amount you take home after taxes and deductions, giving you a realistic figure to base your budget on. Once you have that clear number, you can begin dividing it according to the rule, 40% for needs, 30% for wants, 20% for savings, and 20% for debt repayment or investments. For instance, if your take-home pay is $3,000 per month, this would mean $1,200 goes toward your needs such as rent, groceries, and bills, $900 can be comfortably spent on your wants, $600 is directed into savings, and another $600 is used to pay off debt or invest. 

Adjusting the Rule to Fit Your Lifestyle

Everyone’s lifestyle, income, and priorities are different, which is why the 40-30-20-20 rule isn’t meant to be a strict plan that fits everyone the same way. It’s more like a flexible guide that you can adjust to your own life. For example, if your rent, groceries, or bills take up a bigger part of your income, you can shift the rule a little, maybe spend 45% on needs and reduce your wants to 25%, and if you don’t have any debt, you can move that extra 20% toward savings or investing to grow your money faster. 

The goal is to make this rule work for you, not to feel restricted or stressed by it, but to find a balance that feels natural, realistic, and easy to maintain over time.

Common Mistakes People Make with the 40-30-20-20 Rule

A common mistake people make when following this rule is mixing up needs and wants like calling eating out a “need” or thinking that upgrading to the latest phone every year is necessary. Another mistake is forgetting to count small, regular expenses such as subscriptions, parking, or food delivery, which can quietly eat away at your budget without you noticing. 

The best way to avoid these slip-ups is to stay aware and honest about your spending habits. Take a few minutes each week to review your expenses and see where your money is going. This helps you notice unhealthy patterns early and make small adjustments before they turn into bigger problems.

Tips to Stay Consistent with Your Budget

The toughest part about budgeting isn’t actually making the plan, it’s following it consistently. To make it easier, try automating your savings and debt payments so that the money is transferred automatically every month before you even get a chance to spend it. 

You can also keep a simple tracker, whether it’s on paper or an app, to watch your progress and celebrate small wins along the way. Remember, consistency doesn’t mean being perfect, it means showing up and making mindful choices most of the time. Even small, steady steps add up and keep you moving closer to financial control and peace of mind.

When and How to Review or Rebalance Your Budget

Your budget isn’t something you create once and then leave untouched forever, it’s meant to grow and evolve as your life does. Over time, your income might increase, new bills might appear, or your priorities may shift, which means your budget should adjust to reflect those changes. 

A smart habit is to review your budget every few months and check whether it still fits your lifestyle and goals. If you notice that you’re overspending in one area or saving less than you’d like, don’t panic or make big, overwhelming changes all at once. Instead, make small, realistic changes that you can actually stick to. 

How This Rule Leads to Financial Freedom 

The real beauty of the 40-30-20-20 rule lies in its balance, it gives you both structure and flexibility at the same time. It helps you cover your essential needs, enjoy the things that make life fun, and still save or invest for the future without feeling deprived. 

This rule teaches you that financial control doesn’t mean giving up on happiness or comfort, it means being intentional about how you use your money. Over time, you start to feel more confident about your finances, more mindful about your spending, and more peaceful knowing that you’re not just surviving, but slowly building stability and freedom. 

Conclusion

At the end of the day, the 40-30-20-20 rule is one of the easiest and most practical budgeting systems you can follow. It’s simple enough for beginners to understand, yet powerful enough to bring long-term balance to your finances. By giving every dollar a purpose and dividing your income in a thoughtful way, you’re building a foundation that brings both your present comfort and your future security. Whether you’re just starting your money journey or trying to organize your current finances, this rule helps you find clarity, balance, and calm, reminding you that good money management isn’t about strict limits, but about making your finances work for you, one intentional step at a time.

The 30-Day Budget Plan That Actually Works (Step-by-Step Challenge)

October 31, 2025 By Ana Rose

Budgeting doesn’t have to be intimidating, overwhelming, or filled with complicated spreadsheets that are too hard to read, that ultimately make you want to give up before you even start the journey. Sometimes, all it needs is a focused 30-days plan to help you reset your financial habits and modify them into something that serves the future you. The 30-day budget plan is a practical, realistic, and hands-on challenge that is designed to help you achieve financial discipline, gain clarity and insight regarding your spending habits, and create a budget that truly fits you, your lifestyle, and income the best. This article will explore the dynamics of the 30-day challenge, helping you take on a journey that will get you back on track, step by step. 

The 30-Day Budget Plan That Actually Works (Step-by-Step Challenge)

Day 1–2: Define Your “Why” Behind Budgeting

Illustration of a woman writing her financial goals at a pastel pink desk with floating icons of savings and dreams, symbolizing finding her “why” behind budgeting.

During the first two days of your 30 day challenge, sit down with yourself and figure out the ‘why’ behind budgeting. Ask yourself questions like, “Am I saving for something important?”, “Am I budgeting only because I want to stop living paycheck to paycheck?”, or “Do I want to feel more organized and disciplined by managing money?”

Having a reason behind budgeting can add a personalized touch to the whole process, making it easy for you to stick with it. You can write down your reason somewhere you can see it often as this simple exercise can help you remind you of your goal, motivating you to stick to it even when the journey feels tough. 

Day 3–4: Calculate Your Total Income

Once you’ve figured out the ‘why’ behind your journey, the next step is to calculate your total income. This can include your salary, freelance gigs, side hustles, or other sources of income. The next step is to calculate your net income, which is your take home pay, after all the taxes and deductions, giving you a specific figure to deal with all the expenses. 

The goal is to have a clear picture of your total monthly income so you work with the figure and deal with all the expenses, staying within your monthly income. When you know how much money is coming in every month, you can budget with efficiency, making it less of a guesswork and more of an organized and structured process. 

Day 5–6: Track Every Expense

Illustration of a woman tracking her daily expenses using a laptop and phone with floating receipts and charts on a pastel pink background, representing mindful spending.

Once you know how much money is coming in each month, the next step is to track every expense for these two days. Whether it’s those coffee runs, online orders, or a ride you booked, track it all and note every expense, either big or small. 

If you prefer a digital approach, you can consider creating a spreadsheet, budgeting apps that help you track every expense, or even something as simple as a notebook can be used. The point of this step is not to judge what you spend at but to promote mindful and intentional spending when it comes to your hard-earned money. When you see your expenses written down with unhealthy patterns showing, it’s easy to modify them in a way that it serves the future you.

Day 7–8: Review the Past Month’s Spending

The next step is to review your past months’ spending by reviewing your bank statement or receipts from the past months. This step can give you a bigger picture of your past spending habits, for instance, you might notice that you’re more prone to spending on coffees, takeouts, or dining out. 

It’s important to remember that this step is not about guilt or shame, it’s more about being honest with yourself and knowing your spending habits more deeply, allowing you to make smarter and sane decisions regarding your hard-earned money. 

Day 9–10: Categorize Your Expenses

Once you’ve reviewed your spendings, the next step is to categorize your expenses. The simplest approach is the 3-category budgeting with needs, wants, and savings. Needs are those basic and essential expenses, necessary for survival, including housing, utilities, food, or transportations. Wants are those nice-to-have non-essential expenses that are fun and it feels good spending on them, including subscriptions, takeouts, or shopping for clothes. Lastly, savings can include emergency funds, investments, or goals. 

By categorizing, you can give each of your expenses a place, making it easy for you to spend based on their priority, with needs coming first, then wants, and then savings. 

Day 11–13: Set Realistic Spending Limits

The next step is to create realistic spending limits, making it easy for you to stick with the budget and make sure that it works for you by not setting unrealistic standards. If you set your limits too tight, there’s a high possibility you may feel like the process is overwhelming and frustrating, making it crucial to find a balance. 

For example, if you currently spend $400 on eating out, aim to reduce it to $300 instead of cutting it off completely. This way you can still enjoy the things you like while paying attention to the limits you’ve set for yourself. 

Day 14–16: Create a Cash Envelope or Digital Tracker System

By this point, you already have a clear idea of where your money goes and how much you want to spend in each category, so now it’s time to find a system that helps you actually stay on track with your plan. 

Some people prefer using the old-school cash envelope system, where they divide their money into labeled envelopes, one for groceries, one for entertainment, one for dining out, and so on, and once an envelope runs out, they stop spending from that category. 

Others feel more comfortable with a digital approach, using budgeting apps or spreadsheets to record every transaction. 

Day 17–19: Identify Spending Triggers

Everyone has certain emotional or situational triggers that push them toward unnecessary spending, and identifying those triggers can make a huge difference in how you manage your money. Maybe you tend to shop online when you’re stressed or bored, or you order food when you feel too tired to cook, or you spend impulsively when hanging out with certain friends. 

These small, unnoticed habits can quietly drain your budget without you even realizing it. Once you recognize your triggers, you can start creating healthier alternatives like going for a walk instead of scrolling through shopping apps or prepping simple meals for busy evenings. 

Day 20–22: Find Areas to Cut or Replace

After identifying your triggers, the next step is to find areas where you can gently cut back or make smart replacements without feeling deprived. Cutting back doesn’t mean completely eliminating the things you enjoy, it’s about creating small, intentional changes that help your budget breathe a little better. For example, if you notice you’re spending too much on coffee, you can brew it at home a few days a week and save the coffee shop visits for weekends. 

Even the smallest adjustments can make a noticeable difference over time, and what might feel like tiny savings at first can eventually become a substantial amount that supports your financial goals.

Day 23–25: Start Building Your Emergency Fund

Now that you’ve started freeing up a little extra money by cutting down unnecessary expenses, it’s time to put that saved money to good use by building an emergency fund. An emergency fund is one of the most comforting and empowering financial tools you can have as it acts as your safety net for unexpected situations like car repairs, medical bills, or sudden job changes. 

You don’t need to save a huge amount right away, the idea is simply to start. Even if you put aside a small amount like $20, $50, or $100 every month, what matters most is consistency. Over time, these small contributions grow and give you a sense of peace, knowing that you’re financially protected against life’s little surprises.

Day 26–28: Review and Adjust Your Budget

At this stage, you’ve been practicing budgeting for almost a full month, which means you now have enough data to see what’s working well and what’s not. This step is about reviewing your progress and making gentle adjustments where necessary.

Budgeting is not about getting everything perfect from day one, it’s about learning, evolving, and adapting as your circumstances change. Sit down with your notes or tracker, reflect on your financial choices over the past few weeks, and make updates that reflect your current lifestyle. 

Day 29–30: Reflect and Set Next Month’s Goals

As your 30-day challenge comes to an end, take these last two days to slow down and reflect on everything you’ve accomplished so far. Think about what you learned from the process, what surprised you, what made you feel proud, and what you’d like to improve in the next month. 

This reflection can help you recognize your progress and celebrate it, no matter how small it might seem. You’ve already taken control of your finances in a way that many people struggle to even start, and that deserves recognition. Now, use this to set new, realistic goals for the next month, whether that means saving a little more, reducing one expense category further, or starting to invest. 

Conclusion

By the end of this 30-day budgeting challenge, you’ll realize that managing money doesn’t have to be stressful, restrictive, or filled with confusion, it can actually be a deeply empowering experience that brings calm into your life. You’ll know where your money goes, how to control it instead of letting it control you, and how to make mindful choices that support your goals instead of sabotaging them. Once you’ve taken this journey, you’ll find that budgeting isn’t about giving up the things you love, it’s about creating a life where you can enjoy them more freely, because your finances are finally working for you, not against you.

  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 40
  • Go to page 41
  • Go to page 42
  • Go to page 43
  • Go to page 44
  • Interim pages omitted …
  • Go to page 170
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers