• Skip to primary navigation
  • Skip to main content

Just Start Investing

We Make Investing Easy

  • Investing
    • Learn About Investing:
    • Investment Accounts
    • Online Brokerage Accounts
    • Investment Vehicles
    • Start Investing:
    • How to Invest in Index Funds
    • Start Investing with Betterment
    • Start Investing with Charles Schwab
  • Banking
    • Best Bank Accounts
    • Types of Bank Accounts:
    • Checking Accounts
    • Savings Accounts
    • CDs and Money Market Accounts
    • Online Banks vs Brick-and-Mortar
  • Credit Cards
    • Best Credit Cards:
    • Best Cash Back Credit Cards
    • Best No Annual Fee Credit Cards of 2021
    • Best Premium Credit Cards of 2021
    • Credit Card Tool: Find the Best Credit Card for Me
    • Learn About Credit Cards:
    • Types of Credit Cards
  • Blog
    • Investing
      • What is Crypto?
        • Crypto
      • What are stocks?
        • Stocks
      • What is a Real Estate Investment?
        • Real Estate Investments
      • What is an IPO?
        • IPO
    • Banking
    • Credit Cards
    • Budget
    • Finances
  • Earn with Crypto
  • Budget
    • How to Build a Budget
    • 24 Tips to Save More Money
  • Resources
  • About
    • Contact
    • Press
    • Learn More
    • Disclaimers
  • Show Search
Hide Search

Blog

Smart Ways to Use Budget Categories for Financial Planning  

October 25, 2025 By Ana Rose

Budgeting is not only limited to tracking your money and making decisions, it’s more about giving a clear and realistic roadmap to your hard-earned money so that it serves you, both financially and mentally. When you organize your spending into smart, meaningful, and thoughtful categories, you gain control over where your money goes rather than letting it control you. It can also help you reduce stress and make more intentional choices when it comes to financial dynamics, such as investment or saving. This article will explore a complete guide on how to use budget categories wisely, helping you become financially stable and free in the long run. 
Smart Ways to Use Budget Categories for Financial Planning Graphic

Start with the 50/30/20 Framework

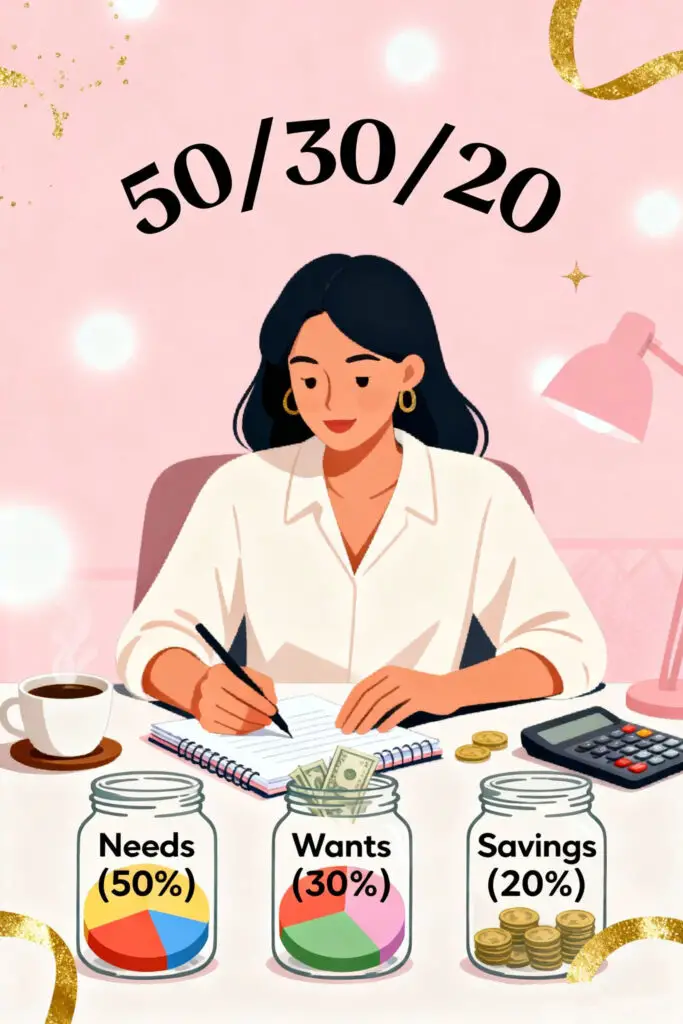
An illustration of a woman managing her budget using the 50/30/20 rule with jars labeled Needs, Wants, and Savings on a pastel pink background, symbolizing smart financial planning and balance.

The 50/30/20 budgeting rule is one of the simplest yet highly effective budgeting methods which is all about prioritising essential expenses over non-essential ones. This budgeting method divides your expenses into three categories, needs, wants, and savings. 

According to this budgeting technique, 50% of your income is spent on your needs or those essential expenses including rent, food, transport, or utilities, 30% of your paycheck goes to the non-essential expenses or those nice-to-have items including shopping for clothes, takeouts, or subscriptions you don’t really need. Lastly, 20% of your income is assigned to savings, investment, or paying off debt, if there is any.

What makes this budgeting method considerable is that it perfectly divides the spending categories, helping us prioritize essential ones over non-essential ones, while still making room for savings and other financial goals. 

Separate Needs from Wants Clearly

What makes budgeting easier is being able to tell the difference between needs and wants. While this may seem simple and straightforward, distinguishing needs and wants can be difficult at times and is definitely a skill that requires decision-making and logical reasoning. 

In simpler terms, needs are those essential expenses that are necessary for survival including rent, utilities, food, or healthcare. On the other hand, wants are those extras that aren’t essential but they make life fun and enjoyable, such as those daily coffee runs, vacations, or gadgets. 

When you draw a clear line between the two, you can easily make more mindful and intentional decisions when it comes to your hard-earned money. You may come to realize that you can still feel content and at ease without buying that dress you’ve been eyeing online. 

Create a Category for Emergencies
An illustration of a person saving money in an emergency fund jar under an umbrella on a pastel pink background, representing financial protection and planning for unexpected expenses.

Life has its way of throwing unforeseen circumstances your way when you least expect them, and at times, those situations bring along a price tag with them. Whether it’s a car repair situation, job loss, or a sudden medical bill, it’s easy to forget that life can take a sudden turn and it’s important to be prepared for it, both mentally and financially. 

A smart way to avoid stress and financial crisis is to create a category for emergencies by creating a dedicated emergency category and contributing to it regularly, even if it’s a small amount each month. Over time, these small amounts can grow into something big and meaningful, allowing you to deal with every curveball that life throws your way with confidence and peace. 

Include a Debt Repayment Category

Debt can definitely drain your finances and harm them if not managed properly, making it crucial to deal with it with responsibility. Create a specific category for debt repayment which can include credit card balances, student loans, car payments, or personal loans.

You can further divide this into “minimum payments” to stay current and “extra payments” to reduce principal faster. Prioritizing debt repayment not only helps improve your credit score but also frees up more income for savings and investments in the long run. 

Prioritize a Savings and Investments Category

What makes saving difficult is the habit of setting aside the leftover money, instead of paying yourself first. Creating a separate category for savings and investments ensures that a part of your income always goes toward building your financial future. 

Even if you start small, the habit of saving consistently can lead to big results over time. This category can include short-term savings, like saving for a vacation or a new phone, and long-term goals, such as retirement or a home. 

You can also dedicate a portion to investments like mutual funds or stocks if you want your money to grow faster. The key is to treat saving as a non-negotiable expense, just like rent or utilities, because it secures your peace of mind and helps you build financial independence for the long run.

Add a Category for Irregular or Annual Expenses

It’s easy to overlook or forget those expenses that happen to show up once or twice a year but when they do, they potentially harm your entire budget and put it off track, which is exactly why it is essential and crucial to make preparation for these expenses beforehand. Whether it’s car registration, insurance renewal, or holiday gifts, these irregular costs can cost you way more than you may realize. To avoid letting these expenses hurt your budget, a smart approach would be to create a sinking fund category where you save a little each month for upcoming annual expenses. 

This way, when the time comes for you to deal with these expenses, you’ll have a safety net and won’t have to dip into savings or cut into your regular budget, making this option a  considerable one for financial planning. 

Track Personal Care and Health Expenses

Your health and well-being deserve just as much attention as your bills or savings. Having a specific category for personal care and health can help you stay prepared, both financially and mentally, for medical checkups, medications, fitness memberships, or even small wellness habits. 

Many people skip including these costs in their budget and end up feeling financially stressed when unexpected health-related expenses appear.

Make Room for Fun and Entertainment

A good budget isn’t supposed to feel restrictive or like a punishment, it’s more about creating balance between discipline while still making room for things you enjoy. Life should be enjoyed too, and that’s why creating a category for fun and entertainment is important. Whether it’s dining out with friends, watching a new movie, going on a small trip, or treating yourself to something nice, these moments matter. 

This way, you can spend guilt-free on things you enjoy and find pleasure in because all that spending is a part of your plan. This approach helps you avoid impulse spending and keeps your budget from feeling restrictive or boring. 

Budget for Giving and Donations

Giving back is one of the most fulfilling ways to use your money. Whether it’s donating to a cause you care about, helping a friend or family member in need, or contributing to community efforts, including a “giving” category in your budget allows you to share your blessings responsibly. This way, donations and the act of giving doesn’t disrupt your regular budget or savings, it becomes a thoughtful part of that. 

Plan for Education and Skill Development

Investing in yourself is definitely one of the best financial decisions you can ever take. By creating a category for education and skill development, you’re setting aside funds for your personal and professional growth. 

This could include taking an online course, attending a workshop, buying books, or learning a new skill that helps you earn more in the future. These expenses might not give instant results, but they pay off in the long run by opening doors to better opportunities. When you include learning as a category in your budget, you’re not just spending money, you’re investing in the future you. 

Track Transportation and Housing Costs 

Transportation and housing are usually the biggest parts of any budget, and keeping them under control can make a huge difference in your financial health. This category should include rent or mortgage payments, utilities, fuel, maintenance, and any public transport costs. 

What makes it important to track these costs is because even small increases can quietly ruin your budget over time. If your rent feels too high or your commute too expensive, exploring smarter alternatives, like finding a more affordable place or carpooling, can ease financial pressure. 

Review and Adjust Categories Regularly

A budget is not something you set once and forget, it’s something that grows and changes with you. Your income, lifestyle, or goals might shift over time, and your budget should reflect those changes too. 

Reviewing your categories every few months helps you stay on track and make better decisions. For instance, if you’ve paid off a debt, you can move that money into savings or investments, or if your expenses increase, you can rebalance your spending to keep everything in control. 

Conclusion

At its core, budgeting isn’t about cutting back or living with less, it’s about gaining control, clarity, and confidence over your money. When you divide your income into categories that make sense and have a deeper meaning, you create a plan that is thoughtful and can serve you in the long run as well. Each category plays a role in shaping a balanced financial journey, one where your essentials are secure, your goals are within reach, and there’s still room for joy and growth. Over time, these small, thoughtful decisions turn into lifelong habits that lead to stability and peace of mind. 
Bi Weekly Savings Challenge

October 24, 2025 By Ana Rose

Saving money can be difficult especially when you’re living from paycheck to paycheck, figuring out ways to make money last till the end of the month. But the truth is that you don’t need to save thousands of dollars in one go, you just have to follow a realistic plan, stay consistent, and gradually build savings in smaller and manageable ways. The biweekly savings challenge is one of the easiest and most practical challenges that helps you save through small steps without having you feel overwhelmed and frustrated by the process. Whether you’re saving up for an emergency fund, a vacation, or simply trying to build a better financial life, this article will help you explore the dynamics of a biweekly savings challenge that can help you save money every two weeks in a way that feels doable and fits your lifestyle as well. 

Bi Weekly Savings Challenge Graphic

Step 1: Understand What a Bi-Weekly Savings Challenge Is

A biweekly savings plan is a structured plan that helps you set aside a specific amount every two weeks. Instead of saving randomly or waiting until the end of each month, this challenge makes saving more consistent and manageable. 

Moreover, this method is quite helpful for those who receive their paychecks biweekly, helping them align their savings with their income and lifestyle. Over time, these small biweekly amounts can grow into something big and meaningful, giving you the motivation to move on with the challenge. 

Step 2: Set a Clear Goal

Before you get into the complexities of the challenge, it is crucial to know what you’re saving for. Whether it’s a big future purchase, an emergency fund, or something as simple as building a stable financial life, having a clear goal can give your progress meaning and direction, making it easier for you to stick with it through every thick and thin. 

You need to be specific and realistic with your goal, know it on a deeper level, and calculate how long it will approximately take you to save what you’re aiming for. Asking yourself these questions can help you achieve your target more effectively, leaving no room for unrealistic timelines and expectations. 

Step 3: Break Your Goal into Manageable Parts

Illustration of a woman organizing her savings goal into smaller parts using labeled jars and a notepad on a pastel pink background, representing manageable biweekly saving steps.

Once you know your total savings goal, the big figure may intimidate or overwhelm you and that’s exactly where the biweekly thing comes in. Divide your goal by the number of biweekly periods you plan to save for, for example, if you want to save $1,000 in one year, that will be about $38 every two weeks. 

Seeing a smaller number can make the process feel a bit easy and doable as compared to the big, frightening figure. It is crucial to remember that progress and consistency matters more than perfection, and each time you choose to show up every two weeks, that’s worth appreciating because it shows your willingness and discipline. 

Step 4: Automate Your Savings

To make the process easier and convenient to carry out, you can consider the possibility of automating the saving process. Set up an automatic transfer from your checking account to your savings account every two weeks, ideally on payday. This way you don’t have to rely on willpower and can save without having to think about it. 

Automation turns saving into a routine habit rather than something you have to intentionally make effort for, which is the real secret to building long-term financial stability. 

Step 5: Cut Down on Small, Repetitive Expenses

Sometimes finding extra money to save means looking closely at your spending habits and figuring out unhealthy spending patterns. Whether it’s those daily coffee runs, extra subscriptions, or frequent takeouts, these small and seemingly harmless expenses can put your entire budget off track. 

Cutting back on just a few of these unhealthy spending patterns can save you a lot for your biweekly goals, helping you save more effectively and helping you make room in your budget for what truly matters. This method is less about cutting out everything you enjoy and more about being mindful where your hard earned money goes, prioritizing goals over those temporary doses of happiness. 

Step 6: Use the Envelope or Digital Jar Method

If you like something more visible to keep track of the progress, consider the envelope or digital jar method. You can label each envelope or jar with the goal, for example, travel, emergency fund, or new gadget. 

This method can make the saving process easier as you can see it, both physically or digitally, building motivation and reminding you why you started in the first place. 

Step 7: Reward Yourself Along the Way

Saving money doesn’t mean you have to restrict yourself from all enjoyment and it’s perfectly okay to reward yourself after hitting certain milestones in your biweekly savings journey. These rewards don’t have to be expensive or luxurious, they could be something as small as treating yourself to your favorite snack, watching your comfort movie, or spending time doing something you love. 

The idea is to keep your motivation alive and associate positive feelings with your saving progress and when you acknowledge your effort and dedication, saving starts to feel less like a burden and more like a lifestyle choice you genuinely enjoy maintaining.

Step 8: Involve a Friend or Family Member

Everything becomes easier and more fun when you’re not doing it alone, which is exactly why it is a considerable option to involve a friend or a family member. If you have a friend, sibling, or even a parent who’s also looking to improve their finances, invite them to join your biweekly savings challenge. 

You can share your progress, encourage each other, and even hold friendly competitions to see who stays the most consistent. This shared accountability helps you stay on track, and it also makes the whole experience less stressful and more meaningful. Sometimes, just knowing someone else is saving alongside you can keep you committed on days when you feel tempted to skip a round.

Step 9: Track Your Progress Regularly

Illustration of a woman happily updating her savings tracker on a pastel pink background, representing tracking biweekly savings progress with calm and motivation.

Tracking your progress is one of the most satisfying parts of this challenge because it allows you to see how your efforts are paying off over time. You can use a notebook, spreadsheet, or even a simple note on your phone to record how much you’ve saved every two weeks.

Watching those numbers slowly increase gives a sense of pride and reassurance that your consistency is working. It also helps you stay organized and aware of your financial growth, keeping your motivation strong and reminding you that slow progress is still progress.

Step 10: Challenge Yourself to Save a Little More Each Cycle

Once you get comfortable with your saving routine and feel more confident about your budget, try increasing your savings amount slightly after every few cycles. You don’t have to jump too high, even adding $5 or $10 extra every two weeks can make a big difference in the long run. 

This small step not only accelerates your savings but also helps you test your limits and improve your money management skills. Gradually challenging yourself ensures that you’re always growing, without making the process feel forced or stressful. Over time, you’ll be surprised at how much more you can save just by gently pushing yourself a little further each time.

Step 11: Keep Your Savings Out of Easy Reach

To make sure you don’t end up spending what you’ve worked hard to save, it’s best to keep your savings in a place that’s not too easily accessible. You can open a separate savings account without a debit card or use a savings app that doesn’t allow instant withdrawals.

Creating this small barrier between your spending money and your savings helps reduce the temptation to dip into your funds for impulsive purchases. When you make your savings slightly harder to reach, you naturally give them the time and space to grow, allowing your money to work for you quietly in the background.

Step 12: Reflect and Reassess Your Progress 

Every few months, take some time to sit down and reflect on your biweekly savings journey. Ask yourself if you’re happy with the pace, whether your goals have changed, or if there’s something you can adjust to make the process easier. Maybe you can afford to save a little more, or perhaps you need to take a short break and reorganize your budget. 

Reflection keeps your plan realistic and aligned with your current lifestyle instead of forcing you into a pattern that no longer works. This step helps you see how far you’ve come and reminds you that saving isn’t a one-time challenge, it’s an ongoing habit that keeps improving with time.

Conclusion

The biweekly savings challenge is proof that you don’t need big jumps to achieve financial stability, just small, steady steps taken consistently. By saving every two weeks, even a modest amount, you build not just a financial cushion but also a mindset of discipline and self-control. It teaches you that saving doesn’t have to feel like a struggle or sacrifice, it’s simply about being intentional with your money and creating a plan that fits your reality. Over time, the effort you put in every two weeks will compound into something meaningful, giving you peace of mind, confidence, and the satisfaction of knowing you’re in control of your financial future.


Money Saving Techniques For Students

October 23, 2025 By Ana Rose

Student life often feels like a constant struggle between academic tasks and making money last till the end of the month. Whether it’s tuition fees, books, daily meals, or transportation, it’s easy for money to slip out faster than you expect in the absence of effective strategies and money management techniques. Saving might sound unrealistic when you’re already living on a tight budget, but what makes it easier, even as a student, is just the habit of being intentional with where the money is going. This article will explore some helpful money saving techniques for students, teaching them to budget smartly, make intentional spending choices, and build healthy financial habits over time that can serve them in the long run. 

 Money Saving Techniques For Students Graphic

Track Where Your Money Goes

The very first step towards saving money is tracking where the money is actually going and knowing your spending habits on a deeper level. As a student, you may underestimate how much you actually spend on those small and seemingly harmless expenses, whether it’s that morning coffee, snacks, or random online shopping sprees. 

You can start by writing your daily expenses, no matter big or small, in a notebook or if you prefer a digital approach, consider creating a spreadsheet or using a tracking app. Once you see the big picture, you’ll often find that small changes, such as skipping coffee run a day, can free up more cash than you’ve imagined. 

Create a Weekly Budget

A happy student creating a weekly budget on a laptop with charts and notes on a pastel pink background, symbolizing smart financial planning and better money management.

Managing money for a whole month can become overwhelming and frustrating which is why creating a weekly budget can be a better option. You can divide your money into smaller and more manageable weekly categories. 

You can decide how much you realistically spend each week, covering essential expenses like food, transport, and study material, and then commit to staying within that spending limit. A weekly budget can help you reset your spending habits more frequently and prevent the panic of running out of money halfway through the month, making it easier for you to set some portion aside for savings as well. 

Always Use Student Discounts

Being a student has its pros too yet many of us fail to see that. Whether it’s coupons, discounts, or student perks, countless companies offer these advantages, you just have to ask or sign up for the student programs. 

Platforms like UNiDAYS, Student Beans, and ID.me offer deals on clothing, electronics, entertainment subscriptions, and even travel. Many local restaurants, cafes, and bookstores also provide student discounts when you show your ID. These small savings add up quickly and can make a noticeable difference in your overall spending, making your student like worth it. 

Buy Used or Digital Textbooks

Textbooks are one of the biggest hidden costs when it comes to student life. Buying new books every semester can eat away your budget faster than you may realize which is exactly why it is essential to look for used copies from older students, online marketplaces, or secondhand bookshops. 

Many universities also have book exchange programs or libraries where they offer free access to required readings to their students. Moreover, whenever possible, choose eBooks as they’re often cheaper and easier to carry. These options can save you hundreds each year without affecting your learning experience in any way.

Cook Instead of Eating Out

Pastel pink illustration of a student cooking a meal at home, surrounded by fresh ingredients, representing saving money by preparing food instead of dining out.

Eating out may sound convenient at times but it’s one of the biggest reasons students struggle to save. Rather than depending on takeouts or dine outs, aim to cook your own meals at home. You don’t have to be a kitchen expert, you just need to start with easy recipes, if you’re a beginner, and steer clear of impulsive takeouts whenever you’re busy or tired. 

Not only does this strategy help you save money, it allows you to eat healthy and hygienic food made at home. While eating out may seem harmless, you may come to realize at the end of the month that you’ve saved a huge chunk of your budget simply by preparing meals at home and avoiding takeouts. 

Limit Impulse Spending

One of the biggest obstacles standing between you and saving money is the temptation to spend or impulse purchase, especially when you’re stressed or bored. An effective strategy to deal with it is to use the 48 hour rule. The 48 hour rule is all about giving yourself the time and space to think over your decision to buy something, if the urge persists, you can buy it, however, in most cases, the temptation to buy that item fades away. 

This small mental shift can help you develop a strong emotional grip over your money, prioritizing a mindful and intentional approach towards your money and controlling it, rather than letting it control you. 

Use Public Transport or Carpool

Transportation is one of those expenses that doesn’t seem like much at first, but when you add it up over the month, it can take a huge bite out of your budget. Whether it’s fuel, ride-hailing apps, or daily parking fees, it all adds up. A practical way to save money is by using public transport whenever possible. 

Many universities have discounted or free bus passes for students, so make sure to take full advantage of those. If public transport isn’t easily available in your area, consider carpooling with classmates or friends who live nearby. Sharing rides helps you save on fuel costs and also reduces wear and tear on your vehicle if you have one. Plus, it’s good for the environment and a great way to bond with people on your route.

Take Advantage of Campus Resources

Universities and colleges often provide more free or low-cost resources than students realize. From free printing credits and library materials to gym memberships, counseling services, and career workshops, these facilities are already included in your tuition fees. Instead of spending extra outside campus for these services, explore what your institution offers and make the most of it.

You’ll be surprised how much you can save just by utilizing what’s already available to you. For instance, using the campus gym instead of paying for an outside membership or borrowing laptops and equipment for projects instead of buying them can make a significant difference in your monthly expenses.

Earn While You Learn

If your schedule allows, finding small and manageable ways to earn money while studying can make a big difference in your financial situation and confidence. You don’t need to take on a full-time job or push yourself too hard, even small opportunities like part-time work, tutoring, freelancing, or remote internships can help you earn extra income without disturbing your studies. 

The money you make, even if it’s modest, can go toward personal expenses, transportation, or savings, easing the financial pressure that often comes with student life. Other than just the money, working while you learn teaches you discipline  and the real value of effort, helping you become more independent and responsible with your finances in the long run.

Save a Portion of Every Payment

No matter how little money you receive, whether it’s from your parents, a part-time job, or a small side hustle, it’s important to build the simple but powerful habit of saving a small portion before you spend anything else, because this small act helps you take control of your money instead of letting your money control you. It doesn’t matter if it’s 5%, 10%, or even a few dollars each time, what matters is that you make saving a non-negotiable part of your routine, just like paying rent or clearing a bill. 

You can make this habit easier by setting up an automatic transfer to a separate savings account the moment any money comes in, so you don’t have to rely on willpower or reminders, and before long, saving starts to feel natural and satisfying rather than restrictive. 

Share or Borrow Instead of Buying

Student life often comes with shared experiences, and this can work in your favor when it comes to saving money. You don’t always have to buy everything you need, sometimes borrowing or sharing can be just as effective. 

Whether it’s books, stationery, kitchen items, or even streaming accounts, sharing resources with friends or roommates can help everyone save a little. For instance, instead of each roommate buying separate cleaning supplies, you can split the cost and share them. These small acts of cooperation not only save money but also build a sense of community and trust.

Use Budgeting and Cashback Apps 

In today’s world, managing money has become much easier thanks to technology. Budgeting and cashback apps can help you stay on top of your finances without too much effort. Apps like Mint, YNAB (You Need A Budget), or PocketGuard let you track your spending, set savings goals, and alert you when you’re overspending. 

Cashback apps such as Rakuten, Honey, or Dosh reward you with a small percentage of money back on purchases you make through their platforms. These digital tools make saving money feel automatic and rewarding, allowing you to make smarter financial decisions with less stress.

Conclusion

Saving money as a student isn’t about cutting out all the fun or living on the bare minimum, it’s about being intentional and aware of how you use your money. When you track your expenses, budget wisely, use available discounts, and take advantage of free campus resources, you start building habits that go far beyond student life. Each small saving decision, whether it’s cooking at home or skipping an unnecessary purchase, adds up and strengthens your financial stability. Remember, the goal is not to be perfect but to be consistent. By practicing these money-saving techniques now, you’ll not only survive student life more comfortably but also set yourself up for long-term financial success.

$10,000 Savings Strategy

October 22, 2025 By Ana Rose

Saving $10,000 may sound like an intimidating goal at first, especially when you’re struggling with bills, inflation, and unexpected expenses that throw your entire budget off track. But what most people don’t realize is that you don’t need to have a six figure salary to save a big amount, you just need a clear and realistic plan, consistency, and a sense of discipline to achieve your goal. This strategy focuses on small and doable steps, making it easy for you to achieve your goals, not just aiming for financial perfection. This article will help you explore some helpful saving strategies, allowing you to build a safety net that gives you peace of mind and control over your money, rather than letting the money control you.

$10,000 Savings Strategy  Graphic

Define Your “Why” Before You Start

Before beginning any journey, it is crucial to associate a ‘why’ and a purpose with your goals. Without a clear target, the whole process may feel like a restriction or punishment, putting your progress at stake. 

Whether it’s to build an emergency fund, pay off a debt, or fund a dream trip, having a clear and realistic goal can help you achieve your target without having the whole process feel like a burden. Your reason gives emotional meaning to your effort. You can write it down, visualize it, and remind yourself of it when the temptation to spend kicks in.

Break the $10,000 Goal Into Smaller Targets

An easier way to look at the goal of saving $10,000 is to break the target into smaller, more manageable chunks so that the big picture seems less overwhelming and intimidating. You can think in terms of small milestones, for example, $833 a month, $192 a week, or about $27 a day. 

This way, the goals feel achievable and what makes this approach considerable is that it gives you quick wins, making it easier for you to stick with the challenge and stay motivated along the process. 

Create a Dedicated Savings Account

Keeping your savings in the same account as your regular spending can be a big obstacle between you and financial freedom. The smart approach is to create a separate savings account dedicated solely to your savings, goals, and aims. 

This way, your savings can grow in peace without any drama or distraction, instead of being mixed up with your daily expenses. You can even open a high-yield savings account to earn extra interest while your money grows quietly in the background. Separating your accounts builds discipline, reduces temptation, and makes it easier to track your progress toward your $10,000 goal.

Track Every Dollar You Spend

Sometimes you can’t fix what you don’t track and monitor, which is exactly why it is essential to know your spending habits and where the money is actually going. Spend one month writing down every expense, no matter big or small. Whether it’s your daily coffee run, a shopping spree, a big purchase, or something as small as a light snack, keep track of where your hard-earned money is going. 

By the end of the month, you may come to realize that these small and seemingly harmless expenses eat away a big chunk of your income. By identifying your unhealthy spending patterns, you can alter your habits and redirect your money towards something more meaningful that can serve you in the long run. 

Apply the 50/30/20 Rule

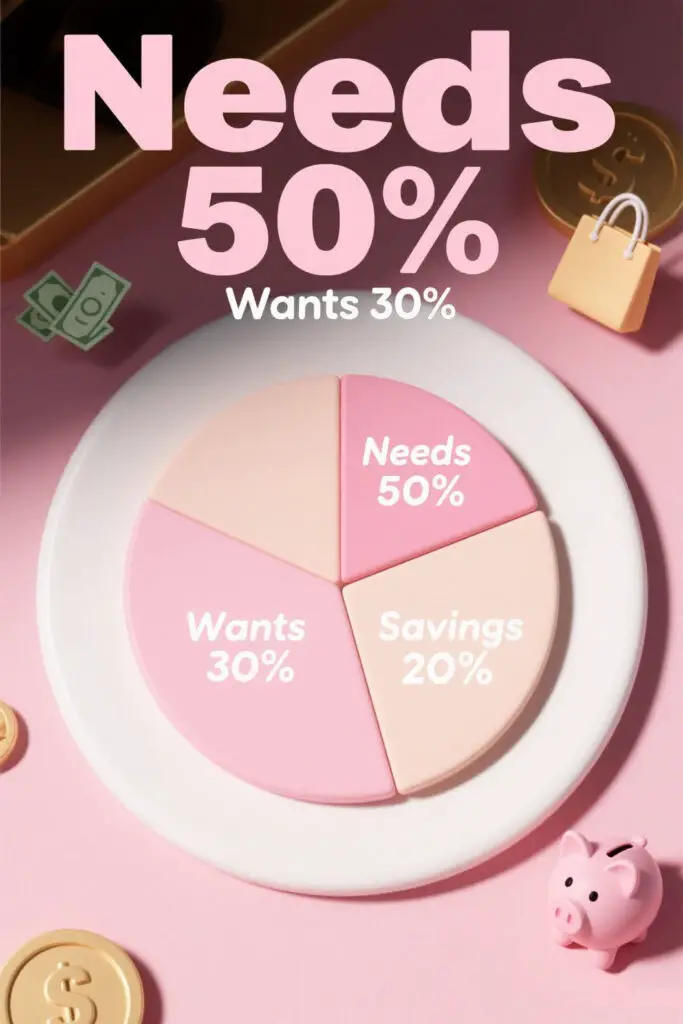
Illustration of a 50/30/20 budgeting pie chart on a pastel pink background showing income division for needs, wants, and savings with soft golden highlights symbolizing financial balance and planning.

Budgeting techniques can give structure and more discipline to your money, finances, and more importantly, your aim and target. You can apply the 50/30/20 rule in which 50% of the income is spent on needs and those essential expenses such as rent, bills, groceries, or transportation, 30% of your paycheck is assigned to your wants or those nice-to-have-items including clothes, takeouts, or those daily coffee runs, and lastly, 20% of your monthly income goes to savings, investment, or paying off debt, if there is any. 

However, if you want to modify the rules to make saving more easier and effective, try changing the percentages of the spending categories, for example, you can spend 20% of your income on wants and save 30% for your savings. 

Embrace a “No-Spend” Challenge

Pastel pink illustration showing a calendar marked “No-Spend Week” and a woman adding coins to a savings jar, representing mindful spending and self-discipline during a no-spend challenge.

The no spend challenge is one of the most simple yet powerful saving strategies that helps you control your impulse to spend and save more mindfully. Choose a week or weekend each month where you aim to spend only on those basic and essential expenses, including rent, food, groceries, transportation, or utilities. 

Aim to stop spending money on those non-essential spending categories including shopping, subscribing to unnecessary services, or takeouts. This challenge might feel tough at first but what makes it motivating to stick to the challenge is knowing that you’ll enjoy the freedom that along with not feeling pressurized to swipe the card every time you’re tempted to purchase something. 

Cut Recurring Costs Without Feeling the Pain

One of the most effortless ways to increase your savings without making life harder is to review your recurring expenses, the ones that quietly drain your money each month. These could include subscription services you rarely use, premium app memberships, expensive phone plans, or even small automatic payments that you may have forgotten about. 

Go through your bank statement and identify what’s truly necessary and what can be cut or replaced with a cheaper option. You can easily save $50–$200 a month just by trimming these unnoticed costs. 

Boost Income Through Side Hustles

When you feel like there’s nothing left to cut from your budget, the next best move is to look for ways to increase your income. Side hustles are no longer just a trend, they’re a powerful tool for building financial freedom. Even a small extra income stream can help you reach your $10,000 goal faster without having to sacrifice your essentials or comfort.

You can start by exploring your skills and hobbies, for example, if you’re good at writing, designing, or social media, consider freelancing online, if you enjoy baking, crafting, or tutoring, turn it into a weekend side gig. 

Automate and Forget

One of the smartest ways to save money is to remove the temptation to spend it. Automating your savings ensures that you save first and spend later, not the other way around. Set up an automatic transfer from your main account to your dedicated savings account as soon as your paycheck arrives. Even a fixed amount like $200–$300 each payday can quietly accumulate while you focus on other things.

When savings happen automatically, it becomes a habit instead of a chore, and you no longer have to rely on motivation or willpower because the process runs on its own. 

Make Saving Fun and Visual

Saving doesn’t always have to feel like a restriction, it can actually be enjoyable if you turn it into a game. Create a visual savings tracker where you color in boxes or fill jars as you hit milestones, like $1,000, $2,500, or $5,000. This visual progress keeps you excited and motivated, reminding you how far you’ve come instead of how far you still have to go.

You can also try fun savings challenges like the envelope method, where you set aside a small amount each week, or the “round-up” method, where every time you spend, the change is rounded up and added to savings. 

Avoid Lifestyle Inflation

As you start saving and possibly earning more, it’s tempting to upgrade your lifestyle, whether it’s a nicer phone, more frequent dining out, or expensive shopping “rewards.” This is what’s known as lifestyle inflation, and it’s one of the biggest threats to long-term savings.

The trick is to resist the urge to increase your expenses every time your income grows. Instead, maintain your current lifestyle and channel that extra income directly into your savings or investments. For example, if you get a raise at work, pretend it never happened, and immediately set up an automatic transfer for that amount.

Reinvest and Keep the Momentum 

Reaching your $10,000 goal is a major achievement, but it’s not the finish line, it’s the foundation. Once you’ve built that savings cushion, use it wisely to create more growth. You can put part of it into a high-yield savings account, a fixed deposit, or even explore low-risk investments like index funds or mutual funds, depending on your comfort level.

Saving isn’t just about hitting a number, it’s about developing habits that protect your financial future. Continue saving even after reaching your goal, whether it’s for your next big milestone or simply to strengthen your emergency fund. 

Conclusion

Saving $10,000 is more than just setting money aside, it’s a personal journey that builds patience, control, and confidence in how you manage your finances. Along the way, you realize that financial freedom isn’t about how much you earn, but how consistently you save and how wisely you spend. Each small decision to hold back from unnecessary purchases and stay focused on your goal adds up, slowly creating a sense of stability and peace of mind. When you finally reach your $10,000 goal, it won’t just feel like a financial win, but a reminder of your discipline, your growth, and your ability to take control of your future one mindful choice at a time.
Saving Goals 2025

October 21, 2025 By Ana Rose

Each year comes with a quiet hope that this year might be different from others in terms of savings and finances, but 2025 isn’t just another year, it’s a chance to reset your habits and build a new relationship with saving and spending. Saving money isn’t just about numbers in your bank account or cash in wallet, it’s more about creating peace for yourself, having choices, and controlling money rather than letting it control you. Whether your goal is to build an emergency fund, save for a big purchase in future, or to simply stop living paycheck to paycheck, 2025 is your year to do it in a way that feels realistic and balanced. This article will help you explore some thoughtful and realistic saving goals that can genuinely change your financial story in 2025. 

Saving Goals 2025 Graphic

Build a 3–6 Month Emergency Fund

Clear jar labeled “Emergency Fund” with coins, planner, and calculator on a pastel pink background with golden highlights, symbolizing steady financial preparation and saving for emergencies.

Life doesn’t always go as planned, which is exactly why it is necessary to build a safety cushion in case of unforeseen circumstances. Whether it’s job loss, a sudden medical bill, or your car needing repairing, unexpected expenses seem to show up at the worst possible moment. 

Start by saving enough to cover one month’s worth of expenses, then build it up to three months, and eventually aim for six. You don’t have to stress about small numbers, even if you save $100 or $200 each month, you’re still moving in the right direction. What truly matters is that you choose to keep going even when the circumstances are against you. 

Automate Your Savings 

Saving money can be hard when it depends solely on your willpower to set money aside, which is exactly why automation of transfers is a helpful trick. Set up a system where a fixed portion of your income is transferred to your savings account the moment your paycheck hits your checking account. 

This way the process of saving becomes effortless and less demanding, happening quietly in your background, while letting your savings grow in peace, without any drama or distraction. Once your savings are automated, you’ll be surprised at how much less you worry about “forgetting to save” or running short by the end of the month.

Pay Off High-Interest Debt First

If you’ve been carrying credit card balances or small personal loans, you already know how heavy that can feel. Debt has a way of silently draining not just your money but also your energy and confidence, so make it one of your biggest 2025 goals to reduce or ideally, eliminate your high-interest debt. 

Begin by listing out all your debts, note their interest rates, and focus on paying off the one that costs you the most every month. You don’t have to do it all at once, small and consistent payments add up faster than you think.

Save for the Big Things You Care About

It’s usually so easy to spend on little things that we forget about the bigger picture that truly matters. Whether it’s moving into your own place, funding your studies, or buying a car, take a few minutes this year, sit down, and figure out what you truly want. 

Seeing your dreams written on paper makes them feel real and gives you something to look forward to and work for. You can then break down your goals into smaller and more doable chunks, for example, if you want to save $1200 for a trip at the end of the year, instead of struggling when the time comes, try saving $100 each month, which is much easier than handling a huge sum. This method can turn your dreams into something you can actually achieve with one small and meaningful step at a time. 

Start Investing 

A lot of people think that investing is reserved for the wealthy, but it’s not true. All you need is  a plan, a little consistency, and the patience to let your money do the work for you, because even the smallest investments, when done regularly, can turn into something truly meaningful in the long run. 

You could explore mutual funds, index funds, or retirement plans, things that let your money quietly grow over time. The power of compounding is incredible, as money you invest today keeps growing on its own, and years from now, you’ll look back and be grateful you started small instead of waiting for the perfect time that never comes.

Join a Fun Savings Challenge

Savings tracker and notebook labeled “Savings Challenge 2025” on a pastel pink background with golden accents, representing a fun and creative approach to saving money.

Saving, at times becomes boring, which is exactly why it is smart to take help of challenges that make the whole process fun and a lot more easier. Join a savings challenge, like the 52 week challenge where you save a small amount in the initial phases of the challenge and as you move forward, the amount grows too. You can also consider the $1000 savings challenge that breaks your goal into small and more manageable chunks, turning that big goal into small weekly steps. 

You can even create games of your own, for example, every time you skip coffee or fight the urge to shop impulsively, transfer that amount to your savings. This way, not only do you manage to put money aside but the whole process feels less overwhelming and more fun, motivating you to stay consistent and committed to it. 

Try a “No-Spend” Month

Sometimes the best way to understand your spending habits is to pause them altogether for a while. A “no-spend” month is not about punishing yourself or living uncomfortably, it’s about becoming more aware of where your money actually goes. 

Choose one month in 2025 and commit to spending only on the things you genuinely need, such as groceries, bills, and absolute essentials. 

Create a “Fun Fund” for Guilt-Free Spending

Saving shouldn’t mean cutting all joy out of your life, in fact, one of the best ways to make saving reasonable is to build room for fun in your budget. A “fun fund” can be a separate little fund for treats, experiences, or things that make you happy without guilt. 

This fun fund could be for anything you enjoy, whether it’s a movie night with friends, your favorite meal, or a new outfit you had your eyes on. This way you can still enjoy what you like without any guilt of spending on those non-essential expenses. 

Save for Retirement

Retirement might seem like something that belongs far in the future, but the truth is, time moves faster than we think. Even if you can only put aside a small amount each month, it’s worth it, because what matters most is consistency, not perfection.
If your job offers a retirement plan, take advantage of it, especially if they match your contributions. If not, consider opening your own savings or investment account designed for long-term growth. 

Build a Health and Wellness Fund

Good health and financial peace are deeply connected, yet most of us don’t realize it until an unexpected doctor’s bill suddenly throws everything off balance. That’s why having a small health and wellness fund isn’t just a smart money move, it’s an act of genuine self-care. It doesn’t have to be a big amount, just a small, steady contribution each month that slowly grows with time. 

When you know there’s money safely set aside for health-related expenses, you stop feeling that anxious hesitation every time something unexpected comes up. You won’t have to choose between your well-being and your wallet, and that sense of relief, that quiet comfort of being prepared, is absolutely priceless.

Start Saving for Holidays and Special Occasions Early

Every year, holidays and celebrations seem to sneak up on us, and suddenly we’re spending way more than we planned. Whether it’s Christmas, Thanksgiving, birthdays, or wedding gifts, these occasions bring happiness, but they can also bring financial stress if you’re not prepared.

Take a few minutes at the start of the year to list all the events you know are coming, estimate how much you’d like to spend, and divide that number across the remaining months. This way, by the time the occasion arrives, you already have the money ready, and you can celebrate freely without feeling guilty or anxious about overspending. 

Track and Celebrate Every Little Win 

The journey of achieving your goals for the year isn’t just about depriving yourself of all the fun and making it feel like a punishment, it’s about liberating yourself of the unhealthy spending habits and having more peace and control when it comes to finances. Along the way, what truly matters is that you appreciate yourself and celebrate mini milestones as you move towards your big goal. 

Every time you hit a target, whether it’s saving your first $100 of the journey or paying off debt, stop and appreciate yourself for the consistency and effort. 

Conclusion

Saving money isn’t about denying yourself the good things in life, it’s about giving yourself the freedom to enjoy them without guilt, fear, or stress. It’s about feeling safe in your own choices and confident that no matter what life throws your way, you’ll be okay. 2025 can be the year you break old habits, start fresh, and build a healthier, calmer relationship with money. So start small, be kind to yourself when you slip, and keep going, even slow progress is still progress. With each goal you set and each bit you save, you’re not just improving your finances, you’re building a future that truly feels like yours.

  • « Go to Previous Page
  • Go to page 1
  • Interim pages omitted …
  • Go to page 42
  • Go to page 43
  • Go to page 44
  • Go to page 45
  • Go to page 46
  • Interim pages omitted …
  • Go to page 170
  • Go to Next Page »

The Latest Blog Posts:

  • 14 Profitable Things To Sell On eBay June 20, 2026
  • Mason Jar Crafts To Make And Sell June 19, 2026
  • 12 Best Jobs for Retired Teachers  June 18, 2026

As Featured In:

Just Start Investing Press Strip 2020 B&W

Follow Us:

  • Facebook
  • Twitter
  • Pinterest

Copyright © 2026 · Just Start Investing LLC

  • Contact Us
  • Blog
  • Privacy Policy / Disclaimers